


QUALCOMM (QCOM) Could Be 11% Undervalued On Arm Ruling And Amazon AI Push
A Delaware federal jury ruled that Arm Holdings breached a key licensing deal with QUALCOMM (QCOM), confirming QUALCOMM’s right to keep developing custom CPUs and supporting its AI and data center chip roadmap with Amazon.
QUALCOMM’s share price has slipped over the past month, with a 30-day share price return of 4.18% down, even though the 90-day share price return of 1.18% up and 1-year total shareholder return of 8.13% suggest longer term holders have still seen gains. Recent headlines around the Arm verdict, the $4.6b shelf registration, and fresh AI data center partnerships, as well as competitive pressure in data center deals, have all fed into shifting expectations about QUALCOMM’s growth opportunities and risk profile.
Scan how QUALCOMM’s legal win and AI push stack up against other chip players by reviewing a curated set of 92 AI infrastructure stocks positioned for the next wave of data center demand.
QUALCOMM now trades around US$172 while analyst targets cluster near US$194, and one intrinsic estimate sits slightly above spot. Which of those anchors deserves more weight in your valuation work next?
Most Popular Narrative: 11% Undervalued
The most followed QUALCOMM thesis pegs fair value around $194, a touch above the current $172.62 share price, and leans heavily on non handset growth delivering against ambitious long term targets.
Execution on the AWS custom silicon and optical connectivity agreement, which could total up to US$60b of product purchases over ten years and is expected to start contributing from the December 2026 quarter, would support Qualcomm’s new data center revenue goals of US$5b in fiscal 2027 and US$15b in fiscal 2029 and could become a key driver of long term revenue growth.
See why 632 investors see QUALCOMM as 11% undervalued.
Result: Fair Value of $194.13 (UNDERVALUED)
Still, Qualcomm’s reliance on cyclical smartphones, along with the risk that ambitious AI and data center targets slip on timing, could quickly challenge that 11% undervalued story.
Find out about the key risks to this QUALCOMM narrative.
Another View: QUALCOMM Through The Earnings Lens
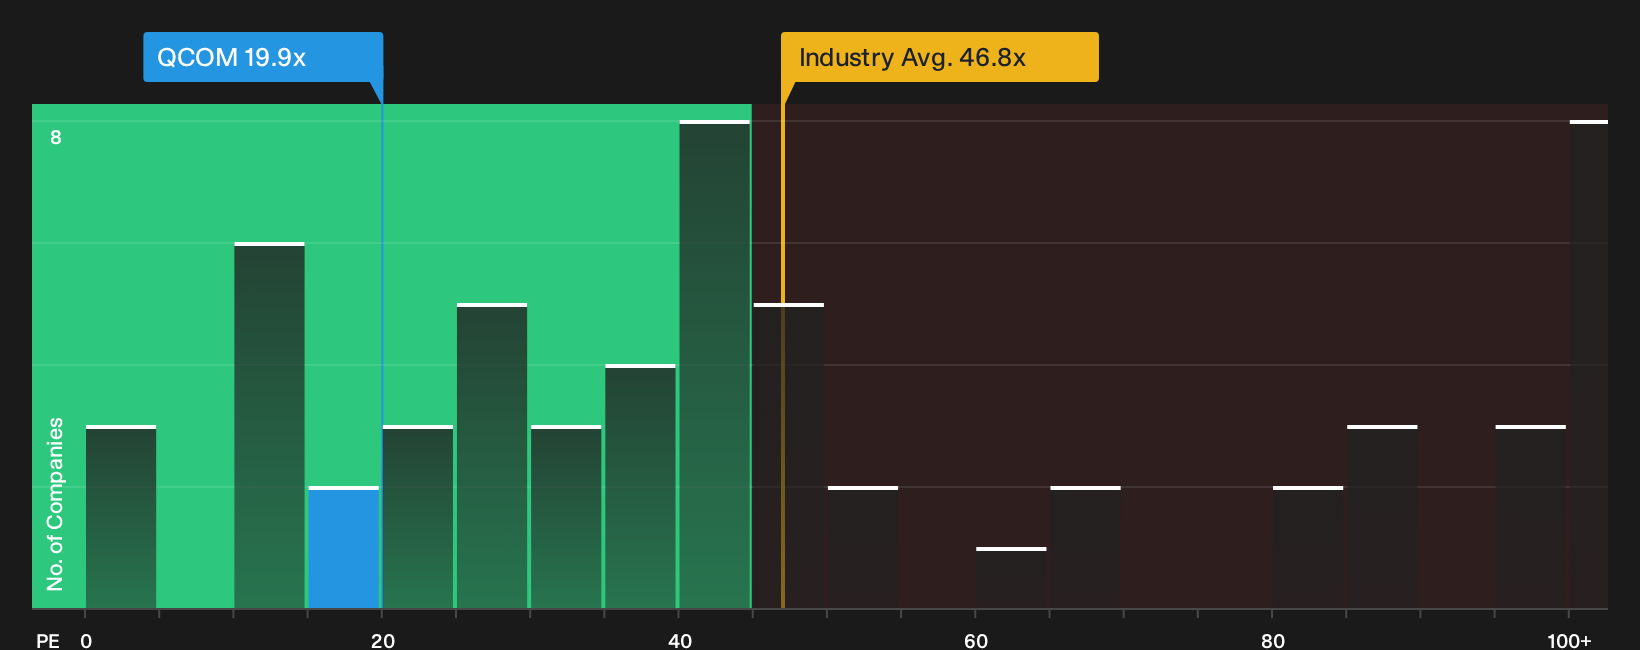
There is a different signal when QUALCOMM is viewed through its P/E. The stock trades at 19.9x earnings, while the US Semiconductor industry sits near 46.8x and peers average 61.9x, and the fair ratio is 30.3x. That gap can look like a margin of safety or a warning that expectations stay muted. Which side do you lean toward?
To pressure test that earnings based view against detailed valuation work, including how that fair ratio might change as QUALCOMM’s mix shifts toward AI and data center revenue, See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out QUALCOMM for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the QUALCOMM story so far. Act quickly, review the numbers, weigh both sides, and then ground your own judgment in the 3 key rewards and 1 important warning sign.
Looking for more QUALCOMM sized opportunities?
QUALCOMM gives a lot to think about on its own, yet your returns often hinge on what you own alongside it. Do not leave that to chance.
- Target stronger upside potential by scanning a curated pool of quality candidates using the 20 high quality undiscovered gems.
- Prioritise resilience and sleep better at night by searching through a 32 resilient stocks with low risk scores that filters for sturdier fundamentals and steadier profiles.
- Aim for a better price to quality mix by running your next idea through a 32 high quality undervalued stocks that surfaces stocks where expectations look more conservative.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com