


Greatland Resources And 2 Australian Undervalued Stocks To Own
Australian markets just absorbed a sharp tech and AI sell off across Asia, which pushed many growth stories out of favour and left investors hunting for steadier cash generators. That kind of reset can create opportunities to focus on companies where cash flows matter more than hype. This article highlights three Australian stocks that screen as potentially undervalued on cash flow and explains what makes each one worth a closer look.
The three stocks below are only a small sample of the idea. The full screen surfaces 8 more companies that also align with this cash flow and valuation theme and are not covered here.
If you want to go beyond this short list and identify candidates that fit your own criteria, head straight into the Undervalued Stocks Based On Cash Flows screener to analyze, filter and focus on the highest conviction opportunities.
Greatland Resources (ASX:GGP)
Greatland Resources is a gold and copper producer whose investment story is closely linked to the Havieron project, where potential mine cash flows support its inclusion in this cash flow focused screener.
Greatland Resources generates about A$2.26b from its Telfer Havieron operation, reflecting a concentrated gold copper profile, and the stock carries a market value around A$6.56b.
This link between a single large producing asset and potential future cash generation is what makes Greatland Resources notable for investors monitoring this screener.
"The primary driver of Greatland’s future is the gold price. As a single-asset developer moving toward production, it offers significant operational leverage to gold."
Changes in one key input for that asset are likely to be closely watched in relation to potential changes in cash flows and valuation.
That kind of single asset focus makes it even more important to read the full narrative for Greatland Resources to see how the cash flow story could evolve beyond the headline risk.

Ansell (ASX:ANN)
Ansell is a global protective gear specialist. For this cash flow focused screen, the key interest is its Healthcare arm, where recurring glove and medical consumable sales feed into the cash generation that underpins the valuation case.
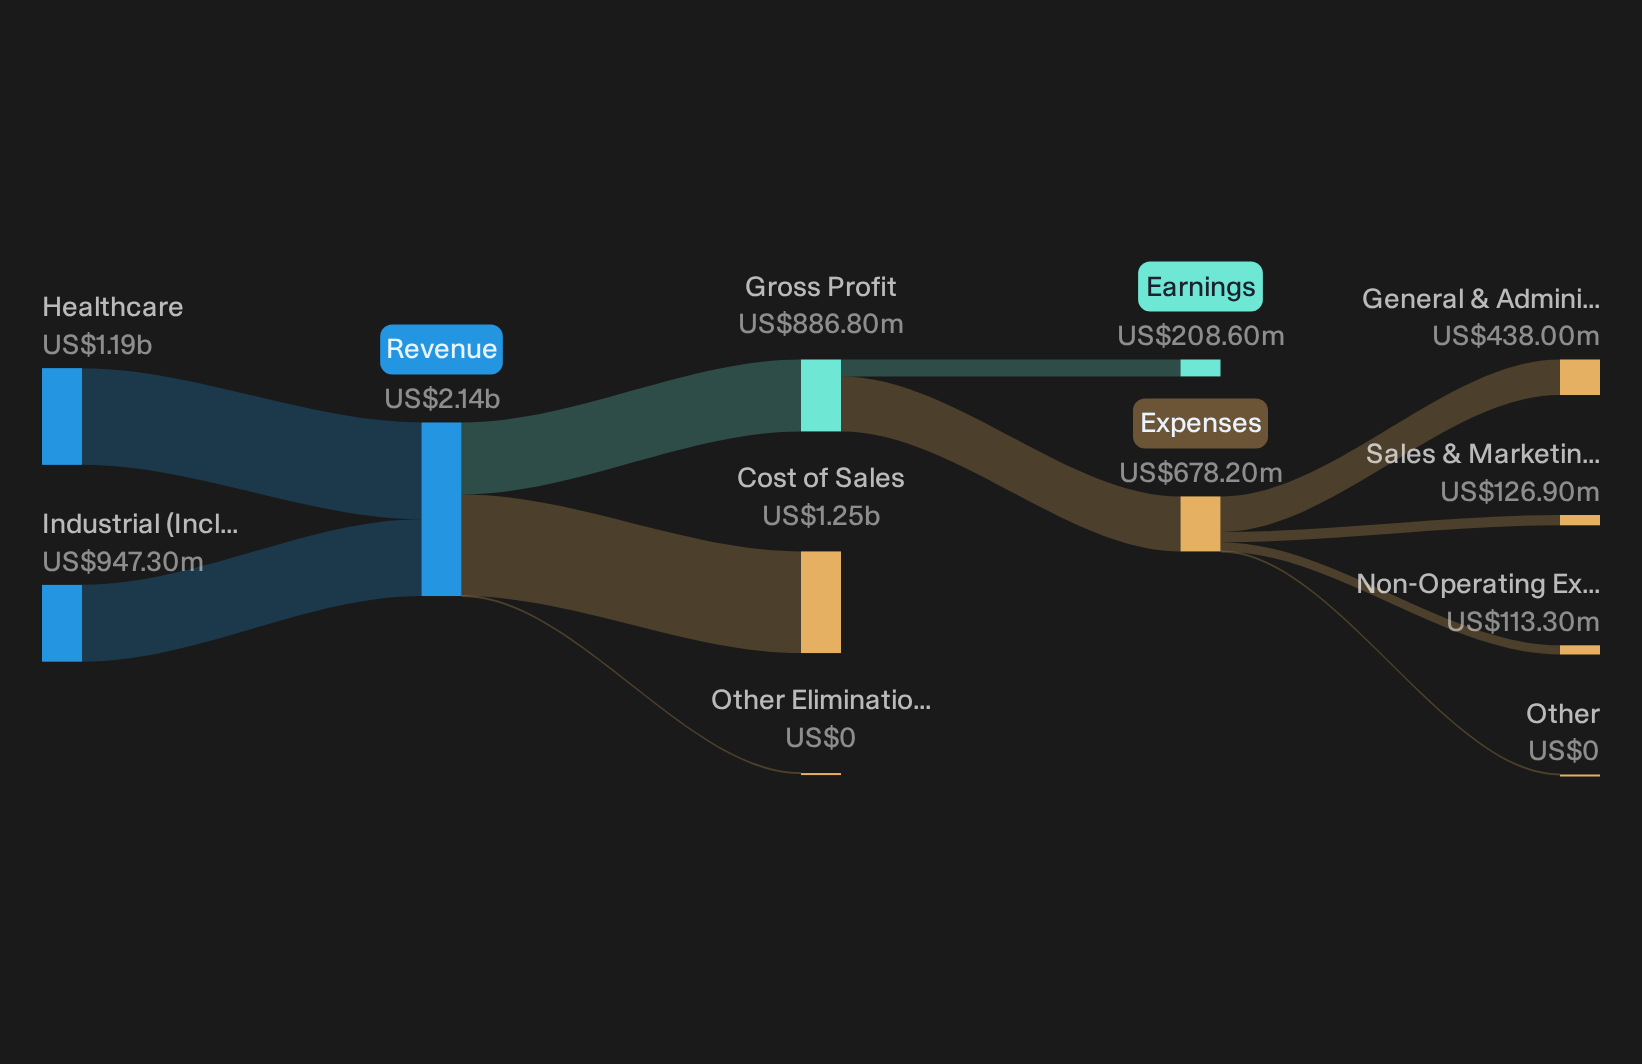
Ansell earns about US$1.19b from Healthcare and US$947 million from Industrial protection, and the stock has an equity value of roughly A$6.32b.
Ansell’s healthcare driven cash flows and global reach give investors a way to anchor on recurring demand rather than short term sentiment swings.
"Ansell is well placed to capture increased structural demand in PPE, driven by tightening workplace-safety regulation, rising healthcare and hygiene standards, and accelerating industrialisation in emerging markets. Volatility in raw-material prices (nitrile, latex, energy), freight disruptions, and trade/tariff risks can pressure margins."
One risk to consider is what happens if a subtle shift in how that protective gear is sourced and priced feeds directly into the cash flow line that investors are counting on.
When that sourcing pressure starts to bite, the full narrative for Ansell shows how Ansell’s pricing power, product mix and capital choices could still accelerate long term cash generation.
JB Hi-Fi (ASX:JBH)
JB Hi-Fi is a large-format electronics and appliances retailer where high-volume store and online sales help drive the cash flows that underpin its appearance in this undervalued-on-DCF screen, giving value-focused investors another consumer-facing option tied to everyday discretionary spending.
JB Hi-Fi earns A$7.42b in Australia, A$2.94b from The Good Guys, A$430 million from New Zealand and A$273 million from e&s, and the group carries a market value of about A$7.87b.
"The acquisition of e&s is expected to enhance JB Hi-Fi's access to premium home appliances and expand the customer base to include builders and commercial clients, potentially boosting revenue growth."
The real swing factor for JB Hi-Fi’s cash flow story is how one quiet shift in its pricing power and cost base plays out from here.
When that pricing and cost equation really shifts, the full narrative for JB Hi-Fi shows how JB Hi-Fi’s cash engine could accelerate or stall as consumer demand cycles again.

Seeking Alternatives Before The Crowd
Fresh ideas move first. Once momentum hits, breakout stories can be flying or dropping before most investors react. Scan what is still under the radar for now and act now.
- Target income that keeps working while you sleep by reviewing the 3 dividend fortresses that aim to keep payouts flowing even when sentiment turns.
- Review infrastructure-related opportunities by scanning the 92 AI infrastructure stocks that are connected to data centers, chips and networks.
- Consider the next materials cycle by checking the 16 top copper producer stocks that are linked to long term electrification and grid upgrade themes.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com