


Twilio (TWLO) Joins The Equal Weight Index As The Bull Case Tests Valuation
Twilio (TWLO) just saw a reshuffle in its index footprint, being dropped from two Russell small-cap composites and joining the S&P 500 Equal Weighted Index, a change that can alter how certain funds trade the stock.
Against that index shuffle, Twilio’s share price has had strong momentum this year, with a 30 day share price return of 16.9% and a year to date share price return of 96%. The 1 year total shareholder return of 151.4% and 3 year total shareholder return near 4x highlight how sentiment has shifted over time, despite a weaker 5 year total shareholder return that is still down 26%.
Spot 39 profitable AI stocks that aren't just burning cash that, like Twilio, are tied to AI driven customer engagement and could be setting up for their own sharp index and momentum shifts.Twilio just delivered strong operational momentum and a sharp share price swing. The real tension now is simple: Are you paying a fair price for that progress, or a premium built on recent excitement?
Most Popular Narrative: 18% Undervalued
On the most followed view, Twilio’s fair value sits at $330 per share, above the last close of $271.12, which frames the current rally as incomplete rather than overextended.
Analyst consensus anticipates AI adoption and conversational automation will incrementally expand Twilio's TAM and margins, but this view may understate Twilio's emerging role as the infrastructure backbone for the next generation of global customer interactions, positioning it to capture a majority share of rapid acceleration in AI-powered messaging, voice, and orchestration. This dynamic could drive compounding top-line beats and material margin expansion as software-driven revenue mix outpaces expectations.
See why 9 investors see Twilio as 18% undervalued.
The fair value estimate of $330 is built using a 9.29% discount rate and assumes Twilio grows revenue at about 14.1% a year with profit margins eventually at 10.9%. Those inputs sit alongside a requirement that the stock trades on a P/E of 73.6x around 2029 earnings of $900.8m, which is a much richer multiple than the 21.0x applied to the broader US IT sector in the same framework.
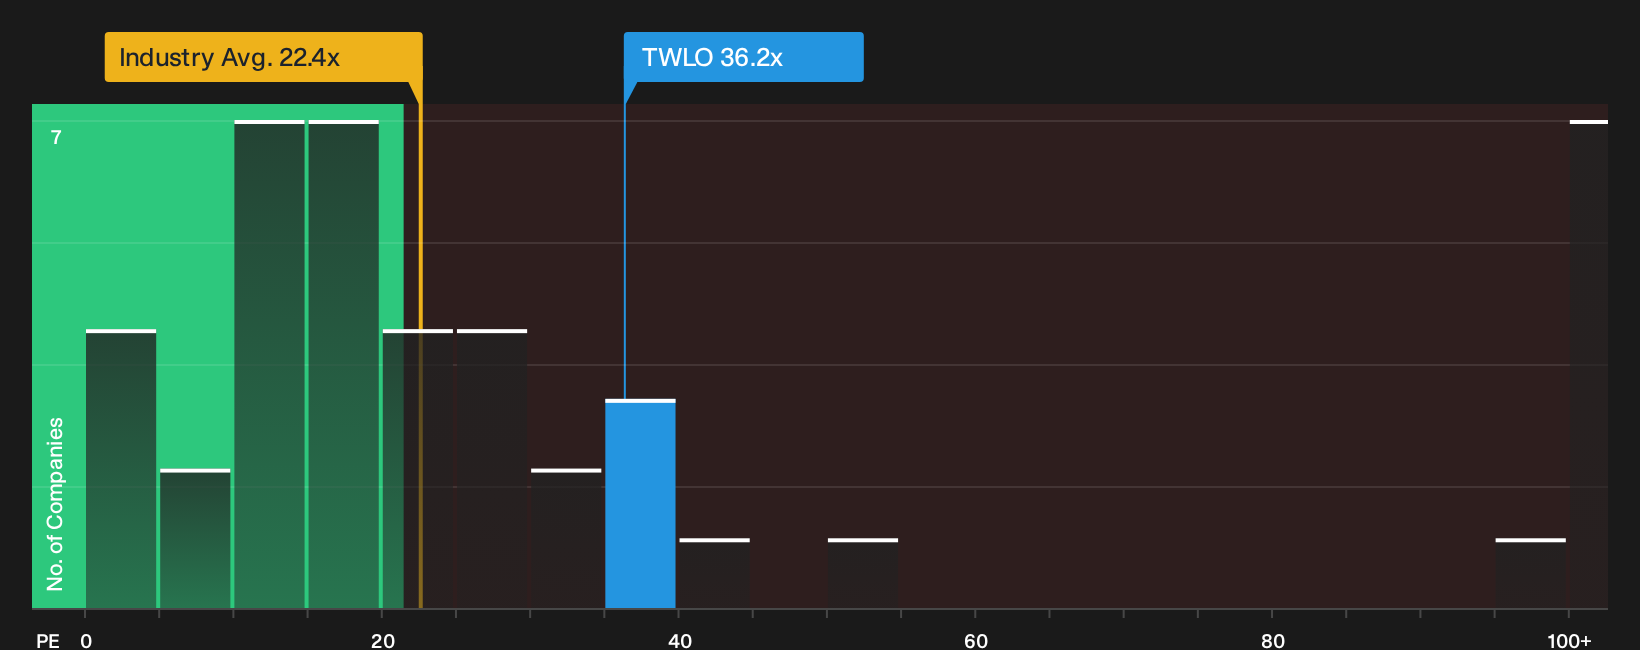
For that narrative to hold, you would need to be comfortable that Twilio’s current 20.6% net margin can support a path to lower but still double digit profitability while earnings decline by 27.1% a year over the next 3 years, then rebase to a smaller but higher quality profit pool. You would also need to accept that today’s 36.2x P/E could stretch meaningfully from here over time, despite the stock already screening as expensive against an estimated fair P/E of 19.6x and the US IT industry average of 22.4x.
None of this makes the narrative right or wrong. It simply spells out the trade off. The story prices in Twilio as a long term AI customer engagement platform with earnings power that justifies a P/E multiple that is more than 3x the fair ratio estimate and materially above the sector anchor, even though the discounted cash flow work on future cash flows comes out lower at $215.22 per share.
Result: Fair Value of $330 (UNDERVALUED)
Still, the bullish Twilio story can crack if privacy rules tighten in ways that limit data rich messaging, or if larger cloud rivals keep squeezing API pricing.
Find out about the key risks to this Twilio narrative.
Another View: Twilio On Earnings Multiples
A different lens on Twilio cuts the story very differently. The stock trades on a P/E of 36.2x, which is well above the fair ratio estimate of 19.6x and the broader US IT sector at 22.4x, even though it sits below a peer average of 61x.
In plain terms, that gap suggests you are paying a premium price that could compress if sentiment cools, even if peers stay more expensive. The question is simple: Are you comfortable owning a business that screens richer than the sector anchor while future earnings are forecast to decline 27.1% a year over the next 3 years?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on whether Twilio’s recent run and competing narratives really add up. Move quickly, review the full data stack, and weigh both the upside drivers and pressure points through 1 key reward and 4 important warning signs
Looking for more investment ideas beyond Twilio?
If Twilio has your attention, do not stop there. Broader opportunity comes from comparing it with other businesses filtered for quality, value, and resilience.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (25 results) so you are not relying on optimism alone.
- Hunt for quality at a discount by scanning the 32 high quality undervalued stocks that combine strong cash generation with valuation metrics that still look reasonable.
- Prioritise stability and income by checking the 7 dividend fortresses that pair higher yields with balance sheets designed to handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com