


Porch Group (PRCH) Shares Slid, So What Is Driving Attention Now?
Porch Group (PRCH) set a new marker for its insurance ambitions after agreeing to acquire Allied Trust's insurance carrier and managing general agency, in a deal aimed at expanding coverage across Louisiana and additional states.
Porch Group’s latest deal talk follows a sharp share price run, with a year-to-date return of 78.31% and a 90-day gain of 19.13%. However, recent trading has cooled, with the 7-day return down 5.03% and the 1-day move down 4.53% as investors reassess both growth potential and execution risk.
Scan for other insurers that are trying to scale like Porch Group by filtering for list of solid balance sheet and fundamentals (25 results) that could better withstand acquisition and expansion shocks.
After a rally that has already been strong, the pullback raises a simple tension for Porch Group. Has the market already priced in most of the Allied Trust opportunity, or is meaningful upside still in front of you as an investor sizing up valuation next?
Most Popular Narrative: 21% Undervalued
Porch Group’s most followed valuation story pegs fair value at $20.79 per share versus the last close of $16.44. This highlights a clear gap between the market price and the narrative’s cash flow view of the stock.
The analysts have a consensus price target of $20.79 for Porch Group based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be $753.0 million, earnings will come to $80.6 million, and it would be trading on a PE ratio of 44.2x, assuming you use a discount rate of 7.2%.
See why 7 investors see Porch Group as 21% undervalued.
Result: Fair Value of $20.79 (UNDERVALUED)
Still, the Porch Group story can shift quickly if execution on the fee based insurance model stumbles or if revenue volatility seen around EIG resurfaces.
Find out about the key risks to this Porch Group narrative.
Another View: Porch Group Looks Expensive On Sales
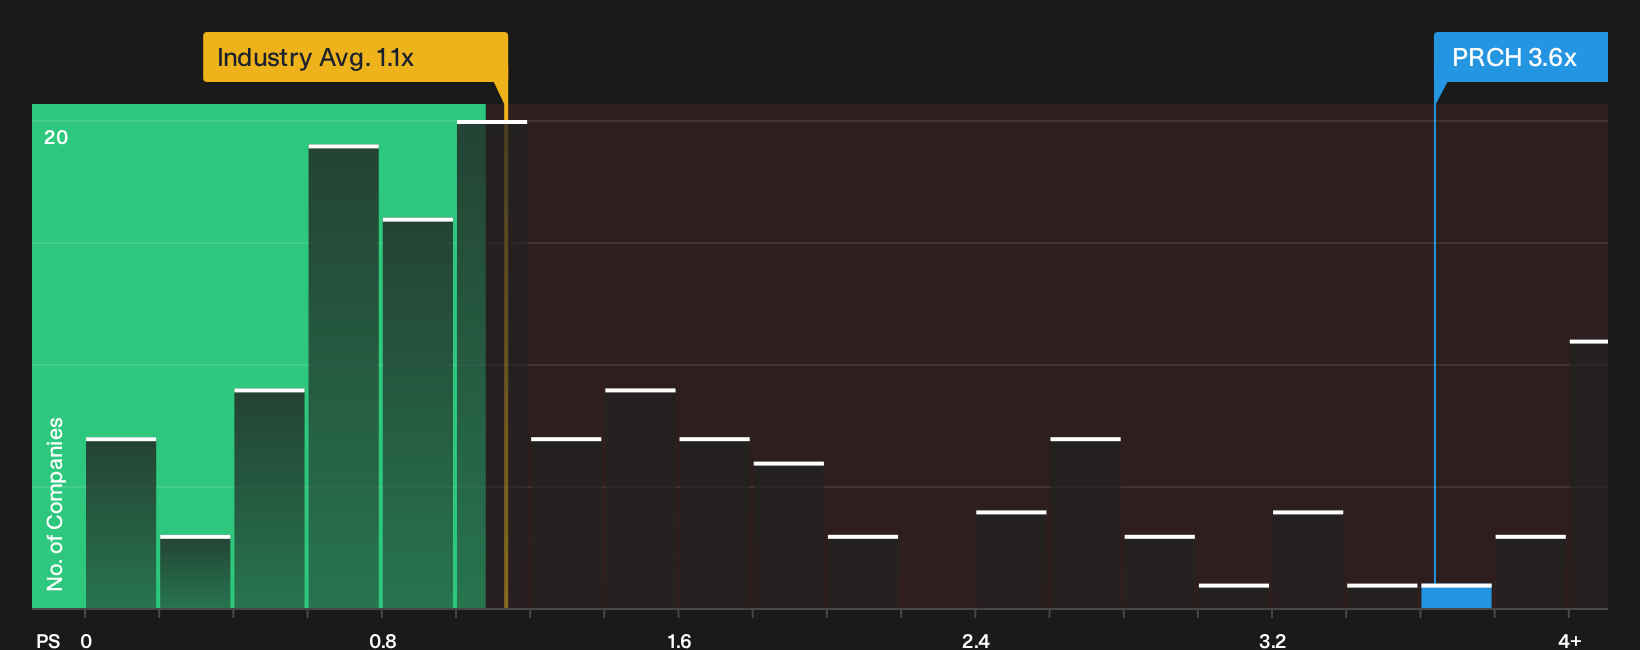
Porch Group screens very differently when the focus shifts from cash flows to simple sales multiples. The stock trades on a P/S of 3.6x, which is much higher than both the US Insurance industry at 1.1x and peer average at 0.9x, and also sits above a fair ratio estimate of 1.9x. This raises the question of how much execution risk is already baked into the price.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Porch Group are evident, with both risk flags and reward markers in play. Move quickly, review the full breakdown, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Porch Group?
Porch Group gives you one lens on risk and reward. Broaden your opportunity set by scanning other companies with different strengths, balance sheets, and income profiles.
- Explore potential opportunities by focusing on companies that trade below what their fundamentals suggest with the 32 high quality undervalued stocks.
- Prioritise resilience and support more stable portfolio behaviour by checking the 32 resilient stocks with low risk scores for businesses with steadier risk profiles.
- Identify companies that may not yet be widely followed by running through the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com