


3 Stocks That Could Be Undervalued By Up To 48.6% According To Estimates
Over the last 7 days, the United States market has experienced a 1.6% decline, yet it remains up by 12% over the past year with earnings projected to grow by 17% annually. In this environment, identifying stocks that are potentially undervalued can offer opportunities for investors seeking to capitalize on discrepancies between current prices and intrinsic values.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Zions Bancorporation National Association (ZION) | $61.78 | $123.40 | 49.9% |
| Textron (TXT) | $73.80 | $143.61 | 48.6% |
| SouthState Bank (SSB) | $99.17 | $192.64 | 48.5% |
| Signet Jewelers (SIG) | $107.96 | $213.75 | 49.5% |
| Orange County Bancorp (OBT) | $36.34 | $71.84 | 49.4% |
| Northeast Bank (NBN) | $123.75 | $240.31 | 48.5% |
| M&T Bank (MTB) | $216.05 | $419.36 | 48.5% |
| Live Oak Bancshares (LOB) | $34.42 | $68.81 | 50% |
| KeyCorp (KEY) | $19.79 | $39.46 | 49.8% |
| Addus HomeCare (ADUS) | $116.62 | $226.18 | 48.4% |
We'll examine a selection from our screener results.
Healthcare Services Group (HCSG)
Overview: Healthcare Services Group, Inc. offers management and operational services for housekeeping, laundry, facility maintenance, and dietary departments in healthcare facilities across the United States with a market cap of approximately $1.43 billion.
Operations: The company's revenue is primarily derived from its Dietary segment, generating $1.02 billion, and Environmental Services (EVS) segment, contributing $844.06 million.
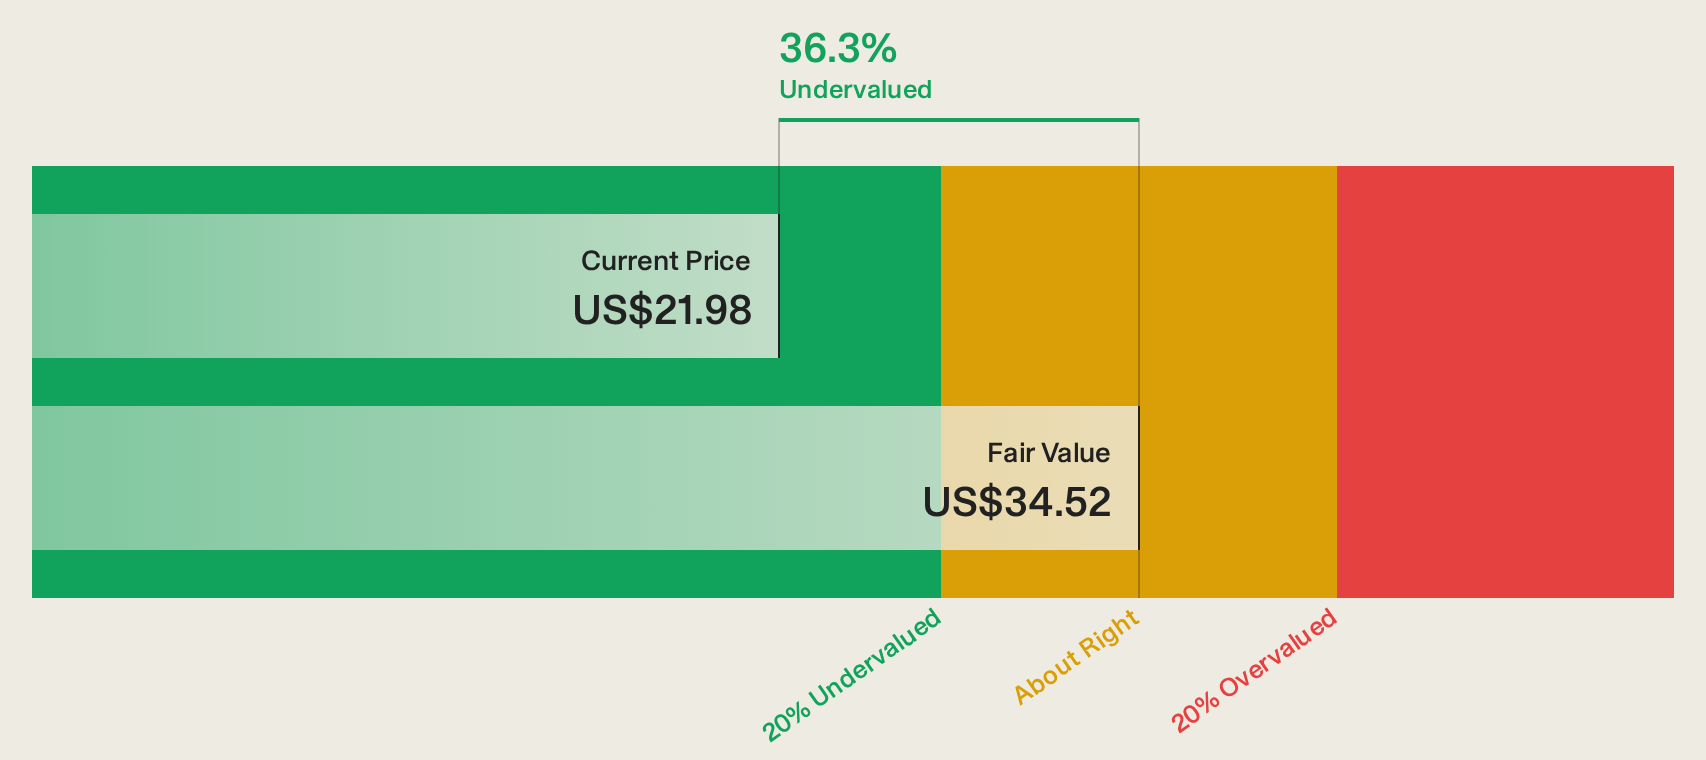
Estimated Discount To Fair Value: 39.1%
Healthcare Services Group is trading 39.1% below its estimated fair value, with a share price of US$21.02 compared to a future cash flow value of US$34.52. Despite earnings forecasted to decline by 13.4% annually over the next three years, recent financials show improved performance, with net income reaching US$22.7 million in Q2 2026 versus a loss last year. The company also completed significant share buybacks totaling US$35.64 million, enhancing shareholder value amidst slow revenue growth projections.
- According our earnings growth report, there's an indication that Healthcare Services Group might be ready to expand.
- Unlock comprehensive insights into our analysis of Healthcare Services Group stock in this financial health report.
Inspire Medical Systems (INSP)
Overview: Inspire Medical Systems, Inc. is a medical technology company that develops and commercializes minimally invasive solutions for obstructive sleep apnea, with a market cap of approximately $1.99 billion.
Operations: The company's revenue is primarily derived from its patient monitoring equipment segment, which generated $898.74 million.
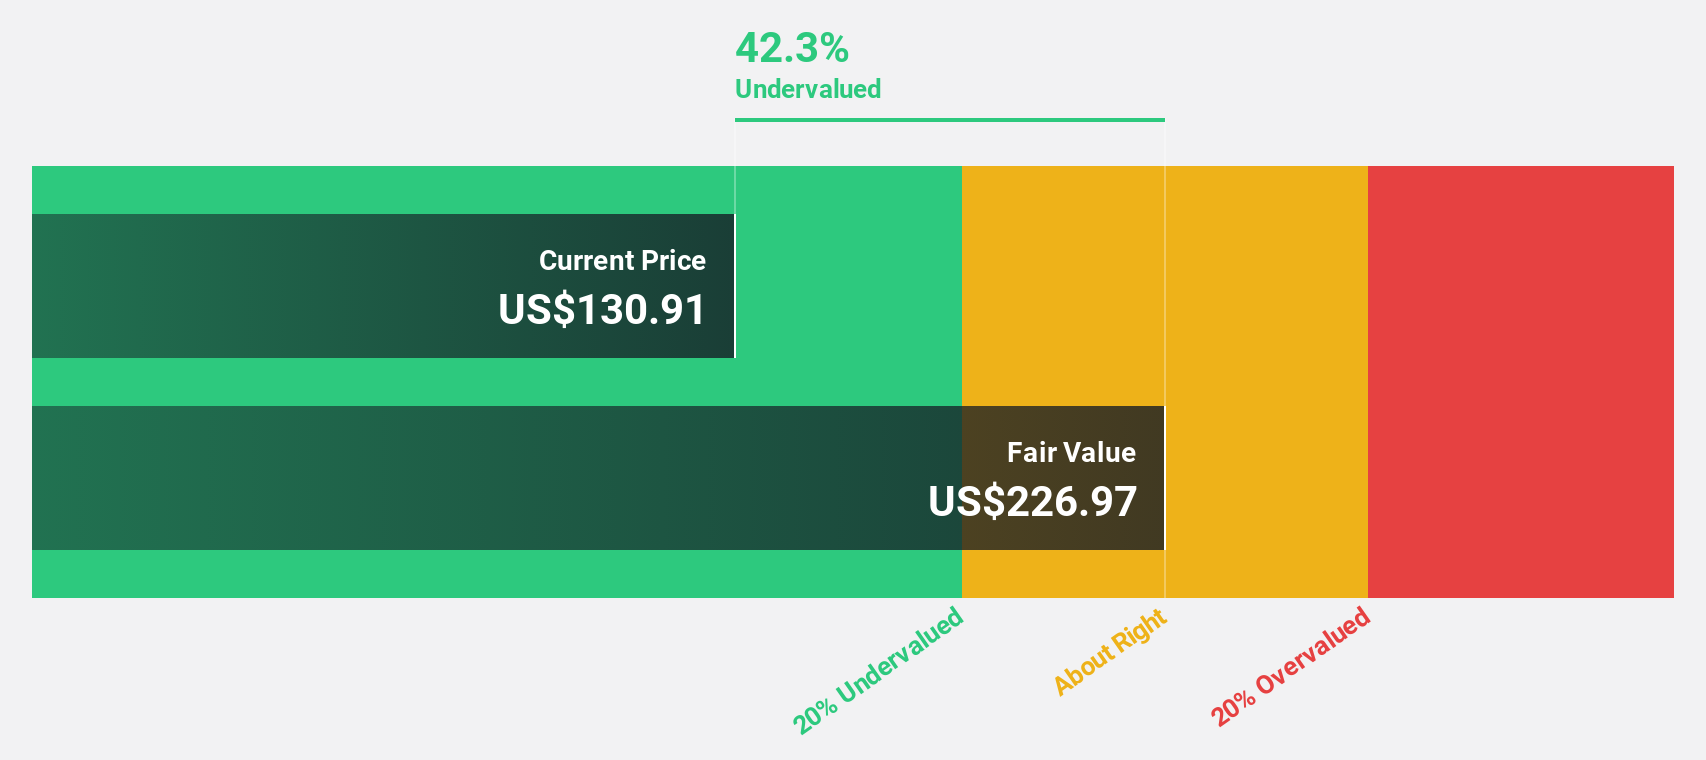
Estimated Discount To Fair Value: 20.3%
Inspire Medical Systems is trading 20.3% below its estimated fair value, with a current share price of US$68.07 against a future cash flow value of US$85.45. Despite earnings projected to decline by 5.9% annually over the next three years, the company reported improved financial performance in Q2 2026, achieving net income of US$0.314 million compared to a loss previously. Revenue growth remains modest at an expected 4.1% annually, below market averages.
- Insights from our recent growth report point to a promising forecast for Inspire Medical Systems' business outlook.
- Click here to discover the nuances of Inspire Medical Systems with our detailed financial health report.
Textron (TXT)
Overview: Textron Inc. operates globally in the aircraft, defense, industrial, and finance sectors with a market cap of $12.80 billion.
Operations: The company's revenue is derived from its Bell segment at $4.43 billion, Industrial segment at $3.22 billion, and Finance segment at $74 million.
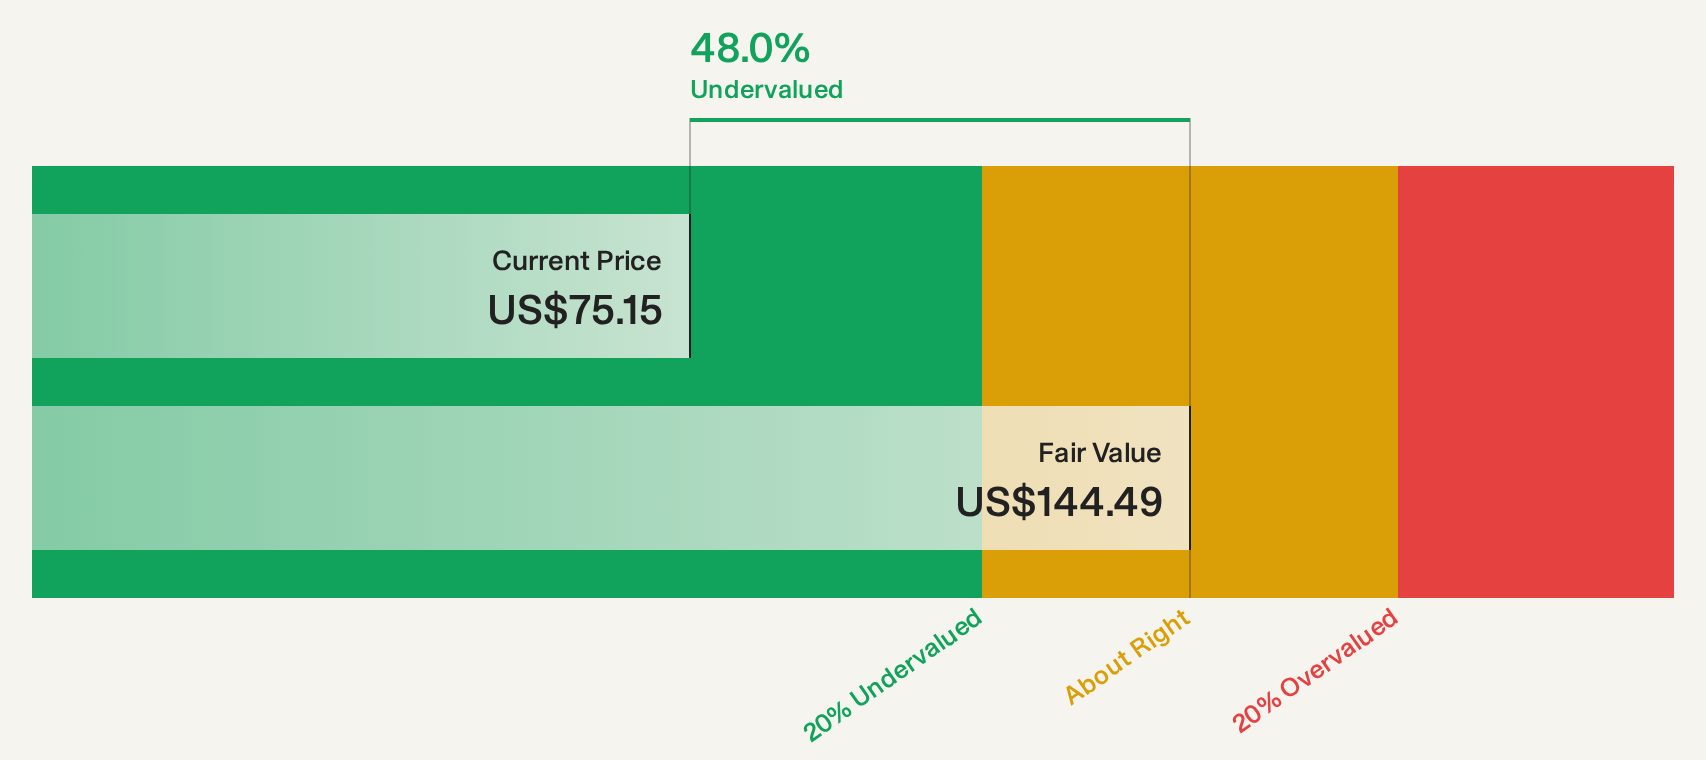
Estimated Discount To Fair Value: 48.6%
Textron is trading at US$73.8, significantly below its estimated future cash flow value of US$143.61, indicating it may be undervalued based on cash flows. Despite a modest earnings growth forecast of 7.13% annually, below the US market average, the stock is considered good value compared to peers and industry standards. Recent leadership changes in Textron Aviation could impact strategic direction but align with ongoing operational improvements and share buybacks totaling US$282.82 million this year.
- Our earnings growth report unveils the potential for significant increases in Textron's future results.
- Dive into the specifics of Textron here with our thorough financial health report.
Taking Advantage
- Access the full spectrum of 103 Undervalued US Stocks Based On Cash Flows by clicking on this link.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Streamline your investment strategy with Simply Wall St's app for free and benefit from extensive research on stocks across all corners of the world.
Interested In Other Possibilities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com