


Is DocuSign (DOCU) Fully Valued After Its Expanded Salesforce Partnership?
Salesforce partnership and AI integration reshape the DocuSign story
DocuSign (DOCU) is back in focus after expanding its more than 20-year partnership with Salesforce, bringing its Intelligent Agreement Management platform directly into Salesforce, Agentforce, and Slack workflows.
The move ties contract creation, approvals, and signatures to the same systems revenue teams already use. This development could matter for how investors think about DocuSign’s role in AI driven sales and contract automation.
Recent trading has picked up meaningfully, with DocuSign’s share price gaining 4.04% over the last day and 40.93% over the past 90 days. The 1-year total shareholder return of 10.78% contrasts with a much weaker 5-year total shareholder return that declined 72.27%, hinting at momentum rebuilding after a tough longer stretch as investors react to AI product updates and the expanded Salesforce tie up.
Scan how DocuSign’s AI contract push compares to other potential breakouts by reviewing the hand picked 39 profitable AI stocks that aren't just burning cash already turning software automation into earnings power.
DocuSign has climbed 40% in three months, powered by AI headlines and the Salesforce tie up. Do you lean into this strength now, or wait and hope for a cheaper shot later as valuation comes into focus?
Most Popular Narrative: 23.3% Overvalued
DocuSign last closed at $75.23 while the most followed narrative pegs fair value at $60.99, creating a gap that puts the recent AI driven rally under the microscope rather than treating it as a given.
On a market capitalisation basis, justifying roughly $11.0 billion at a 9% discount needs about $850 million of GAAP net income in 2031, which on 7% revenue growth implies a net margin near 19%.
The buyback lowers that materially, because the same earnings are spread across fewer shares. Once you run the inputs and I can solve the constant, I will pin the exact requirement. My provisional read is that at the current repurchase pace the requirement falls to roughly 15%, which is close to the base case, meaning DocuSign is priced near fair on these assumptions rather than obviously cheap or dear.
See why 7 investors see DocuSign as 23% overvalued.
According to rcb9, the narrative leans heavily on a few moving pieces. It highlights mid single digit constant currency growth, a meaningful contribution from Intelligent Agreement Management to keep overall expansion closer to 7% a year, and a path to a 15% GAAP net margin helped by share based compensation drifting lower as a share of revenue. It also assumes buybacks continue to reduce the share count meaningfully, so a larger slice of any future earnings accrues to each remaining share.
The same narrative flags clear breaking points that could undermine that fair value math. It points to IAM potentially missing the target of roughly 18% of ARR by January 2027, revenue growth dropping below the guided 8.25% to 8.75% band, or GAAP net margin failing to move past 11% in fiscal 2027. It also singles out any period where diluted share count rises as a red flag that issuance has outrun repurchases.
Those checkpoints give investors a concrete scorecard for the DocuSign story. Revenue around the $865 million to $869 million Q2 fiscal 2027 guide, IAM’s share of ARR, non GAAP operating margin holding above 30%, and progress on share count all become practical data points to compare against this framework as new results arrive.
Result: Fair Value of $60.99 (OVERVALUED)
Still, this storyline can crack if Intelligent Agreement Management loses momentum inside DocuSign, or if share based compensation continues to dilute shareholders faster than buybacks can offset.
Find out about the key risks to this DocuSign narrative.
Another View: SWS DCF model points to upside
The rcb9 narrative frames DocuSign as 23.3% overvalued at $75.23 against a $60.99 fair value. The SWS DCF model points the other way, with a future cash flow value of $158.56 that is well above the current share price. That kind of gap raises a practical question: Which story would you trust more, the cash flow model or the earnings based narrative?
To see how this cash flow lens is built and what would need to hold true for it to matter for your own process, Look into how the SWS DCF model arrives at its fair value.
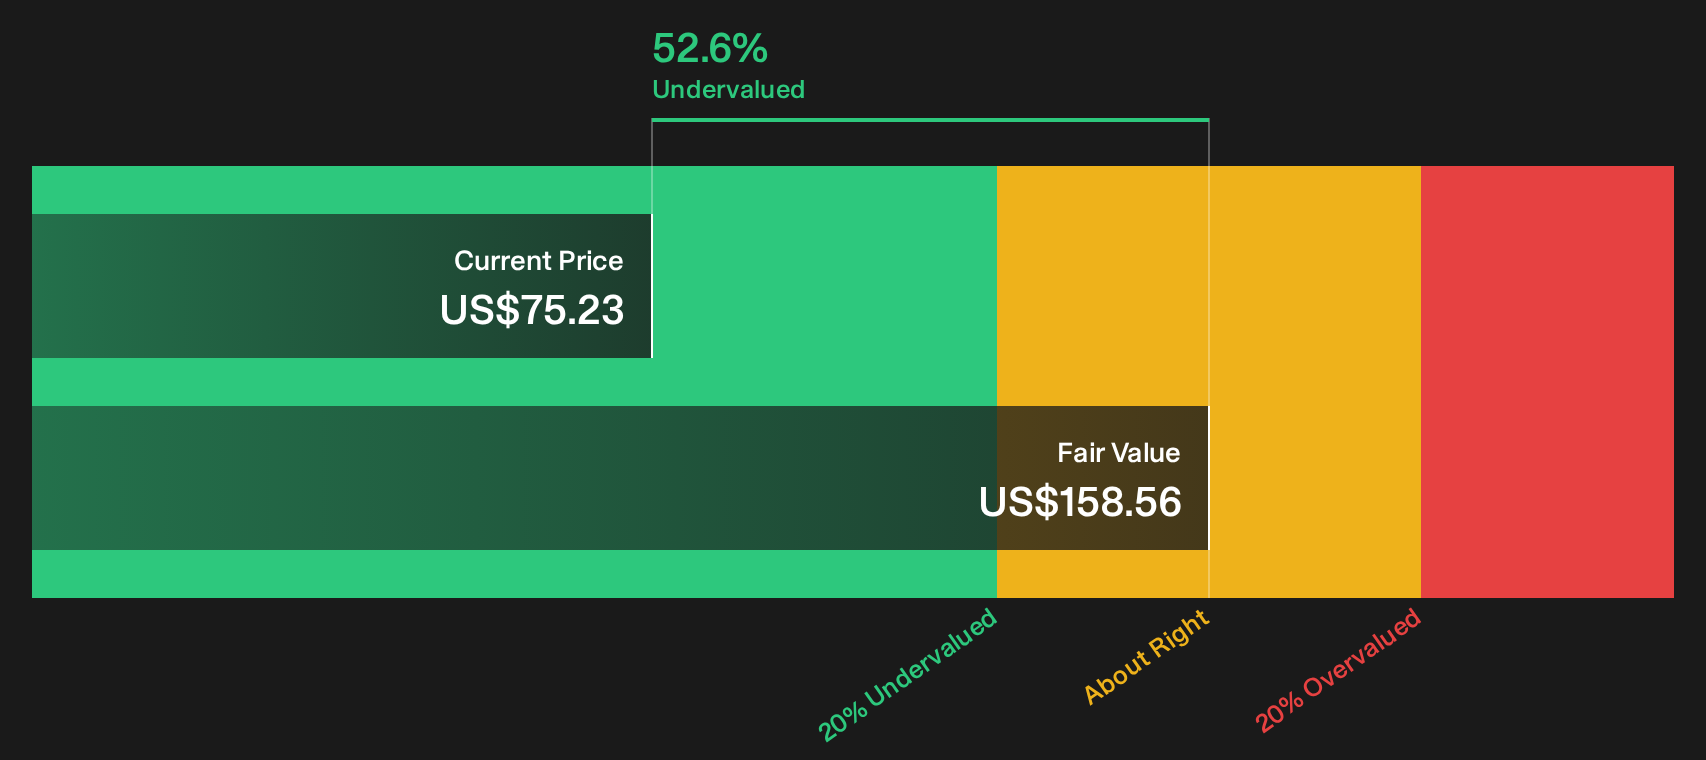
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DocuSign for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around DocuSign can be confusing. Move quickly, review the underlying data, and build your own conviction using the 3 key rewards and 1 important warning sign.
Looking for more DocuSign style investment ideas?
If DocuSign has your attention right now, do not stop at a single ticker. Use the time you have today to scan other opportunities that match your risk, return, and income goals before they move without you.
- Target long term value by reviewing a curated 32 high quality undervalued stocks where strong fundamentals and sensible prices line up.
- Strengthen portfolio resilience by checking the list of solid balance sheet and fundamentals (25 results) that can better handle tough conditions.
- Hunt for future leaders early by scanning the 20 high quality undiscovered gems before wider attention closes the valuation gap.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com