


Can Pacira BioSciences (PCRX) Justify Its Buyout Price On Earnings?
Pacira BioSciences has surged to a US$36.40 share price alongside an agreed all cash takeover by Viatris, which now puts a hard number on what the market is willing to pay. With Pacira stock up strongly over the past year, the live question is whether that deal price is fully backed by the company’s earnings.
- Pacira has delivered a 55.2% return over the past year, so anyone looking at the Viatris offer now has a lot of recent gains riding on how solid the earnings foundation really is.
- The US$36.50 per share cash bid and the ongoing shareholder fairness investigations put a spotlight on Pacira’s profit profile, because the outcome hinges on whether current and expected earnings can reasonably support that takeover valuation.
- Your read on Pacira BioSciences is one view; the desks covering it have another. See what analysts think Pacira BioSciences's shares could be worth.
For investors, the debate is whether Pacira’s current share price around the Viatris offer level is appropriately grounded in what the business is earning today and is expected to earn over time.
If you want to test this same earnings fairness question beyond Pacira BioSciences, you can run the rule over a wider set of solid balance sheet and fundamentals stocks screener (25 results).
Has Pacira BioSciences Run Too Far on Earnings?
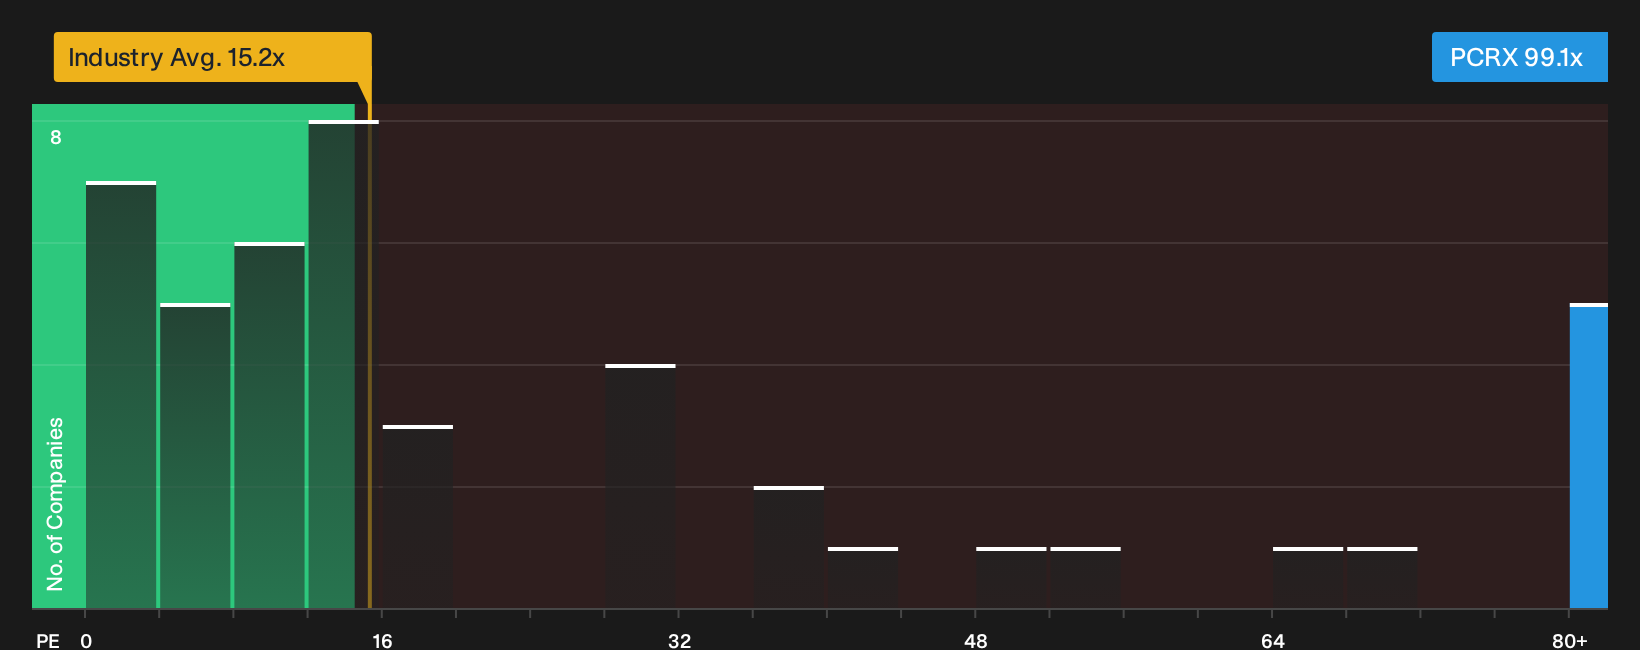
The P/E ratio is a useful yardstick here because Pacira BioSciences is being valued squarely on its earnings power around the Viatris bid. At the current offer level, the stock trades on a P/E of about 99.1x, which is far above the Pharmaceuticals industry average of roughly 15.2x and the peer group on about 11.8x. This gap tells you investors are being asked to pay a very full price for each dollar of Pacira’s profit.
The tailored fair P/E that factors in Pacira’s growth outlook, margins, size and risk profile sits far below the live multiple. On this framework the shares screen as overvalued rather than just slightly rich. Because the Viatris deal already anchors the price in an all cash offer, that premium P/E now reflects confidence that Pacira’s earnings and products justify such a lofty tag despite the ongoing shareholder fairness investigations questioning whether the US$36.50 proposal fully compensates existing holders. To see how large that modelled gap is and what it implies in dollar terms, you would need to look at the detailed multiple breakdowns. Explore the numbers behind Pacira BioSciences's P/E valuation.
The Pacira BioSciences Narrative: What Would Justify Today's Price?
Narratives for Pacira BioSciences pick up where the valuation puzzle leaves off and explain which combinations of future growth, profitability and earnings would need to align for the shares to be worth meaningfully more or less than today's price, all housed on Simply Wall St's Community page. Rather than relying on a single headline multiple or one model output, each Narrative lays out the earnings and margin assumptions behind its view of fair value so you can compare those inputs with Pacira BioSciences' actual results as they are reported.
Pacira BioSciences draws two very different readings from the community, with one group seeing more long term potential than the other gives credit for.
Bull case: roughly fairly valued
"The shift from a single listed EXPAREL patent to 21 patents, combined with a settlement that limits generic entry until 2039, now adds clearer visibility…"
Discover why this Narrative puts Pacira BioSciences at roughly fairly valued.
Bear case: 21% overvalued
"Pacira BioSciences remains heavily reliant on EXPAREL and on supportive reimbursement policies, and the scheduled expiry of NOPAIN Act reimbursement at the end of 2027 introduces the possibility…"
Explore why this Narrative puts Pacira BioSciences at 21% overvalued.
One more Pacira BioSciences clue before you make up your mind
Everything so far has focused on what Pacira BioSciences earns today, yet there is a separate lens in the form of professional projections that can either challenge or reinforce how you see this valuation. Explore where analysts expect Pacira BioSciences to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com