


What United Parks & Resorts Doubters Saw Before The Drop
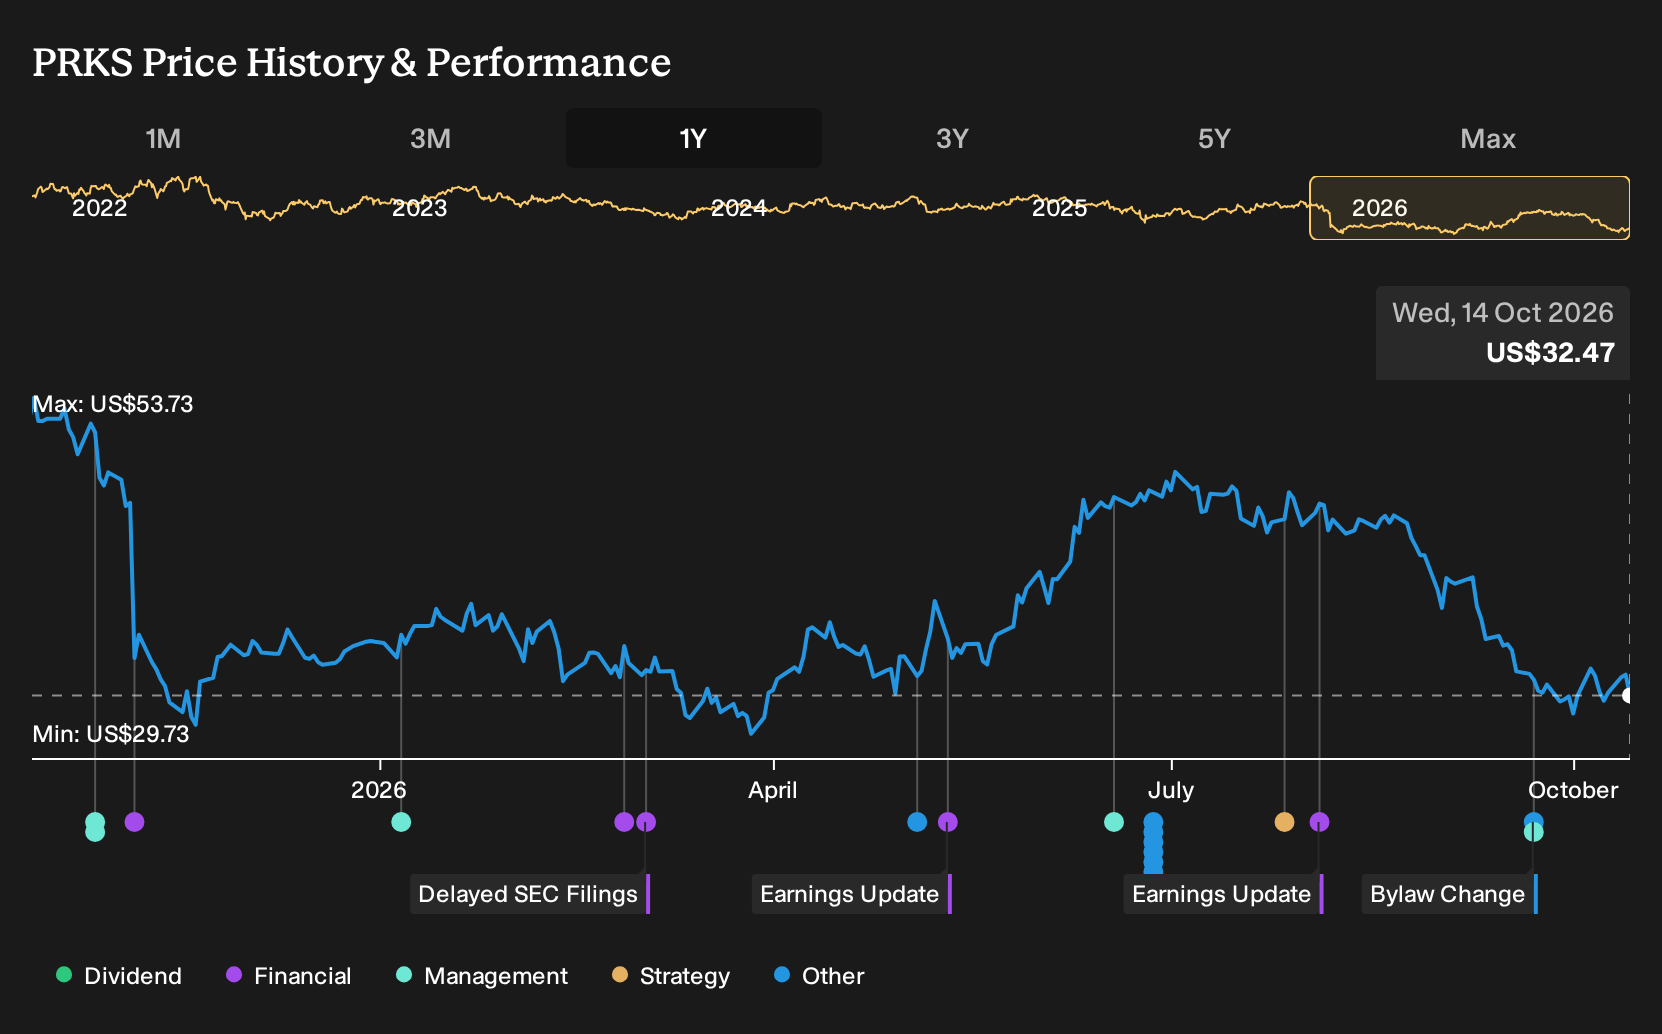
United Parks & Resorts has spent much of 2026 in the headlines for weaker Q1 and Q2 results, falling attendance and a series of leadership reshuffles at key parks like Busch Gardens Tampa Bay and the Orlando properties. Holding United Parks & Resorts over the past year would have meant a 37.7% loss, including dividends. If you had made that call back in October 2025, how would you judge it today in light of softer visitors, ongoing buybacks and mixed analyst conviction about traffic trends?
The easy part of this move is behind United Parks & Resorts. Zero in on 32 high quality undervalued stocks for companies trading below our estimates.
The Argument United Parks & Resorts Investors Faced
The shares cost US$53.73 at the start of the period, and you had to decide which story about United Parks & Resorts felt more convincing. One camp thought the market was slightly cautious. Another group saw meaningful downside risk.
The optimistic narrative pointed to a fair value of US$56.57, a price implied by expectations for resilient Orlando demand and underused real estate, such as roughly 400 acres near the parks that could support extra partnerships and projects.
The cautious view anchored on a fair value of US$44, based on concerns that demographic shifts and climate volatility would steadily erode attendance and put structural pressure on admissions and in-park spending.
What The Results Changed For United Parks & Resorts
United Parks & Resorts then printed Q2 2026 revenue of US$483.32 million, slightly below Q2 2025, while net income slid from US$80.11 million to US$63.27 million and net margin moved from 16.3% to 13.1%. That pattern challenged the optimistic story about stronger profitability, even as ongoing buybacks and IP driven events gave the cautious case some pushback. Overall, the evidence cut both ways.
The key assumption investors needed to test was profit quality. For any other entertainment operator, it is worth watching whether margin trends confirm the upbeat narrative even when headline demand looks soft.
What United Parks & Resorts Buyers Are Really Paying For Now
United Parks & Resorts now trades at US$32.47 after a 37.7% loss over the past year. The selected Narrative’s Fair Value sits above the current price, framed around what prepaid demand, in park spending and real estate could mean for earnings power.
The crux is simple. For the fall to look like an opportunity rather than a warning, a buyer today would need confidence that prepaid visits and higher spending per guest offset choppy attendance and cost pressure.
"Forward bookings and deferred revenue that reached $211.9 million by June 30, 2026, together with earlier commentary on strong group and pass sales, indicate that United Parks & Resorts continues to build a base of prepaid visits and ancillary products that can support future revenue recognition and earnings visibility."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Where Could You Get There Earlier?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 35% below our estimate - targets long life gold reserves while managing higher extraction costs and political risk.
- Company 2 - 47% below our estimate - pushes users from physical betting outlets toward an in house online gaming and sportsbook platform.
- Company 3 - 49% below our estimate - wins multiyear e infrastructure projects building sites for data centers and critical facilities.
Three companies from the same screener. Open the full list of 25 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com