


Big Creek Tunnel Contract Might Change The Case For Investing In Granite Construction (GVA)
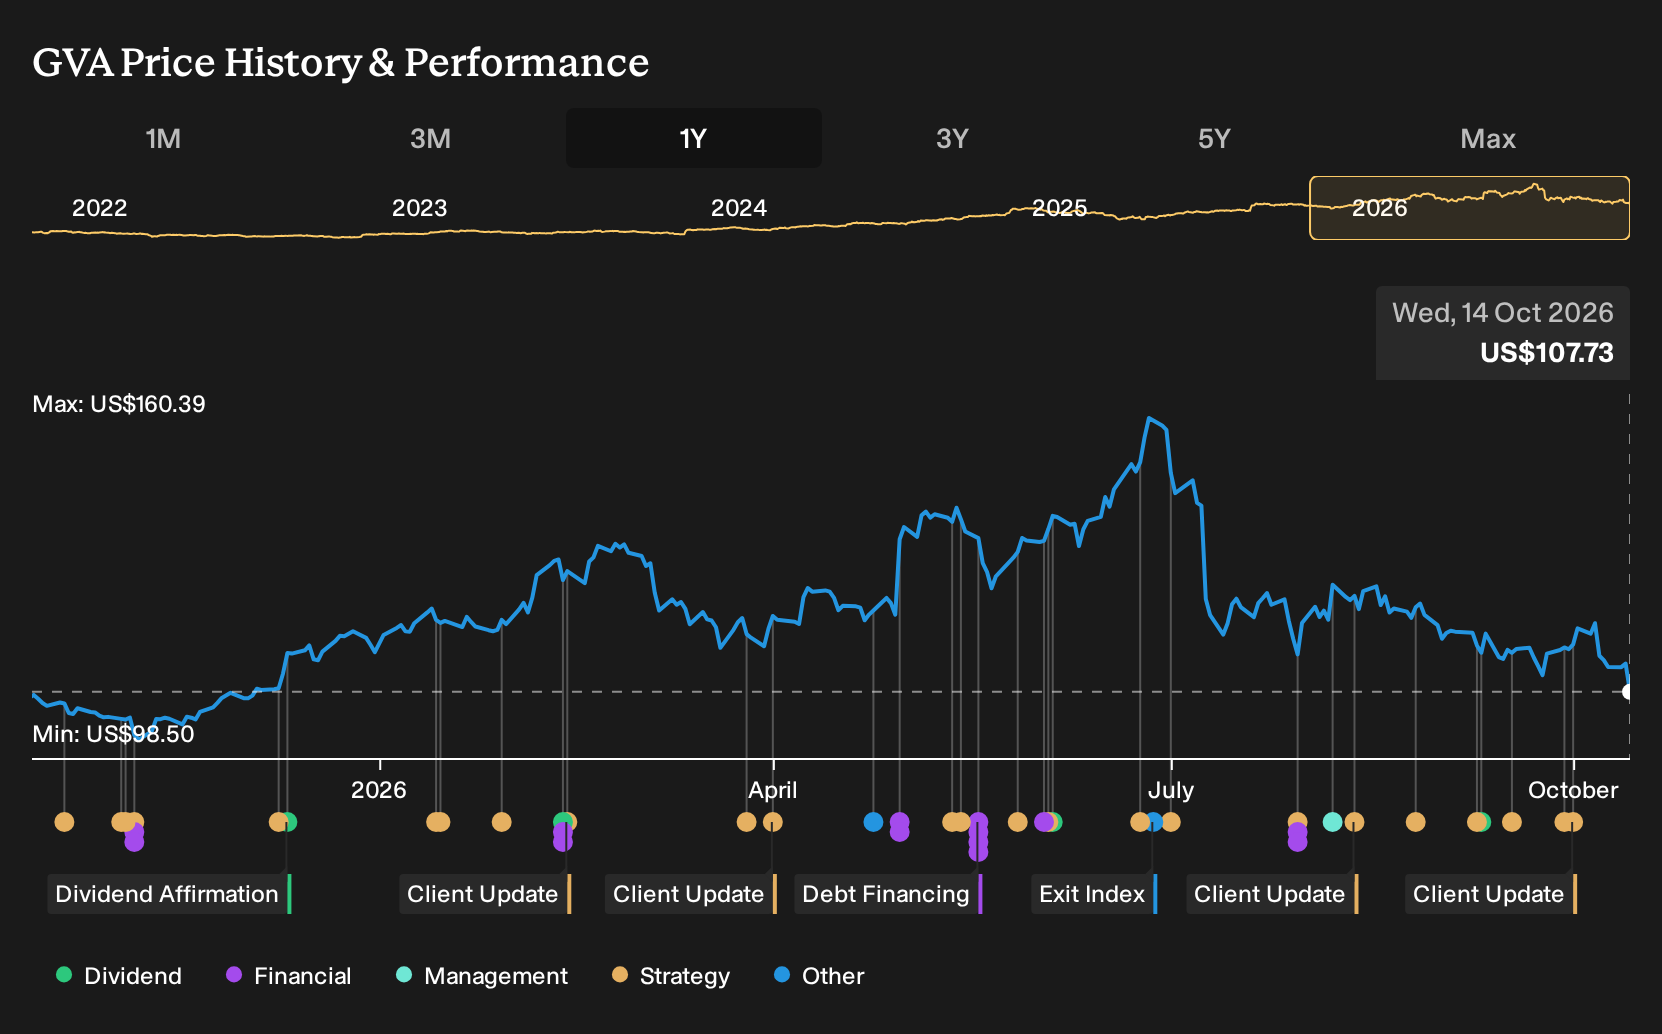
- Granite Construction reported that its Granite Super joint venture won a US$324.8 million Big Creek Tunnel contract in Cleveland, adding a long duration wastewater project to third quarter committed and awarded work.
- The tunnel is part of NEORSD's US$3 billion Project Clean Lake program and is expected to eliminate 550 million gallons of combined sewer releases each year, reinforcing Granite Construction's exposure to long term public infrastructure work.
- This development provides additional context for Granite Construction's investment narrative in light of the large Cleveland tunnel award and multiyear workload.
Scan other construction and infrastructure players positioned for long duration public works contracts using the curated 43 power grid technology and infrastructure stocks, which extends beyond Granite Construction's latest wastewater tunnel win.
Granite Construction Investment Narrative Recap
To own Granite Construction, you need to believe in a long runway of U.S. public works, consistent execution on complex projects and a path from loss making today to the profitability analysts are forecasting. The Big Creek Tunnel award adds visibility to future work but does not change the near term focus on improving cash gross margins and stabilising the Materials segment.
The key short term catalyst remains converting a record construction portfolio into higher quality earnings while managing severe weather and cost pressures that have already hurt margins. The largest risk is softer real public construction spending once current federal programs mature, which could make it harder for Granite Construction to sustain revenue and backlog conversion.
The Big Creek Tunnel win is the announcement that most clearly ties into that thesis. It supports Granite Construction’s emphasis on best value and collaborative work and extends exposure to long duration, federally linked infrastructure. For you, the practical takeaway is a clearer line of sight on multi year activity, which can help the business work toward the profitability inflection analysts are modelling.
At the same time, this award does not erase the known pressure points. Granite Construction still carries a high level of debt, remains unprofitable, and faces Materials margin volatility if quarry and plant costs stay elevated. The Cleveland project highlights execution opportunity, but the real catalyst will be whether management can translate this kind of backlog into steadier margins and stronger operating cash flow over the next few years.
Granite Construction's current loss of US$164.9 million is set against analyst forecasts for earnings of US$687.3 million by 2029. That shift implies an earnings improvement of about US$852 million, alongside expected revenue of US$6.5 billion and an assumed 9.6% yearly increase in sales over the next three years.
Uncover how Granite Construction's fair value indicates a 59% potential upside to its current price, which could materialize faster than many investors expect.
Exploring Other Perspectives
You are not alone if you read the bullish Granite Construction narrative and focus on the bigger federal and data center exposure as the key upside catalyst. The most optimistic analysts were already modelling US$6.5b of revenue and US$594.4m of earnings by 2029 before this Cleveland tunnel award, so expectations were high. Views may shift as this contract filters into fresh models. This is why it helps to compare several outlooks, not just one headline target.
Explore 3 other Granite Construction fair value estimates, including one that suggests as much as 86% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Consider forming your own view based on thorough research.
- A great starting point for your Granite Construction research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Granite Construction. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Granite Construction's overall financial health at a glance.
Looking For More Investment Ideas Beyond Granite Construction?
If Granite Construction has you thinking about where to deploy fresh capital next, it can help to compare this story with other opportunities that share similar qualities or offer a different balance of risk and reward. The Simply Wall St Screener can surface a mix of resilient, income focused and underappreciated companies that match your own criteria rather than someone else’s model portfolio.
- For investors who want quality and value in the same place, start with a curated set of companies that screen well on both fundamentals and pricing by reviewing 32 high quality undervalued stocks.
- If capital preservation sits high on your priority list, consider tilting toward businesses that our models assess as more resilient by scanning the 32 resilient stocks with low risk scores.
- When you are hunting for underfollowed opportunities with solid underlying metrics, broaden your watchlist using the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com