


Aya Gold And Silver (TSX:AYA) Stock Looks Stretched On Its 374% Run
Aya Gold & Silver has delivered a powerful run over the past few years, and the question now is whether the current share price can be explained by the earnings that support it. With such a strong track record on the chart, investors are increasingly focused on what the income statement is saying about the valuation.
- Over the past 3 years the stock has returned about 3.7x, which places significant emphasis on whether present earnings can justify that level of market value.
- The business is closely linked to the profitability of its producing assets, so future changes in net income may depend on how efficiently it converts each ounce of output into cash.
- There is a second opinion on Aya Gold & Silver worth weighing. See what analysts think Aya Gold & Silver's shares could be worth.
The issue now is whether Aya Gold & Silver's current market price is adequately supported by the earnings it is generating today.
If you want more context around Aya Gold & Silver's recent run and current earnings lens, compare it with other producers using our screener of 35 elite gold producer stocks
Does Aya Gold & Silver Look Pricey on Earnings?
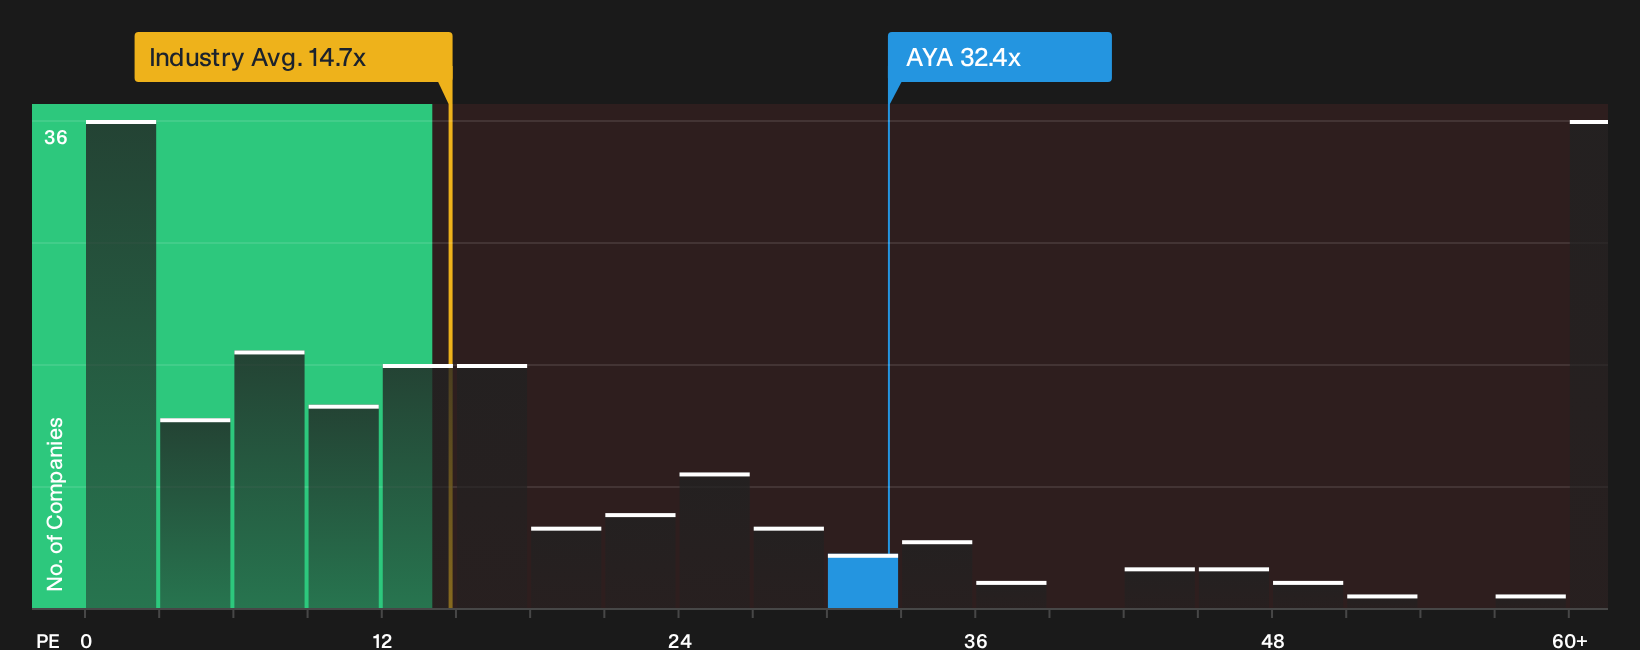
P/E is usually a straightforward way to compare Aya Gold & Silver with other producers because it ties the share price directly to reported earnings. On this yardstick, the stock trades on roughly 32.4x earnings, which is more than double the Metals and Mining industry average of about 14.7x. Compared with a peer group around 37.5x, Aya Gold & Silver changes hands at a lower multiple, so the shares do not sit at the very top of the sector range.
The fair multiple that factors in Aya Gold & Silver's own growth profile, profitability and risk sits below the current 32.4x P/E. This indicates that the stock screens as overvalued on this framework. That gap suggests you need to be comfortable paying a premium for its current earnings stream and confident about the business drivers supporting that premium before relying on P/E alone to frame an entry point. Explore the numbers behind Aya Gold & Silver's P/E valuation.
The Aya Gold & Silver Narrative: What Would Justify Today's Price?
Narratives for Aya Gold & Silver pick up where the P/E discussion stops by spelling out which future paths for growth, margins and earnings would need to play out for today's valuation to move meaningfully higher or lower. Instead of leaving you with a single ratio or model output, they map the underlying assumptions that figure rests on so you can watch how the business reality lines up over time on Simply Wall St's Community page.
Community views on Aya Gold & Silver are split between those who see meaningful upside and those who think the market already prices in a lot of good news.
Bull case: 28% undervalued
"Aya's exploration success at both Zgounder and Boumadine, combined with ongoing property acquisition and aggressive regional drilling programs, is poised to drive…"
Discover why this Narrative puts Aya Gold & Silver at 28% undervalued.
Bear case: 6% overvalued
"Most investors avoid Morocco (Tier-2 jurisdiction), creating a valuation gap…"
Explore why this Narrative puts Aya Gold & Silver at 6% overvalued.
Aya Gold & Silver: One unresolved issue that could matter more than the P/E
Price multiples only tell part of the story, because Simply Wall St's broader checks on Aya Gold & Silver have surfaced specific areas of concern that investors may want to inspect closely before getting comfortable. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com