


Danaos (DAC) Stock Still Looks Cheap With Earnings In Focus
Danaos has delivered a powerful run in recent years, and the question now is whether a price near US$161.96 is still grounded in what the business earns. After a move like that, you need to ask if the earnings story is strong enough to carry the current valuation.
- Over the past 3 years, the share price has gained about 184.2%, which puts a lot of weight on whether current and future earnings can justify that climb.
- The company’s ability to turn its container shipping operations into consistent profits, and to manage capital spending on vessels, can shape how much investors are willing to pay for each dollar of earnings.
- There is a second opinion on Danaos worth weighing. See what analysts think Danaos's shares could be worth.
The stock’s next move may depend on whether Danaos’s current earnings are strong and reliable enough to support today’s share price.
If you want more ideas that put earnings front and center, a focused stock screen is a useful second starting point, including the 32 high quality undervalued stocks.
Is Danaos a Bargain on Earnings?
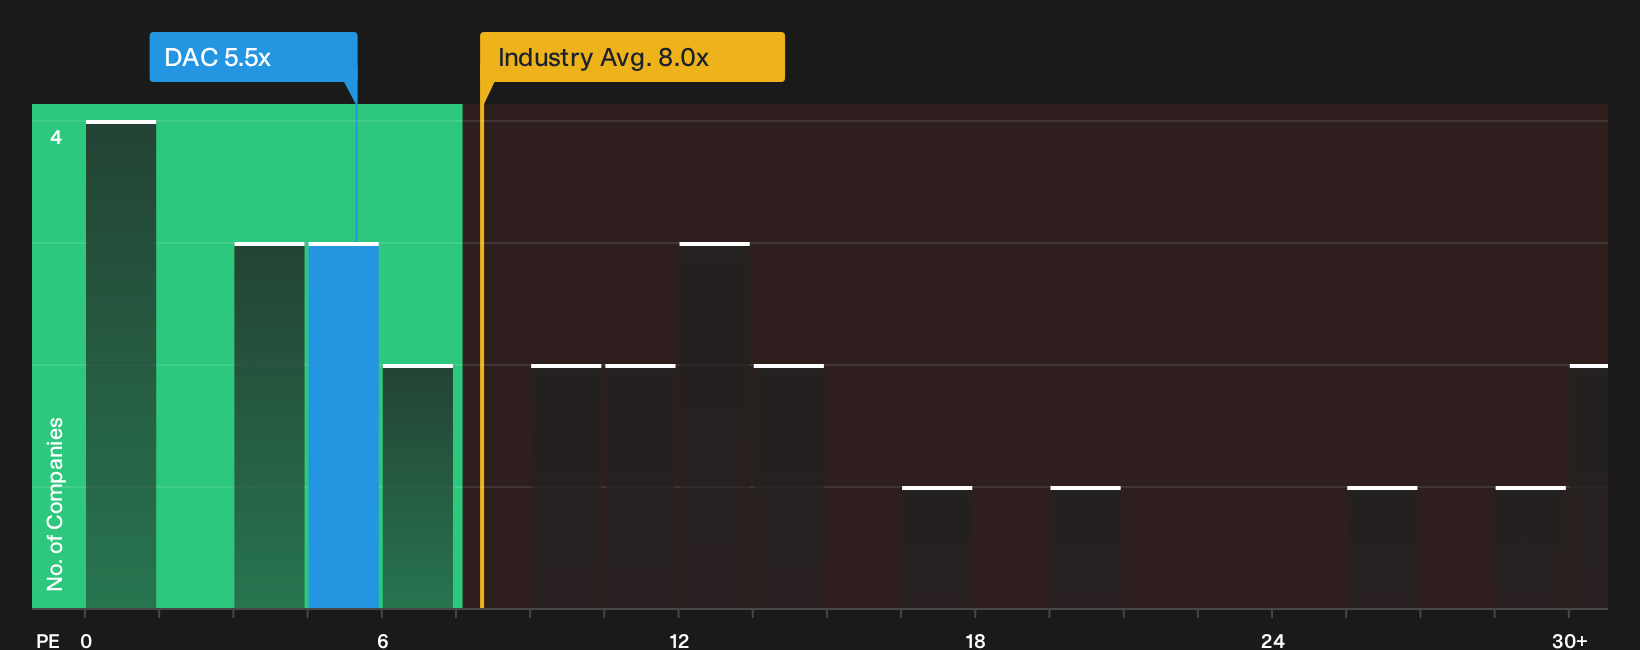
The P/E ratio suits Danaos because earnings power is central to how investors judge a shipping owner with a large vessel fleet. At a current P/E of 5.5x, the stock trades below the Shipping sector average of about 8.0x. That gap suggests the market is attaching a lower earnings multiple to Danaos than to the typical listed operator.
Against a broader peer set, where comparable stocks trade around 11.9x earnings, Danaos also comes through on the cheaper side. The fair multiple implied by the valuation model, which blends the firm’s growth profile, profitability, size and risk, sits above the current 5.5x. As a result, the shares screen as undervalued on this framework. Anyone weighing Danaos at today’s price still needs to judge how durable current profits are across future shipping cycles, since that ultimately determines whether a discounted P/E multiple is justified or an opportunity. Explore the numbers behind Danaos's P/E valuation.
The Danaos Narrative: What Would Justify Today's Price?
Narratives on Danaos pick up where the P/E puzzle leaves off by spelling out which paths for revenue growth, profitability and earnings would need to play out for the stock to look materially cheaper or more expensive than it does today. They sit on Simply Wall St's Community page. Each one turns fair value into a clear, testable view on how Danaos' business might evolve over time, so you can track how that thesis holds up.
Community views on Danaos are split between investors who see its contracted backlog and balance sheet as a cushion and others who think those same contracts cap upside.
Bull case: roughly fairly valued
"The record contracted revenue backlog of about US$4.6b, with charter coverage near full for 2026 and high levels through 2029…"
Discover why this Narrative puts Danaos at roughly fairly valued.
Bear case: roughly fairly valued
"Although the US$4.3 billion contracted revenue backlog with an average 4.3-year charter duration offers visibility, high contract coverage of 100% for 2026 and 87% for 2027 limits Danaos' ability to reprice capacity quickly…"
Explore why this Narrative puts Danaos at roughly fairly valued.
One more angle on Danaos that could change the story
Price tags and earnings multiples only go so far if you do not know who is steering Danaos or how their pay packets line up with your interests. See who runs Danaos and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com