


Should Investment Push Require Action From M&S Investors?
- Marks and Spencer Group is pushing its turnaround by committing high capital spending to store rotation, logistics and technology aimed at improving efficiency and returns in Food and in Fashion, Home & Beauty.
- The key angle is execution risk, since heavy spending and cost out targets only translate into value if projects like automated distribution hubs and digital platforms deliver the expected savings and cash generation.
- Next, the focus turns to how this renewed push on logistics and technology could reshape Marks and Spencer Group's broader investment narrative.
Marks and Spencer Group Investment Narrative Recap
To own Marks and Spencer Group, you need to believe that heavy investment in store rotation, logistics, and technology will turn into cleaner execution in Food and better profitability in Fashion, Home & Beauty. The recent push does not change the near term story much. The key short term catalyst is still visible proof that new distribution hubs and larger food halls run smoothly through peak trading.
The biggest near term risk sits in execution and cost control. Planned capex of £650m to £750m in FY 2026/27, on top of already elevated spend, could squeeze cash generation if cyber issues, stock flow problems, or project delays persist while UK consumers stay careful on discretionary spend.
The most relevant recent narrative is the focus on Marks and Spencer Group using higher capital spending to support free cash flow over time. Management is leaning on store rotation, logistics projects at Daventry, Avonmouth, Castle Donington, Bradford and Lichfield, and digital tools like AI driven planning and the Sparks relaunch to lower cost to serve and tighten stock management.
For you as a shareholder, the practical question is whether these projects move the dial on margins and cash in the next few years without creating new operational fragility. Execution missteps could magnify existing risks in International, where sales have already declined 7.2% year on year, and in Clothing, Home & Beauty, where weaker online profitability and higher unit costs remain a drag as more demand shifts to digital channels.
Marks and Spencer Group's narrative projects £21.0b revenue and £762.8m earnings by 2029. This assumes 6.7% yearly revenue growth and an earnings increase of about £503m from £259.4m today.
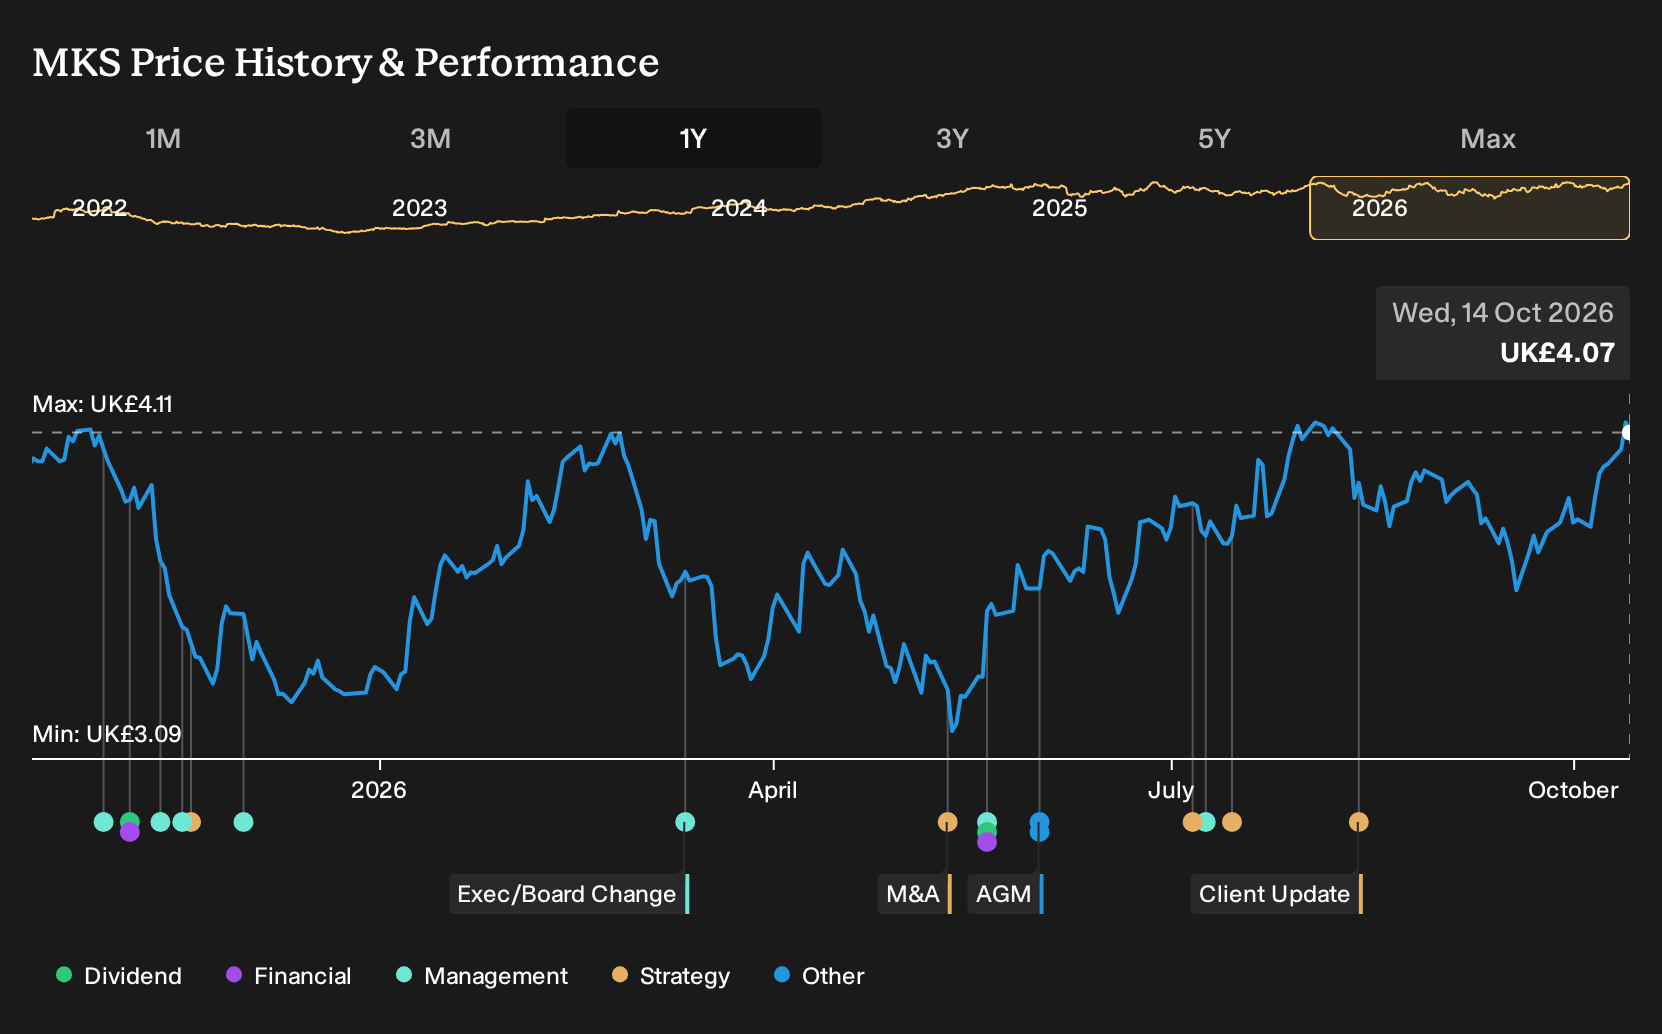
Discover why Marks and Spencer Group's fair value indicates a 9% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster at a minimum of £4.45 but extend to about £8.01, so some private investors see Marks and Spencer Group trading at roughly half their projected worth. You also face a tougher UK retail backdrop, with weaker discretionary demand and higher online participation adding pressure. Use that spread of opinions to test your own view and explore alternative angles before committing fresh capital.
Explore 3 other Marks and Spencer Group fair value estimates, including one that suggests it could be worth just £4.45.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Marks and Spencer Group research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Marks and Spencer Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marks and Spencer Group's overall financial health at a glance.
Looking for more investment ideas beyond Marks and Spencer Group?
Once you have a view on Marks and Spencer Group, it can help to compare it with other businesses that match your preferred style of investing, whether you care more about value, resilience, or future income streams.
- If you are hunting for potential bargains with solid fundamentals, scan a curated set of 8 high quality undervalued stocks that may line up with your return and risk preferences.
- For readers who want balance sheet strength to sit at the center of their process, shortlist companies using a list of solid balance sheet and fundamentals (9 results) to see which ones look built to handle tougher conditions.
- If you prefer under followed stories that still have robust numbers behind them, filter the market using a focused 5 high quality undiscovered gems and see which lesser known stocks deserve a spot on your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com