


How Q3 Shipment Decline At Stellantis (BIT:STLAM) Has Changed Its Investment Story
- Stellantis reported estimated Q3 2026 consolidated shipments of 1.3 million vehicles, a 1% year-on-year decline, as weaker North American volumes offset higher electric vehicle driven deliveries in Europe.
- At the Paris Motor Show, Stellantis used six brand specific concept cars and new BEV platforms to show how its multi brand portfolio could pivot further toward electrified models and software heavy cockpits.
- The focus now shifts to how Stellantis' shipment softness, particularly in North America, reshapes the broader investment narrative around its electrification push.
Stellantis Investment Narrative Recap
For Stellantis, the core belief is that a large, global automaker can reshape its mix toward electric and software heavy vehicles while fixing weak spots in North America and key profit pools. The recent 1% shipment decline and sharp 12% drop in North America keep that repair job front and center, even as European BEV demand supports Enlarged Europe volumes.
The most important short term swing factor is whether Stellantis can steady North American output and pricing while scaling new EV platforms without further margin strain. The biggest risk is that tariff costs, BEV profitability pressure and competitive intensity in mass market segments keep earnings quality unstable. The latest news is directionally important but not a clear turning point yet.
The Paris Motor Show concepts and Stellantis’ FaSTLAne 2030 themed reveal matter because they link directly to the electrification and software story investors are already watching. Six brand specific concepts and new BEV platforms show how future Alfa Romeo, Peugeot, Citroën and other badges could migrate toward electric architectures, software rich interiors and more differentiated designs.
This concept wave connects to catalysts around new BEV launches, platform standardisation and potential scale benefits in Europe and beyond. It also intersects with risks. Management still needs to prove it can bring these ideas into production on time and at acceptable margins while dealing with Chinese competition, weaker North American shipments and restructuring costs elsewhere in the group.
Stellantis' current analyst narrative anchors on revenues reaching €175.0b and earnings of €4.8b by 2029, based on an assumed 2.8% yearly revenue growth rate. That path implies an earnings swing of €24.3b, from a loss of €19.5b today to the forecast profit level, a very large change in absolute terms.
Discover why Stellantis' fair value points to a 46% potential upside from its current price that could narrow quickly.
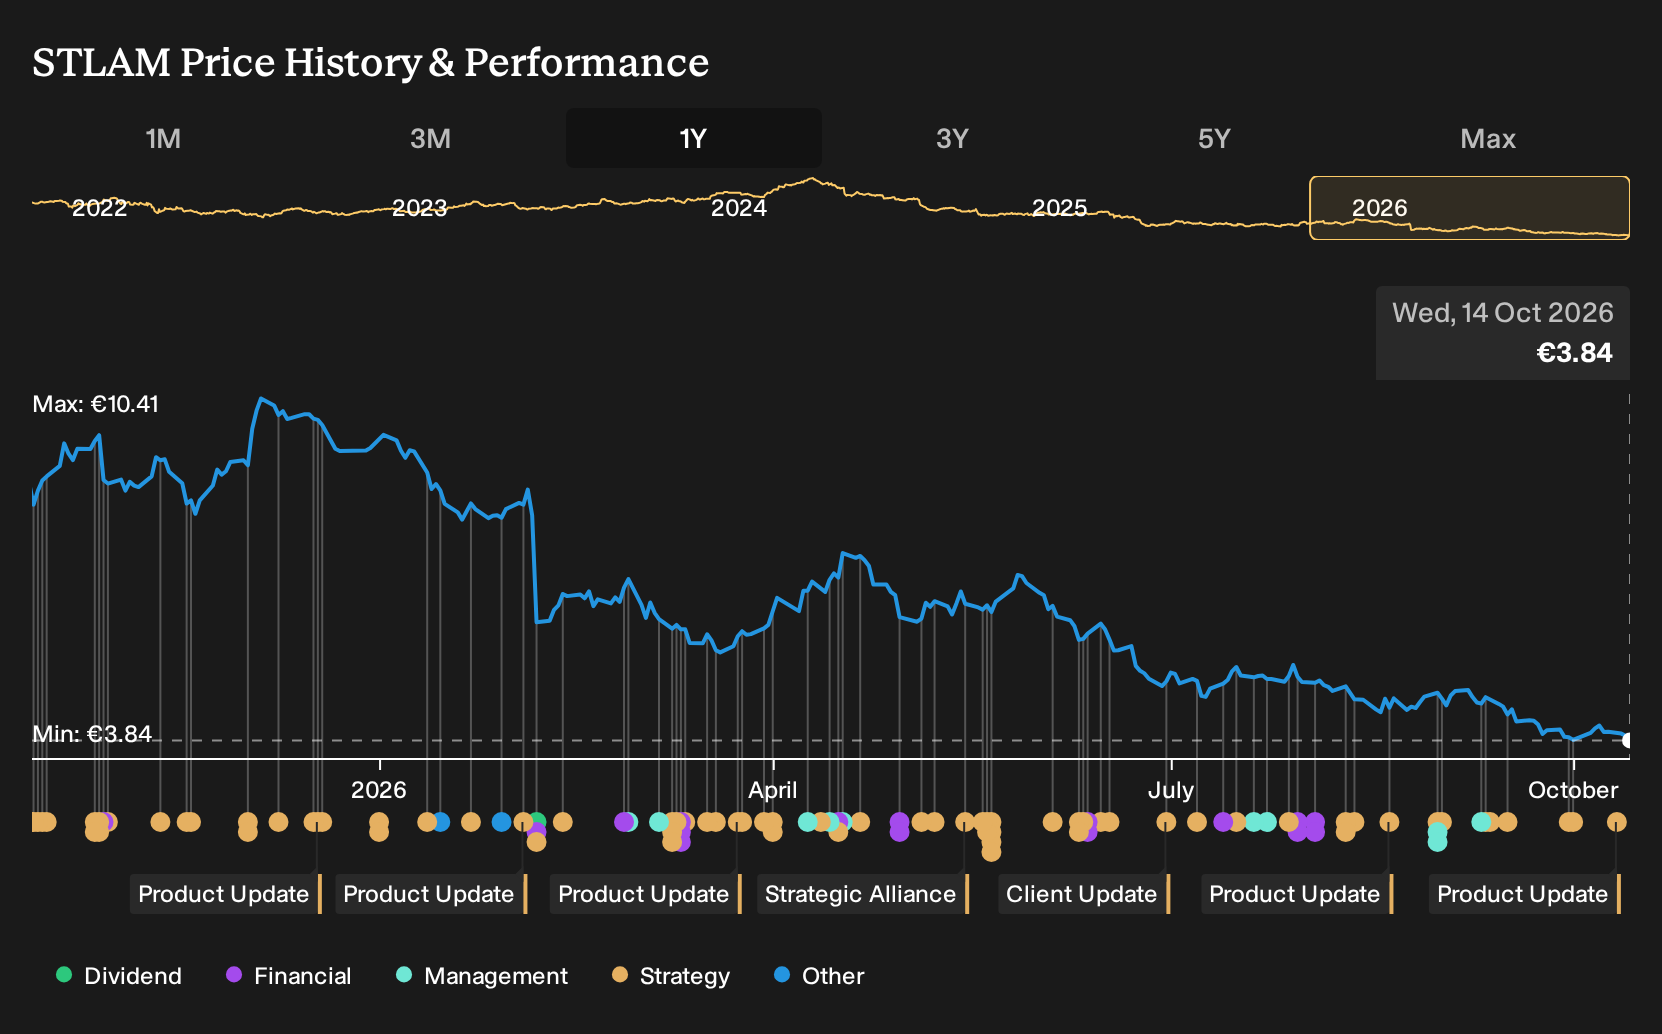
Exploring Other Perspectives
Some of the most optimistic analysts focus on Stellantis’ Value Creation Program as the key swing factor. Before this news, they were pencilling in revenue of about €190.2b and earnings near €11.3b by 2029, far above consensus. You can treat this as one possible storyline that may shift as the Paris show concepts and shipment trends are absorbed.
Explore 10 other Stellantis fair value estimates, including one that suggests an upside potential of up to 332% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Stellantis research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Stellantis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stellantis' overall financial health at a glance.
Looking for more investment ideas beyond Stellantis?
If the Stellantis story has sharpened your thinking about risk, reward and balance sheet strength, use that same lens across the wider market with the Simply Wall St Screener.
- For investors who want income with staying power, scan a curated set of potential yield opportunities through 220 dividend fortresses.
- If capital preservation ranks high on your checklist, narrow your shortlist to sturdier businesses with 222 resilient stocks with low risk scores.
- When you are hunting for underappreciated opportunities with solid fundamentals, start with our hand picked 614 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com