


Does Ahlo 2 Launch Change The Bull Case For Bell (TSX:BCE)?
- Bell recently launched the ahlo 2 smartphone in Canada with a 6.9 inch eye comfort display, 50 MP camera, Android 16, a 5,200 mAh battery and a retail price of $335, with optional $10 per month SmartPay financing and a $39.99 accessories bundle.
- This in house handset gives BCE another way to keep customers inside the Bell ecosystem through bundled devices, financing and accessories that speak directly to value conscious demand.
- We will now look at how BCE's investment narrative could be influenced by the value focused ahlo 2 smartphone launch.
Scan how BCE is leaning into value focused hardware, then widen your lens with a curated list of 7 high quality undervalued stocks that pair everyday pricing with stronger fundamentals.
BCE Investment Narrative Recap
To own BCE, you need to believe the heavy spend on fibre, AI infrastructure and enterprise services eventually steadies earnings and supports the balance sheet, even with modest top line growth assumptions. The near term story is still about absorbing higher capex and an earlier dividend reset while keeping customer metrics and churn under control.
Right now the key swing factor is whether that capital shift translates into the contracted cash flows and mix change analysts expect, against a backdrop where earnings are forecast to decline and wireless ARPU is already under pressure. The ahlo 2 launch looks immaterial to those bigger moving pieces and does not change the main risk, which is execution on capex and free cash flow.
The most relevant dated item for investors is BCE’s upcoming Q3 2026 results call on November 5. That is where management can tie products like the ahlo 2 back to wireless ARPU trends, device financing economics and any impact on churn, and set expectations on whether value oriented hardware supports overall customer lifetime value.
For readers, the useful angle is how this update fits beside the larger catalysts. The call should give more colour on Bell AI Fabric, Ziply Fiber and AI powered enterprise solutions, which are central to the long term thesis and to offsetting dividend, debt and capex concerns. Any detail on early traction, contracted revenue and capex timing will matter far more to BCE’s investment case than a single device launch, even if ahlo 2 helps reinforce the broader value focused positioning with consumers.
BCE's current analyst narrative points to revenue of CA$25.6b and earnings of CA$3.0b by 2029, aligned with forecast annual top line growth of 1.1% and an earnings decrease of CA$3.3b from CA$6.3b today.
Uncover why BCE's fair value indicates a 33% potential upside to its current price before this discount window closes.
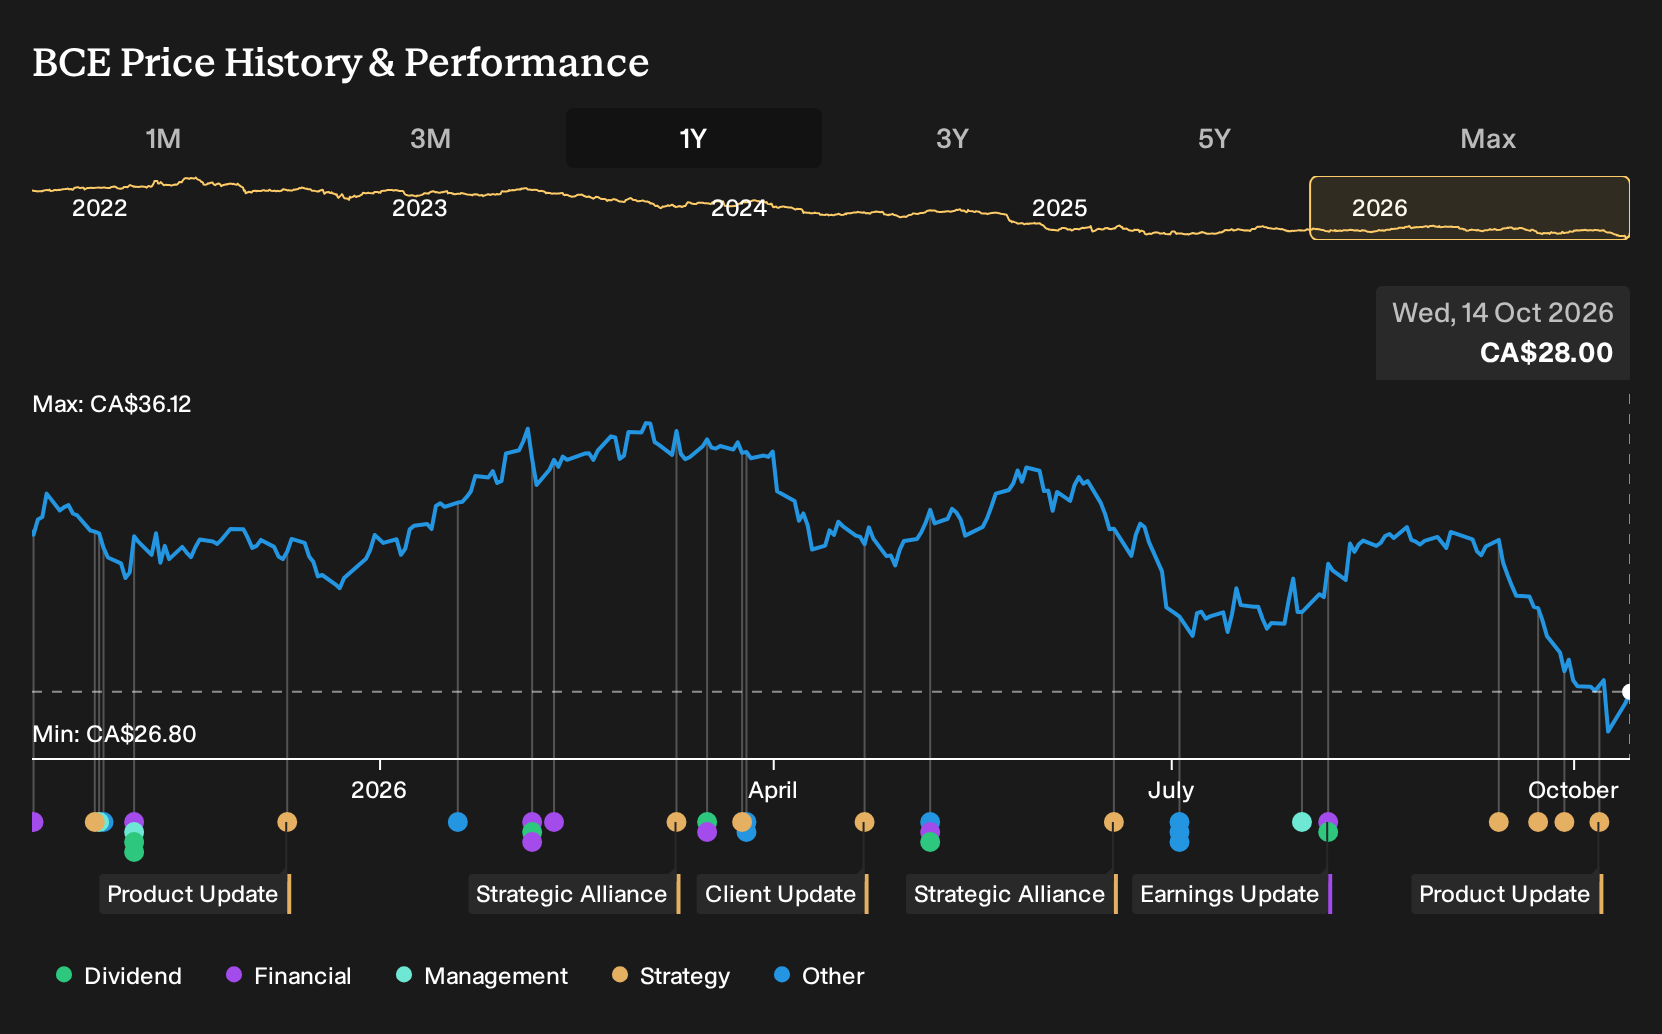
Exploring Other Perspectives
One alternate view says the real swing factor for BCE is not wireless ARPU at all, but whether the Saskatchewan AI Fabric build and broader 800 MW pipeline truly earn their keep. The most pessimistic analysts were pencilling in flat revenue around CA$25.4b and earnings of CA$2.2b by 2029. That is a much harsher setup than consensus. The ahlo 2 launch, with its clear value pitch, could nudge opinions on churn and cash generation either way. It is therefore worth comparing several forecasts before deciding which story you find more convincing.
Explore 4 other BCE fair value estimates, including one that suggests it could be worth just CA$32.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your BCE research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for BCE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BCE's overall financial health at a glance.
Looking For More Investment Ideas Beyond BCE?
If the ahlo 2 launch has you thinking about where BCE fits in your wider portfolio, it can be useful to line it up against other opportunities with clear financial filters. The Simply Wall St Screener lets you quickly scan for businesses that better match your risk tolerance, income needs or value preferences.
- If capital preservation comes first for you, consider stocks that have scored well on stability and financial risk using our 8 resilient stocks with low risk scores.
- Income focused investors who care about consistency may prefer companies that qualify as 3 dividend fortresses, where yields are higher and payments are a central part of the thesis.
- For readers hunting for underfollowed opportunities with sturdier fundamentals, the 10 high quality undiscovered gems can surface lesser known ideas that still pass quality checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com