


Dividend Increase Might Change The Case For Investing In MSC Industrial Direct Stock (MSM)
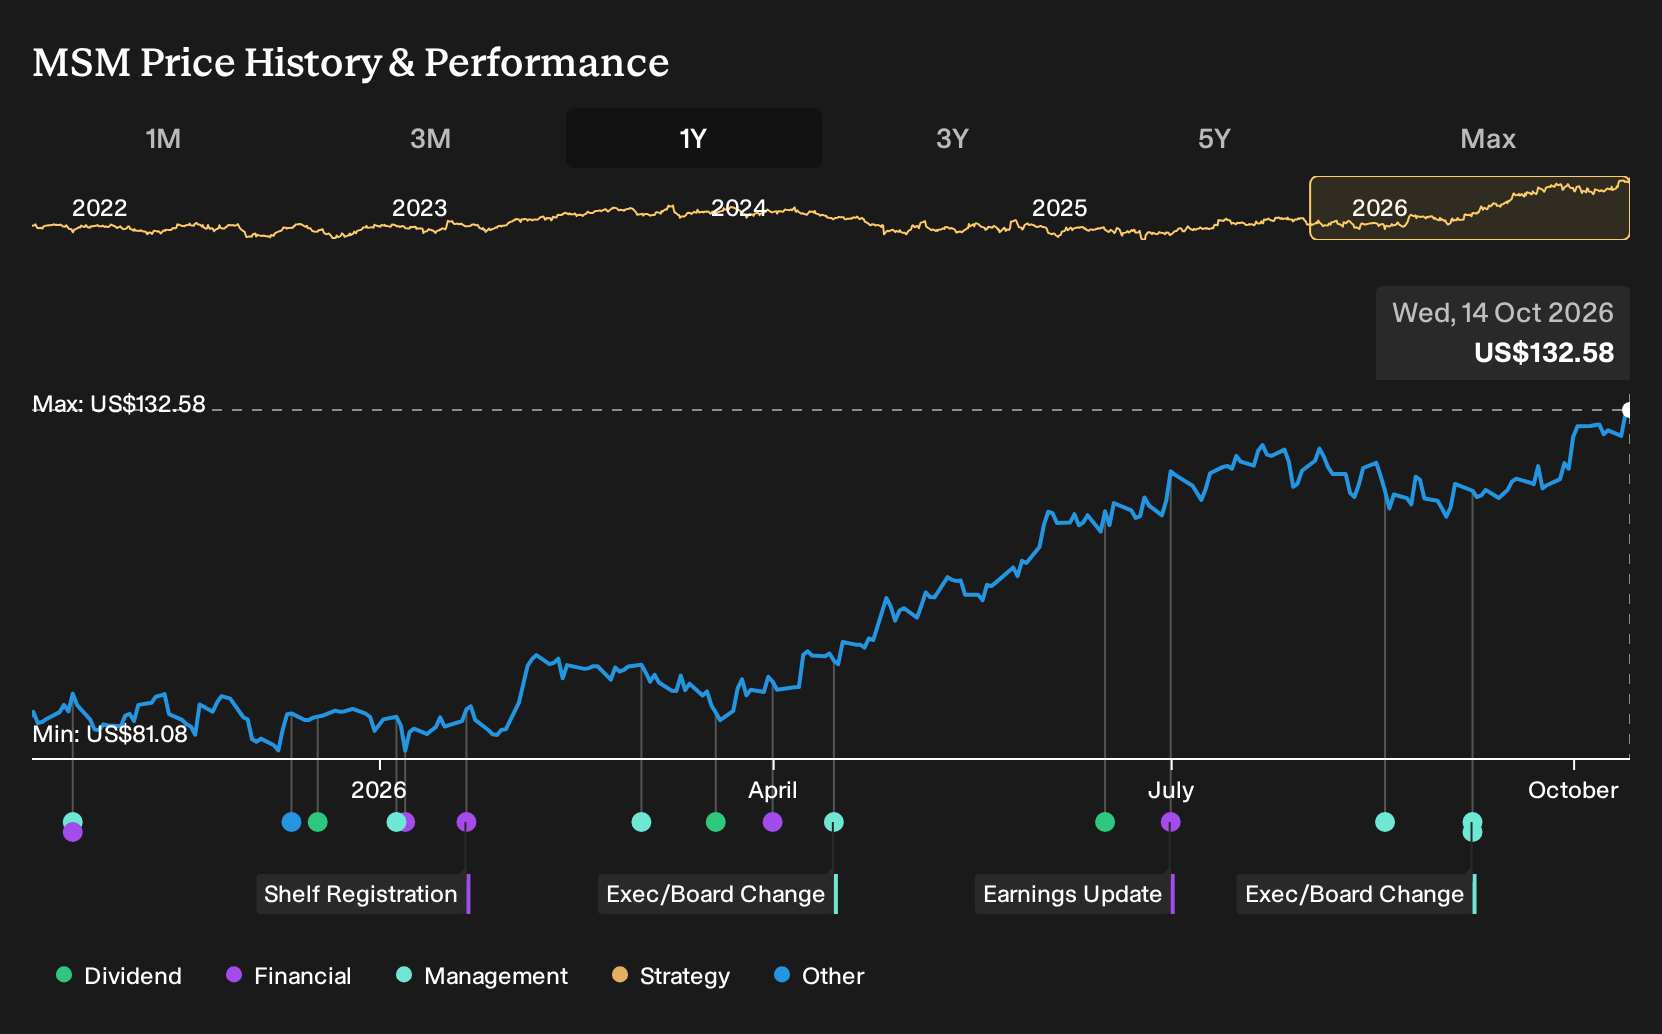
- MSC Industrial Direct's board previously approved a higher regular cash dividend of $0.89 per share, payable on November 25, 2026, to shareholders on record as of November 11, 2026.
- The richer payout is directly linked to MSC Industrial Direct's cash generation and capital allocation choices, which matter for investors tracking execution on cost savings and productivity plans.
- We will now look at how MSC Industrial Direct's investment narrative is shaped by this higher recurring cash dividend commitment.
Scan how MSC Industrial Direct's richer dividend compares with peers by reviewing our hand picked 7 dividend fortresses across the income focused corner of the market.
MSC Industrial Direct Investment Narrative Recap
To own MSC Industrial Direct, you need to be comfortable with a distribution business that leans heavily on execution. The thesis rests on cost savings, productivity gains and scaled programs like in plant solutions and vending, rather than rapid end market growth. The higher dividend signals confidence in cash generation, but on its own it does not change the near term story.
The key short term swing factor remains demand and volume trends, given recent average daily sales and volume pressure. The biggest risk is that cost cuts, headcount changes and sales force redesign create disruption without delivering enough efficiency, which would leave margins exposed if pricing support or order activity soften.
The recent dividend decision is the most directly relevant announcement. A quarterly payout of US$0.89 per share means more cash earmarked for shareholders, and it feeds directly into how you think about MSC Industrial Direct’s capital deployment relative to its ongoing automation and distribution investments.
For catalysts, the interest lies in whether the richer dividend can sit alongside the multi year cost and productivity program without squeezing flexibility. If freight efficiencies, network optimization and e commerce growth continue to support earnings quality, the larger recurring dividend can align with the broader story. If execution stumbles, that commitment could feel tighter against other priorities.
MSC Industrial Direct's narrative projects US$4.7b revenue and US$352.1 million earnings by 2029. This assumes 6.0% yearly revenue growth and an earnings increase of about US$120.9 million from US$231.2 million today.
Uncover why MSC Industrial Direct's fair value aligns with its current price.
Exploring Other Perspectives
Some of the lowest MSC Industrial Direct forecasts lean hard on inventory risk rather than just demand softness. Those analysts expected about US$4.5b of revenue and US$334.8 million of earnings by 2029, which is materially below consensus. They have not baked in this higher dividend yet, so their story could shift as the payout commitment sinks in.
Explore 2 other MSC Industrial Direct fair value estimates, including one that suggests as much as 28% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your MSC Industrial Direct research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for MSC Industrial Direct. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MSC Industrial Direct's overall financial health at a glance.
Looking For More MSC Industrial Direct Style Ideas?
If the MSC Industrial Direct story has you thinking about where else dependable cash flows, solid execution or resilient balance sheets might show up, the Simply Wall St Screener can help you widen the field without losing focus on quality.
- For investors who want income first, scan for payout opportunities that aim to combine yield with staying power through the 7 dividend fortresses.
- If capital preservation matters most to you, filter for businesses that pair measured risk profiles with durable fundamentals using the 32 resilient stocks with low risk scores.
- When you are hunting for future leaders before the crowd pays attention, search through the 20 high quality undiscovered gems and see what is hiding off the main radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com