


McGrath RentCorp (MGRC) Extends Its Dividend Run, Is The Stock Cheap Or Pricey?
McGrath RentCorp (MGRC) again put its dividend track record in focus after fresh data showed the payout has been raised in most years since 1999 and remains covered by trailing earnings.
Recent trading has been choppy for McGrath RentCorp, with the share price down 2.3% over the past day and 7.5% over the last 90 days. However, the year-to-date share price return of 6.4% and a 5-year total shareholder return of 60.6% still point to longer term momentum that dividend-focused investors are weighing against the current income profile.
Compare McGrath RentCorp's income profile with a curated 7 dividend fortresses that also prioritize resilient payouts and consistent shareholder returns.
McGrath RentCorp looks like a solid rental platform on the surface, yet the recent share price pullback raises a sharper question: Are investors being offered real value here or just paying up for quality?
Most Popular Narrative: 23% Undervalued
McGrath RentCorp's most followed valuation storyline pegs fair value at $145.40 against a last close of $111.97, so the debate is about what has to go right for that gap to close.
Increased 2026 gross rental equipment capital expenditure guidance to US$200 million to US$220 million, with a focus on adding TRS capacity while funded debt to EBITDA remains near 1.65x, points to further scaling of the rental fleet that can lift future rental revenues and earnings if utilization stays healthy.
A larger US$725 million five year credit facility arranged in May 2026, alongside 35 consecutive years of dividend increases and US$52 million returned to shareholders in the first half of 2026, gives McGrath RentCorp financial flexibility to keep funding growth investments while supporting earnings and cash flow available to shareholders.
See why 2 investors see McGrath RentCorp as 23% undervalued.
Result: Fair Value of $145.40 (UNDERVALUED)
Still, softer utilization in Portable Storage and the sharp Enviroplex revenue drop to US$8 million, combined with an adjusted EBITDA loss, could easily challenge the bullish McGrath RentCorp narrative.
Find out about the key risks to this McGrath RentCorp narrative.
Another View: What McGrath RentCorp’s P/E Is Really Saying
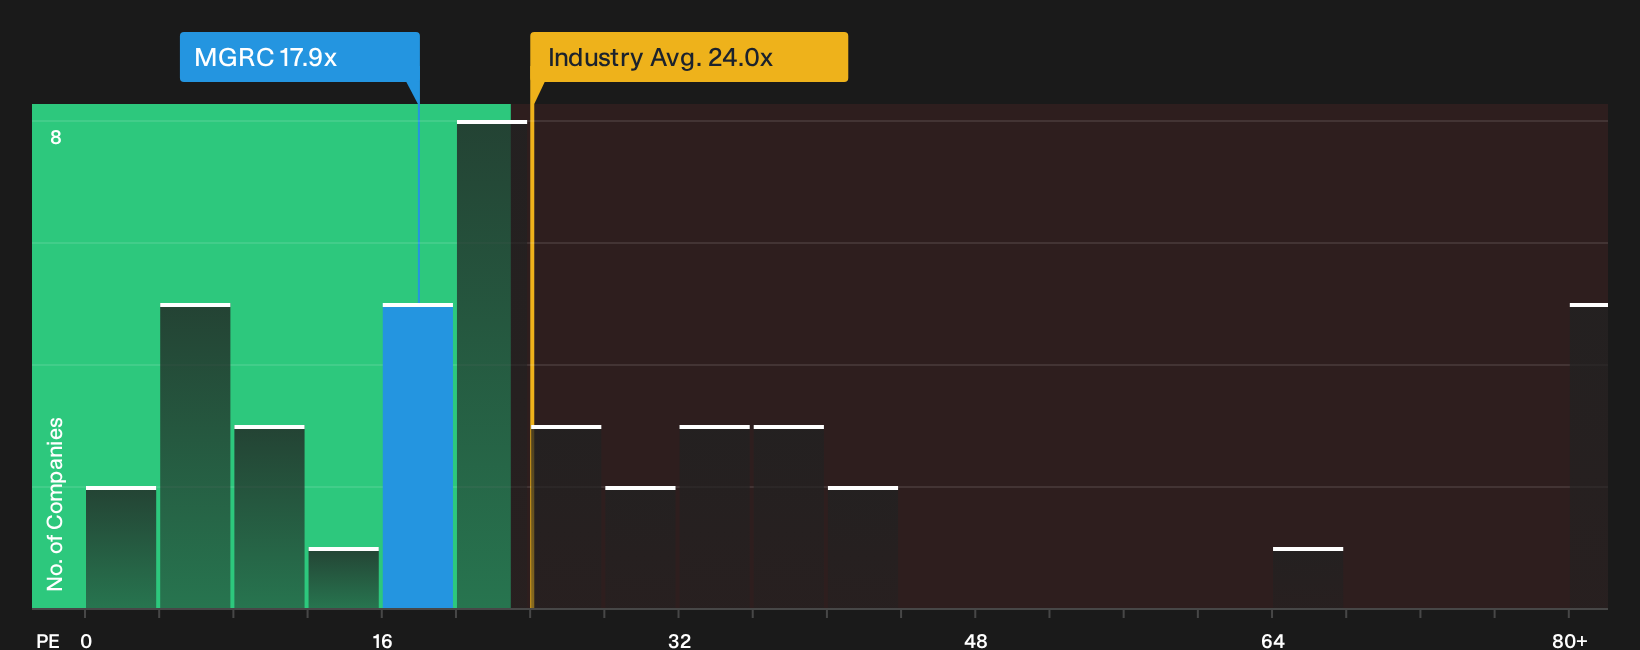
The first story paints McGrath RentCorp as undervalued using a fair value of $145.40 against a $111.97 share price. A different lens tells a cooler story. The current P/E of 17.9x sits above a fair ratio of 16.9x, which points to a mild valuation premium instead of a discount.
That same 17.9x earnings multiple looks cheap beside peer and industry figures of 44.2x and 24.5x, so investors weighing MGRC have to decide what matters more: the small premium to the fair ratio or the wide gap to rivals on P/E.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With both upside potential and real concerns in play, it pays to check the data directly and decide where you land on McGrath RentCorp. To see how the positives stack up next to the red flags, review the 4 key rewards and 3 important warning signs
Looking For More Investment Ideas Beyond McGrath RentCorp?
If McGrath RentCorp has sharpened your focus on valuation and income, you may want to broaden your watchlist with a few focused stock ideas sourced directly from the Simply Wall Street Screener.
- Target dependable income by reviewing stocks with resilient payouts and consistent track records using the 7 dividend fortresses.
- Hunt for potential mispriced opportunities by scanning a curated pool of quality companies through the 32 high quality undervalued stocks.
- Reduce portfolio stress by concentrating on businesses with cleaner finances using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com