


How Investors Are Reacting To Glencore (LSE:GLEN) Broker Upgrade
- Glencore secured approval for the MARA project under Argentina's large investment regime, tying the Agua Rica deposit to existing Alumbrera facilities and supporting about 2,000 jobs in Catamarca while keeping critical copper processing infrastructure active.
- The use of Alumbrera's concentrator and logistics for the Agua Rica ore points to potential operating efficiencies for Glencore, which sits alongside broker commentary highlighting copper volume exposure and geopolitical diversification.
- Next, the focus shifts to how Glencore's investment narrative could be shaped by MARA's scale and copper exposure within its broader portfolio.
What Is Glencore's Investment Narrative?
To own Glencore, you need to be comfortable with a global commodities group that lives and dies by execution, capital discipline and pricing in volatile markets. MARA approval under Argentina's large investment regime plugs directly into that story. Using Alumbrera's existing concentrator and logistics for the Agua Rica ore is an operational call. It aims to keep 2,000 people working, keep copper infrastructure warm and reduce ramp up risk rather than betting on a greenfield build.
Short term, the real swing factors remain commodity prices, marketing performance and how comfortably earnings cover interest and dividends. Revenue recently declined 4.8% year on year while net income rose 3.8%, which shows how sensitive the model can be to mix and pricing. MARA increases copper exposure and potential economies of scale but also adds capital intensity and country risk on top of already tight interest coverage and a dividend that is not fully supported by free cash flow.
Even so, there is a single structural weak spot in the Glencore story that only really comes into focus once you look at...
There's only one way to know the right time to buy, sell or hold Glencore. Head to Simply Wall St's company report for the latest analysis of Glencore's Fair Value.
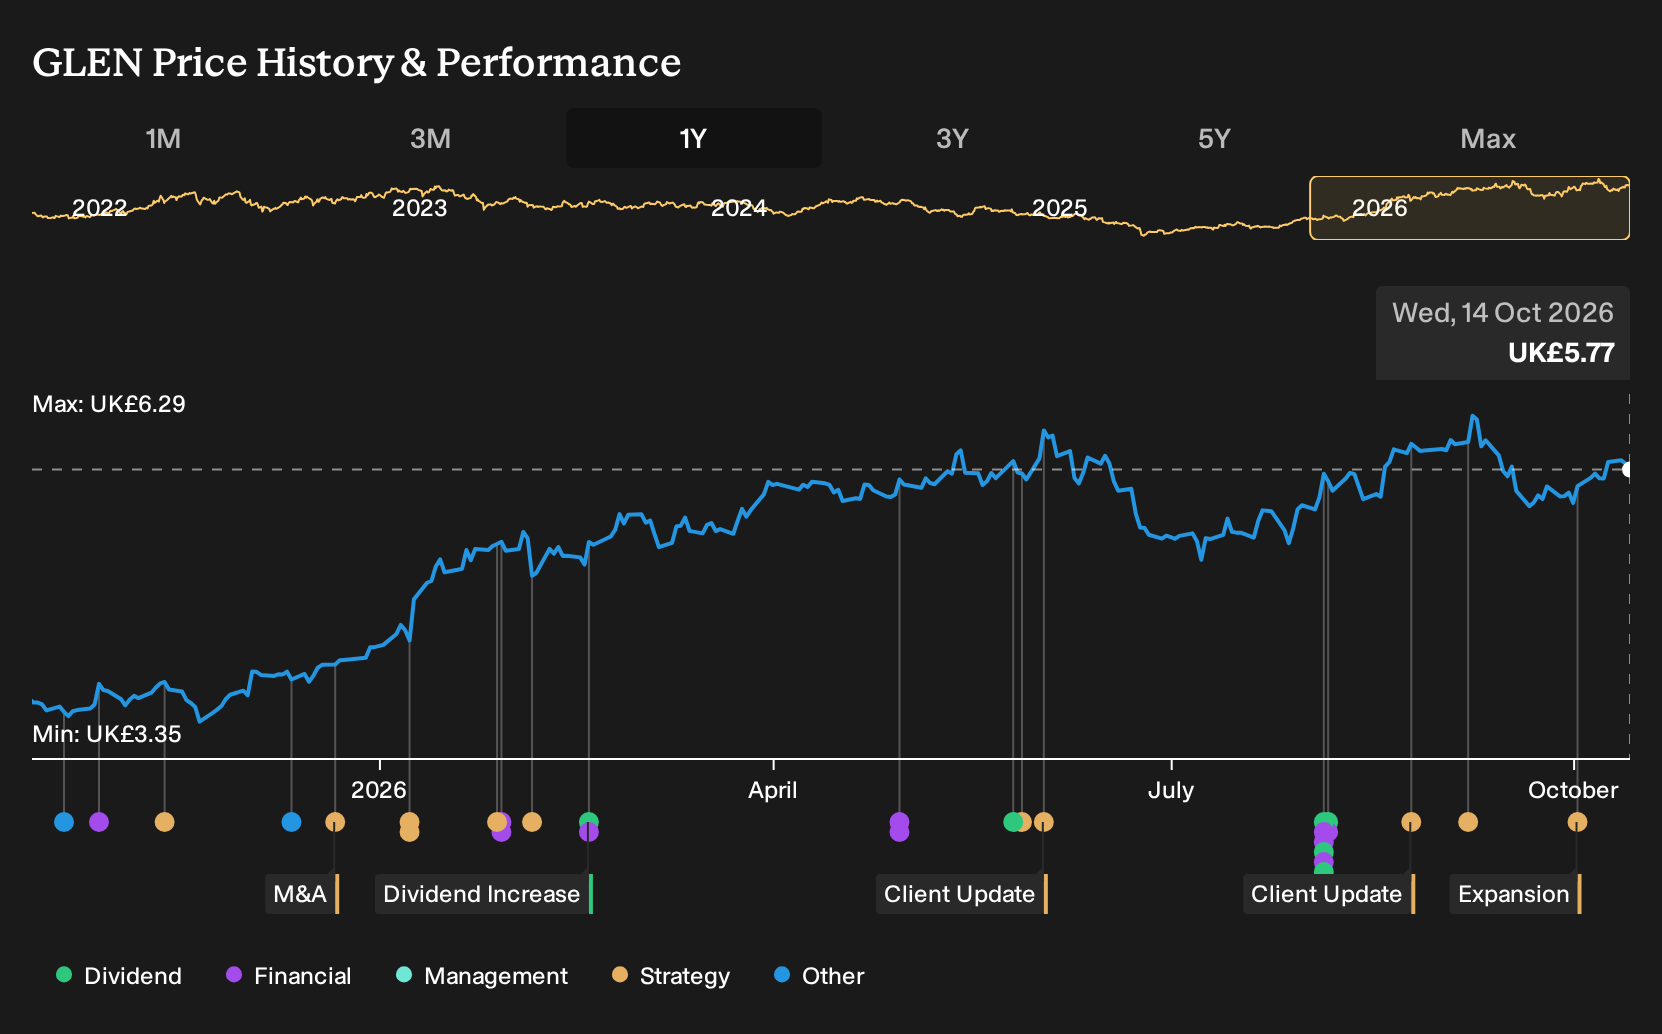
Exploring Other Perspectives
Some of the more conservative analysts focus squarely on copper project execution risk for Glencore. They were already pencilling in revenue declining about 9.7% a year and earnings easing from roughly $5.4b today to $4.3b by 2029. That is a far more cautious story. Use MARA’s approval as a prompt to compare those assumptions with your own and explore how this news could reshape the range of views.
Explore 4 other Glencore fair value estimates, including one that suggests as much as 23% downside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Glencore research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Glencore. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Glencore's overall financial health at a glance.
Looking For More Investment Ideas Beyond Glencore?
Glencore's MARA approval may have put copper back on your radar, but your portfolio does not need to hinge on a single story. You can use this as a springboard to scan a wider opportunity set with the Simply Wall St Screener and line up a few more candidates that fit your risk profile and income goals.
- If you want potential value combined with quality fundamentals, you can start by scanning through 8 high quality undervalued stocks that already clear high bars on cash flows and balance sheets.
- If capital preservation matters just as much as upside, you can filter for 4 resilient stocks with low risk scores that score well on financial health and business stability checks.
- If you prefer companies that are still under the radar, you can broaden your watchlist with a hand picked set of 5 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com