


Sinopec (SEHK:386) Stock Looks Undervalued As Ultra Deep Oil News Emerges
China Petroleum & Chemical has delivered a 75.7% return over the past five years, so the key issue now is whether the current share price around HK$4.59 is supported by the earnings investors are paying for.
- A 75.7% gain over five years puts real weight on the question of whether Sinopec's present earnings power can support this kind of long term shareholder outcome.
- Fresh progress in ultra deep oil resource development in China, including fields associated with state owned groups such as Sinopec, can affect expectations for how stable and capital intensive the company's future earnings stream may be.
- The analysts covering China Petroleum & Chemical have run their own numbers. See what analysts think China Petroleum & Chemical's shares could be worth.
The issue now is whether China Petroleum & Chemical's current valuation is justified by the profits it generates today and what investors expect those earnings to look like over time.
If you are weighing China Petroleum & Chemical against other long term earnings stories, it can help to compare it with 188 high quality undervalued stocks.
Is China Petroleum & Chemical a Bargain on Earnings?
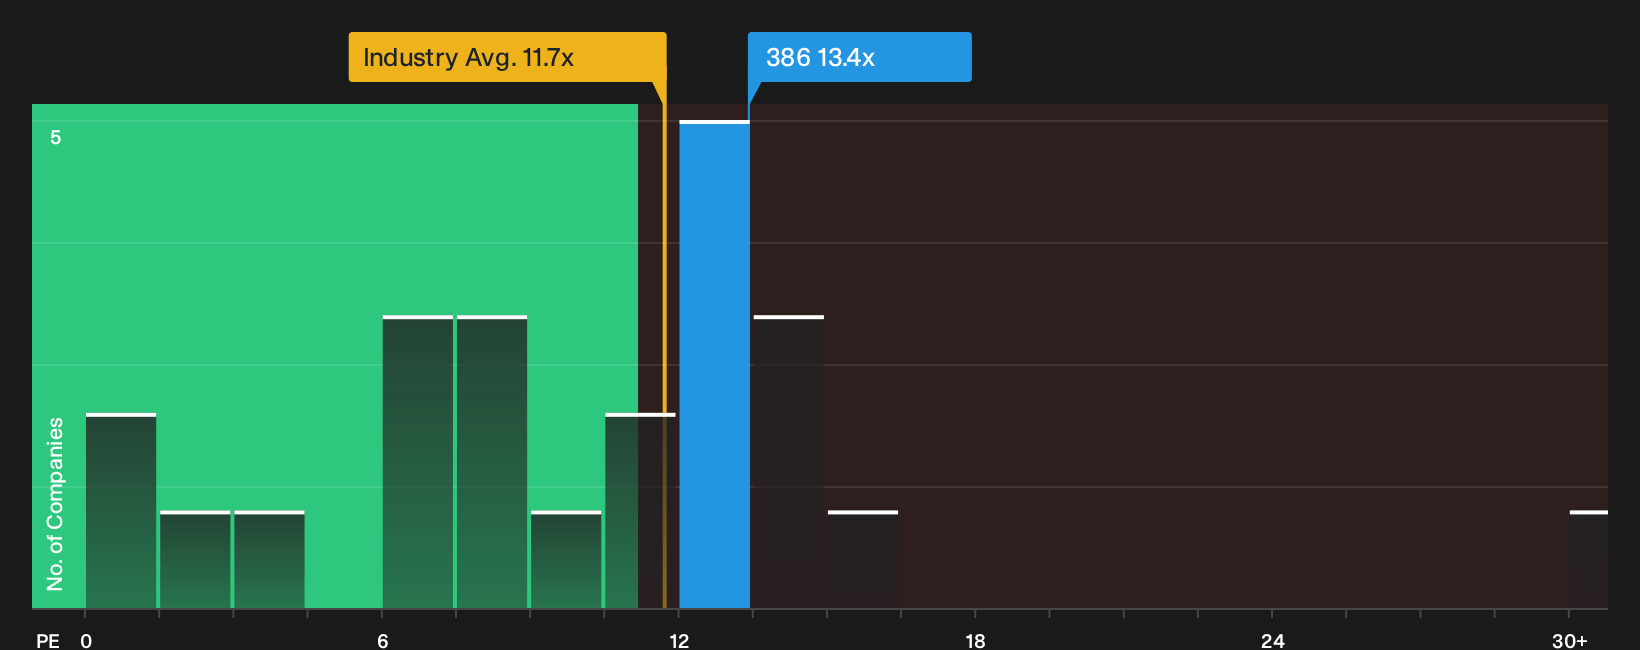
The P/E ratio fits China Petroleum & Chemical because investors often anchor oil and gas valuations on current earnings power. At about 13.4x earnings, the stock trades slightly above its oil and gas industry average near 13.0x, and at a premium to the peer group around 10.2x. That indicates the market is willing to pay somewhat more for each unit of profit than for a typical sector peer.
Recent progress in ultra deep fields like Hade Fuman and Sinopec linked projects has kept attention on the durability of China Petroleum & Chemical's earnings stream, yet the current P/E still comes in below what a tailored model suggests for the business. That framework, which blends the firm’s growth outlook, margins, size and risk profile into a single reference multiple, indicates the shares trade below the level implied by those fundamentals. For an investor weighing whether the market is already baking in rich expectations, the current P/E points to a valuation that screens as undervalued relative to that fair benchmark. Explore the numbers behind China Petroleum & Chemical's P/E valuation.
The China Petroleum & Chemical Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for China Petroleum & Chemical pick up where the P/E puzzle leaves off and spell out which paths for future growth, margins and earnings would need to hold for the stock to be worth far more or materially less than today’s price. Instead of a single output from a ratio or model, they lay out the underlying future those numbers rely on so you can later judge whether that story is still playing out. These scenarios live on Simply Wall St's Community page.
One of the top community narratives on China Petroleum & Chemical: 10% undervalued
"The main factor that has to go right is that China Petroleum & Chemical successfully offsets declining gasoline and diesel consumption by scaling high end PVA, sustainable aviation fuel, CCUS partnerships and other new energy linked businesses..."
Discover why this Narrative puts China Petroleum & Chemical at 10% undervalued.
China Petroleum & Chemical's price is only one piece of the decision
Before you treat China Petroleum & Chemical as just a set of ratios and scenarios, it is worth asking who is steering this business, how their rewards are structured, and whether those incentives truly line up with your interests. See who runs China Petroleum & Chemical and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com