


Vail Resorts (MTN) Faces Price Fixing Suit, Is The 18% Upside Still Real?
On October 6, 2026, a shareholder filed a derivative lawsuit against executives and directors of Vail Resorts (MTN), alleging participation in a horizontal price fixing arrangement with competitors that could expose the business to antitrust liability and reputational pressure.
The lawsuit lands after a choppy stretch for Vail Resorts, where the share price delivered an 11.56% year to date gain and a modest 0.21% 90 day share price return, while longer term total shareholder returns of 8.20% over one year and declines of 21.09% over three years and 45.83% over five years point to momentum that has yet to convincingly rebuild.
Scan how other resort and leisure operators stack up on pricing power and legal risk by reviewing our curated list of 32 resilient stocks with low risk scores alongside Vail Resorts today.
Given the recent legal overhang and only modest share price gains, the question is whether Vail Resorts is being repriced for weaker fundamentals or is simply caught in a shift in investor mood that the valuation no longer supports.
Most Popular Narrative: 17.6% Undervalued
Vail Resorts last closed at $149.45, while the most followed narrative anchors on a Fair Value estimate of $181.43. This frames the current antitrust overhang against a longer term earnings and cash flow story priced at a discount.
The numbers imply the share price treats recent weather impacted earnings, elevated leverage and activist uncertainty as more permanent than might be suggested by a business that is guiding to higher fiscal 2027 resort reported EBITDA and incremental efficiency gains.
See why 1 investors see Vail Resorts as 18% undervalued.
Result: Fair Value of $181.43 (UNDERVALUED)
Still, dividend pressure after a weak fiscal 2026 and the Oasis campaign pushing for portfolio changes could quickly challenge the bullish Vail Resorts narrative.
Find out about the key risks to this Vail Resorts narrative.
Another View: Vail Resorts Looks Expensive On P/E
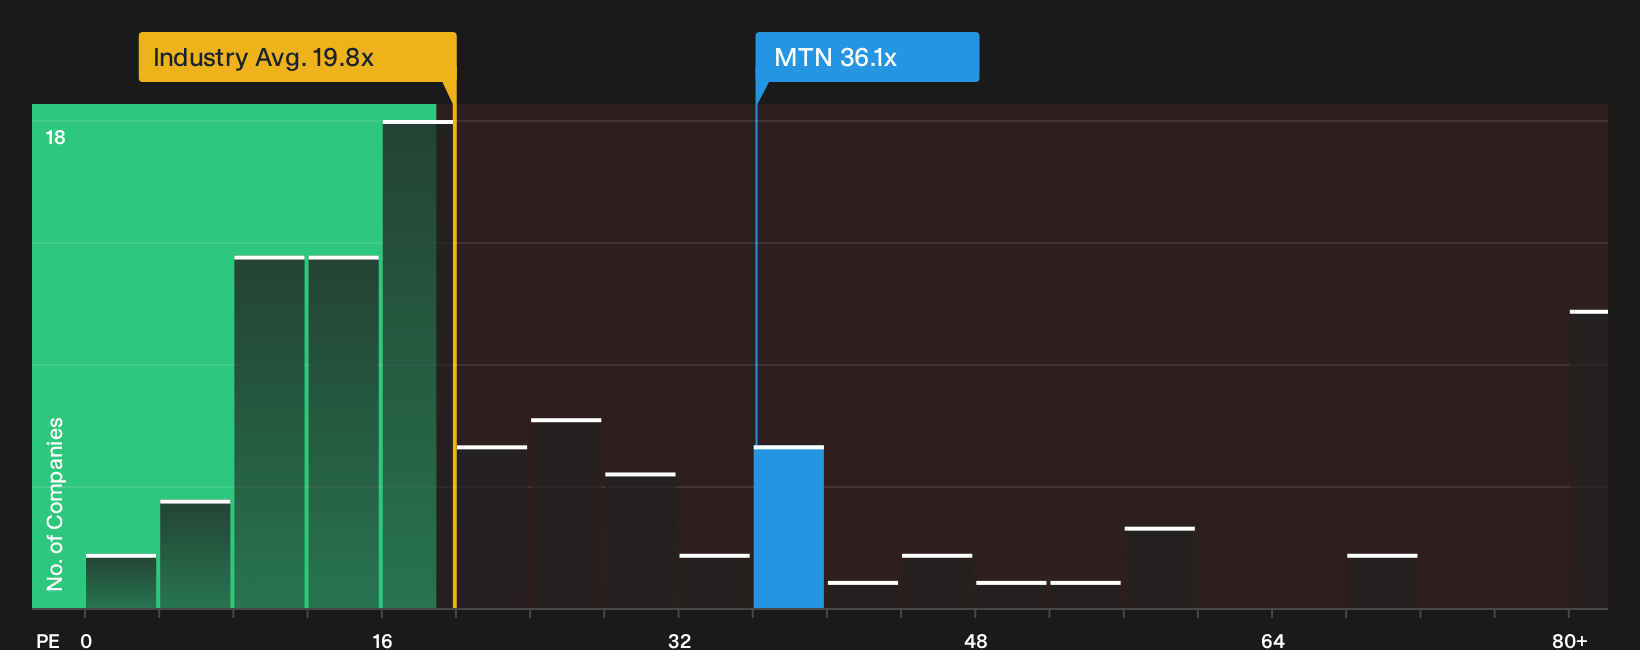
DCF work presents Vail Resorts as undervalued. However, the current P/E of 36.1x is far above the US Hospitality industry on 19.9x, the peer average on 20.6x, and a fair ratio of 23x that the multiple could migrate toward. Is the premium a cushion, or a valuation trap in the making?
For a closer look at how these earnings multiples line up against fundamentals and what the gap could mean for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of legal risk, valuation debate and sentiment around Vail Resorts feels conflicted, move fast and review the underlying data points yourself using the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Vail Resorts?
Do not stop at Vail Resorts. Use the wider opportunity set to pressure test your thinking and spot setups that fit your own risk and return preferences.
- Target potential mispricing by scanning companies flagged as having strong fundamentals and attractive valuations through the 32 high quality undervalued stocks.
- Strengthen your income stream by reviewing the 7 dividend fortresses and focusing on businesses that pair higher yields with resilient cash generation.
- Prioritise financial resilience by filtering for companies on the list of solid balance sheet and fundamentals (25 results) that combine sturdier balance sheets with consistent operating profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com