


Pearson (LSE:PSON), Why Is This Latest Update Drawing Attention?
Pearson (LSE:PSON) just expanded its Pearson Studios portfolio with Career Studio for School and Career Studio for Work, aiming to tighten the link between education, AI driven skills training, and workforce readiness.
That product push lands against a share price that has climbed, with a year-to-date share price return of 28.49% and a 1-year total shareholder return of 23.28%. The 5-year total shareholder return of 136.67% points to momentum that buyers will now be weighing against fresh execution risk around Pearson Studios.
Scan how Pearson fits into the wider education and AI skills story by comparing it with a curated set of 39 profitable AI stocks that aren't just burning cash.
Pearson shares have already rerated on this AI skills story, so the puzzle now is whether today’s price rewards that shift fairly or whether patience could offer a cleaner entry.
Most Popular Narrative: 7% Overvalued
The most followed valuation narrative puts Pearson’s fair value at £12.24, compared with the last close at £13.10, so the current AI and skills story is being judged as slightly ahead of that anchor.
The analyst price target for Pearson in this update edges higher to reflect a fair value move to about £12.24, as analysts factor in slightly adjusted assumptions for discount rate, revenue growth, profit margin and future P/E. Recent research broadly maintains a Neutral or Equal Weight stance, with price targets clustered between about £13.35 and £14.20.
See why 18 investors see Pearson as 7% overvalued.
Result: Fair Value of £12.24 (OVERVALUED)
Still, the story can break if Pearson’s contract driven units hit delays, or if FX swings and weaker enrolments make those projected margins harder to sustain.
Find out about the key risks to this Pearson narrative.
Another View: Pearson Through A Cash Flow Lens
Analysts calling Pearson about 7% overvalued on a £12.24 fair value are leaning on explicit earnings and multiples. The SWS DCF model, which prices the shares at £15.47, instead frames £13.10 as a discount to future cash flows and puts the burden on you to judge which story feels more robust.
To pressure test that cash flow view against your own assumptions on growth, margins and discount rates, Look into how the SWS DCF model arrives at its fair value.
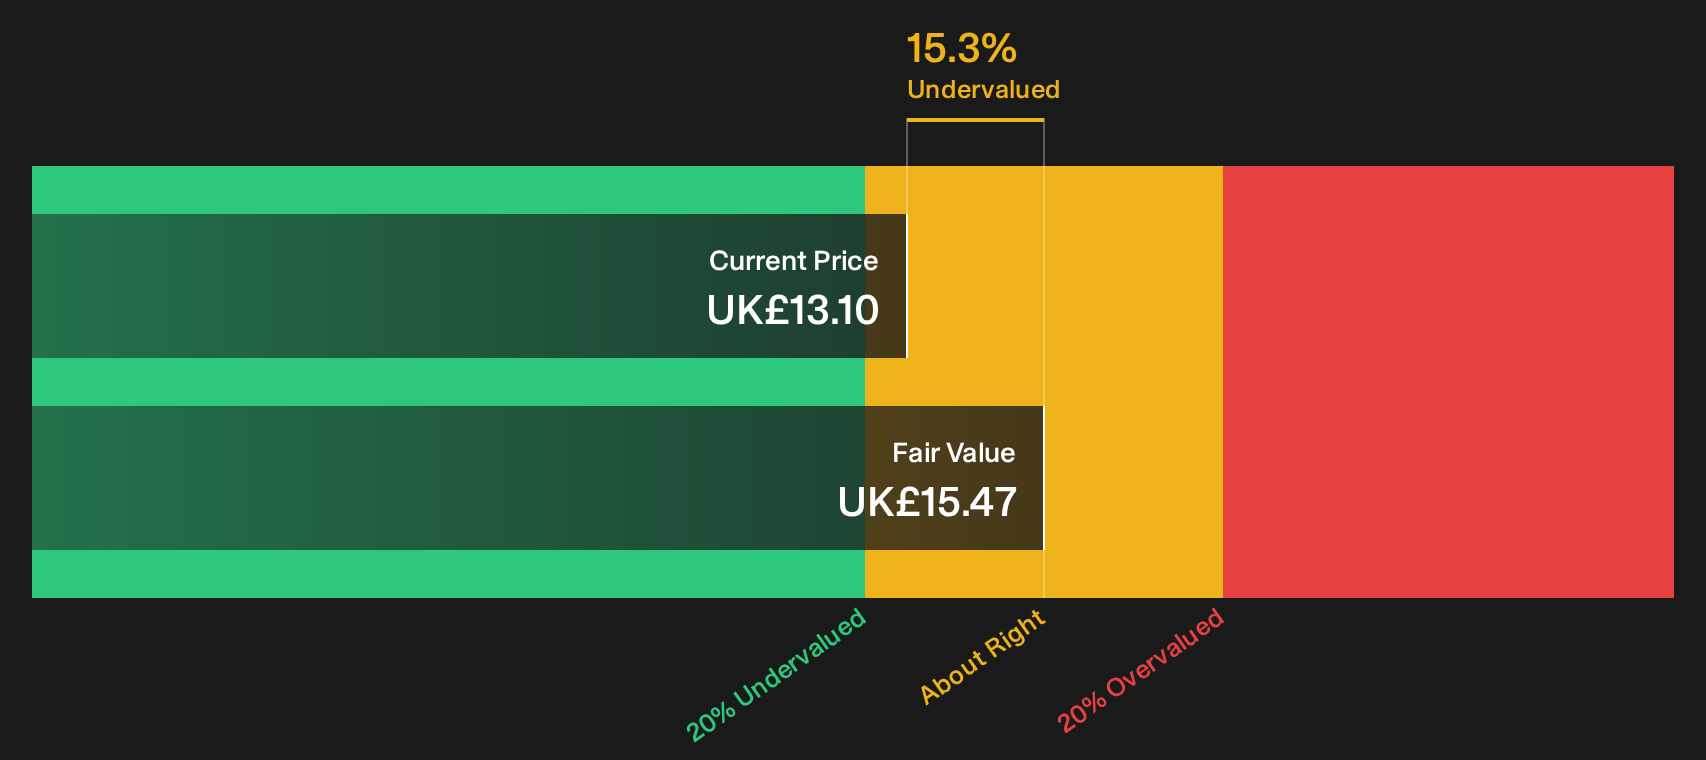
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Pearson for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 8 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Pearson is divided enough that waiting for perfect clarity could mean watching the opportunity pass by. Assess the potential upside drivers yourself and then weigh them against 2 key rewards.
Looking for more investment ideas beyond Pearson?
If the Pearson story has you thinking about portfolio upgrades, use this moment to line up a few fresh contenders that fit your own risk and return preferences.
- Target resilient capital by scanning companies with strong cash generation and low valuation pressure through the 8 high quality undervalued stocks.
- Build a steadier income stream by focusing on companies in the 3 dividend fortresses that pair higher yields with durable payout histories.
- Guard against unwelcome surprises by filtering for sturdier balance sheets and cleaner fundamentals using the list of solid balance sheet and fundamentals (9 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com