


3 US Stocks Banks May Need More As Debanking Scrutiny Grows
Regulators are turning up the heat on big banks over alleged politically driven debanking, and that pressure can ripple far beyond the financial sector. When legal, compliance and reputational risks move to the front page, specialist professional services firms often move to the front of the queue for bank spending. This article unpacks the story and profiles 3 stocks that could be positioned on the right side of this shift.
The three stocks profiled below are only a starting sample, and the full screen surfaced 16 more U.S. professional services firms with equally compelling regulatory and reputation risk narratives that are not covered here. To identify which businesses best fit your own thesis on legal, compliance, and advisory partners to financial institutions, analyze the US Professional Services Firms Focused on Regulatory, Legal, and Reputation Risk for Financial Institutions screener.
Andersen Group (ANDG)
Andersen Group provides independent tax, valuation, and financial advisory services that directly tie into the legal, compliance, and oversight work financial institutions rely on. It generates about US$913 million from a single advisory-focused segment in the U.S., with a market value of roughly US$6.6b.
Andersen Group sits squarely in the regulatory and tax advisory lane that big banks lean on when scrutiny rises. With about US$913 million in advisory revenue and a roughly US$6.6b market value, it meets the screener’s size and quality bar. Investors get a specialist in financial oversight work, although one unresolved funding pressure could have a real say in future profitability.
That funding overhang is exactly why it is worth checking the DCF valuation analysis for Andersen Group to see whether Andersen Group’s current pricing already reflects that pressure.
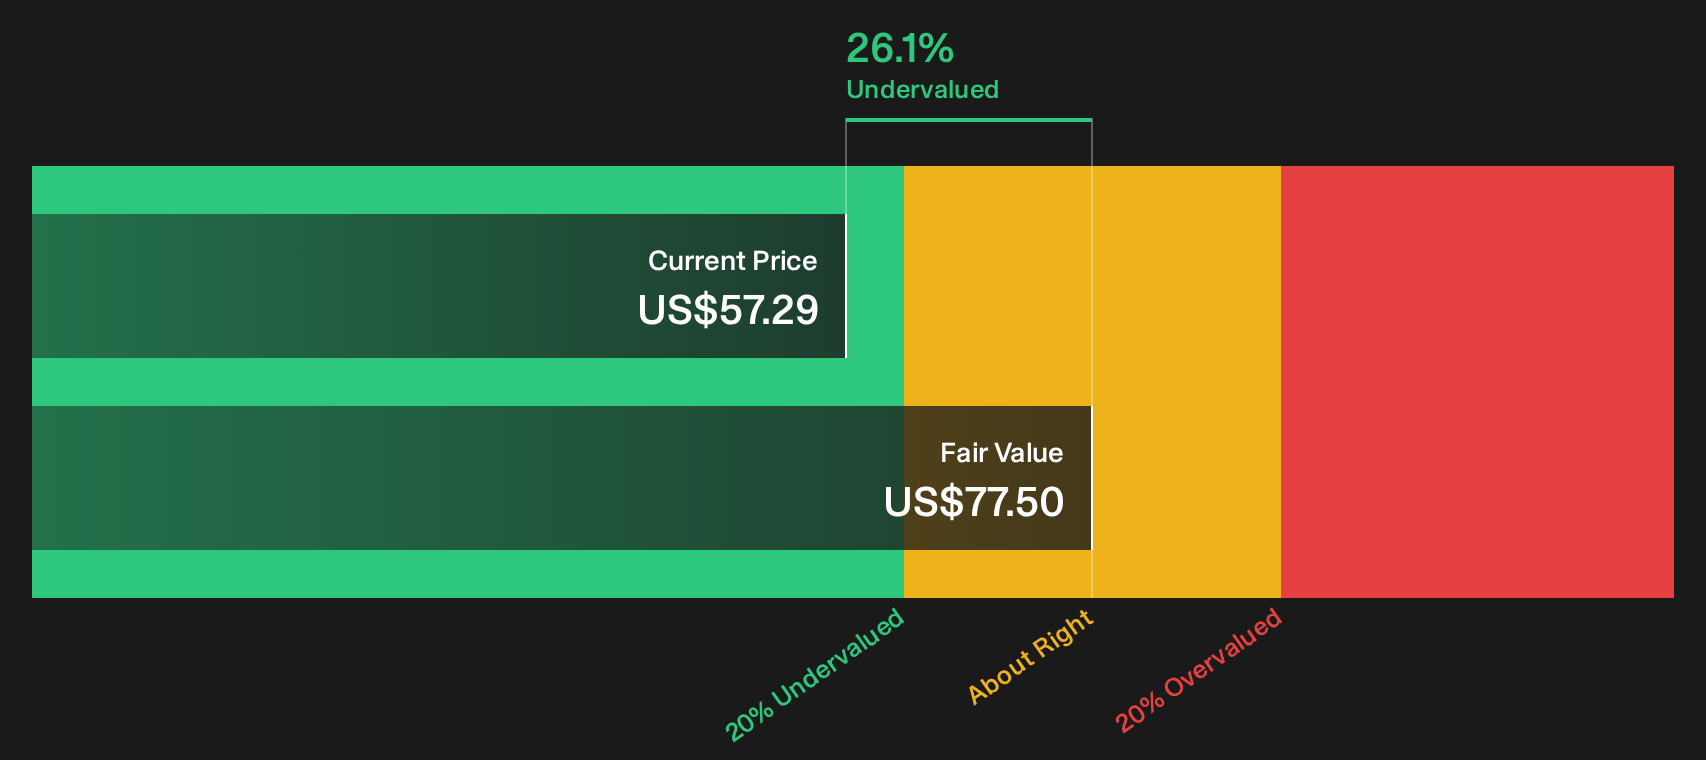
ExlService Holdings (EXLS)
ExlService Holdings is a data and AI specialist that uses analytics, digital operations, and monitoring tools to help insurers, healthcare payers, and banks manage complex processes, including work that can support regulatory, conduct, and compliance programs. It generated roughly US$758 million from Insurance, US$587 million from Healthcare and Life Sciences, US$505 million from Banking, Capital Markets and Diversified Industries, and US$387 million from International Growth Markets, with an equity value of about US$5.6b.
ExlService Holdings gives financial institutions and insurers something they increasingly need in a more heavily policed world: data driven oversight of critical workflows that can support compliance, conduct checks, and audit trails across claims, payments, and finance.
"Five years of mix shift into AI-led work has produced no gross margin expansion, and contracts are terminable without cause."
The real swing factor is how customers value ExlService Holdings when one quiet pressure on its AI heavy work finally moves either margins or demand.
When that pressure finally bites, the full narrative for ExlService Holdings shows how ExlService Holdings could turn stalled margins into accelerating value as workflows, pricing and client mix evolve.

Broadridge Financial Solutions (BR)
Broadridge Financial Solutions plugs directly into the screener’s theme through its role in handling investor communications, governance workflows, and regulatory reporting for banks and brokers. This makes its scale in these highly regulated niches worth a closer look.
Broadridge Financial Solutions runs two major engines, with about US$5.6b from Investor Communication Solutions and US$1.9b from Global Technology and Operations, and carries an equity value around US$19.0b.
"The continued shift toward digitization of financial services, supported by Broadridge Financial Solutions reporting proxy digitalization near 95% for equities and 80% for funds and more than 10% annual growth in customer communications digital revenue for four consecutive years, is increasing the mix of higher value digital services that can support recurring revenue growth and operating margin expansion."
The real watchpoint is how one less visible competitive pressure ultimately filters through to pricing power, client retention, and long term earnings quality.
That pressure point is exactly why the full narrative for Broadridge Financial Solutions digs into where Broadridge Financial Solutions’ digital strength could be masking both pricing power and overlooked earnings resilience.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities do not sit still. Breakout themes build momentum, then get caught by the crowd. Scan these curated ideas while it matters, under the radar for now, and consider them while they remain less widely followed.
- Spot cash generative businesses before momentum headlines pick them up by scanning a curated 32 high quality undervalued stocks that still trade like the market is half asleep.
- Focus on real earnings power in AI rather than hype by reviewing 39 profitable AI stocks that aren't just burning cash that already convert algorithms and data into tangible bottom line strength.
- Look for resilient balance sheets before stress tests bite by filtering for a list of solid balance sheet and fundamentals (25 results) so you are watching sturdier operators while weaker peers are still dropping.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com