


Caught Out By Dassault Systèmes' Slide? Here's What Bears Saw
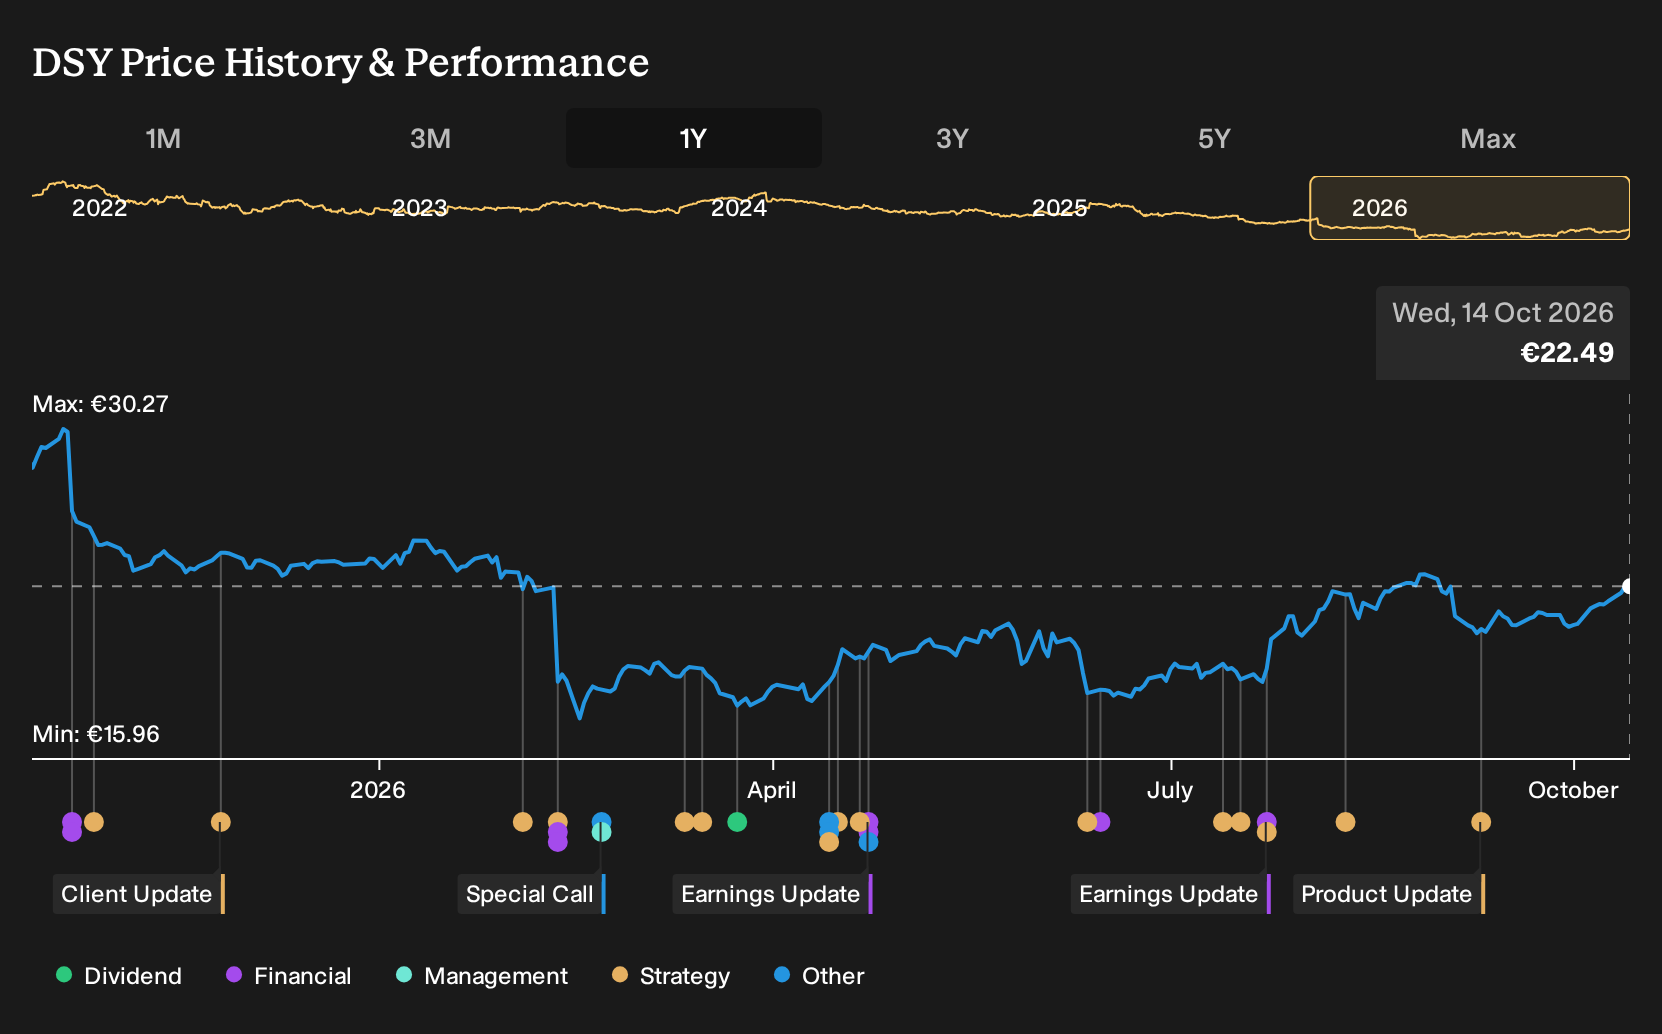
If you backed Dassault Systèmes for its digital twins, cloud shift and AI story, the past year will not have felt rewarding. Holding Dassault Systèmes over the past year would have meant a 21.1% loss, including dividends. If you made that call on 14 October 2025, you were leaning on bullish forecasts for recurring software, margins and life sciences. So what did that original thesis miss about adoption, competition or regulation that might explain this outcome?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
This theme extends beyond Dassault Systèmes. See which of 92 AI infrastructure stocks may still merit a closer look.
The Two Dassault Systèmes Stories Investors Had To Weigh
The shares cost €28.35 at the start of the period, and the debate around Dassault Systèmes centered on how powerful digitalization and AI could be for its software franchises.
The bullish Narrative pinned Fair Value at €35.56 and leaned on recurring software, with revenue assumed to grow 6.2% a year and profit margins rising from 18.0% to 22.3% by 2028.
The bearish case set Fair Value at €26 and highlighted pressure from cloud-native rivals, with margins still improving in the model but only to 21.4% on slower 4.9% revenue growth.
What The Results Changed For The Dassault Systèmes Thesis
The clearest test came from Dassault Systèmes’ Q2 2026 report. Total revenue reached €1,555.8m and net income €319.3m, with net margin at 20.5% versus 14.7% a year earlier. That move in profitability, together with the ArisGlobal deal and the Medidata Plus launch in life sciences AI, pointed toward the more optimistic recurring-software view rather than the more cautious interpretation.
The lesson is that the original call depended on recurring, higher margin software scaling. For any other stock built on that idea, track the subscription share of sales and net margin together in each set of results to see whether that investment story is being reflected in cash generation.
What You Are Paying For In Dassault Systèmes Today
Dassault Systèmes now trades at €22.49, and the selected Narrative’s Fair Value sits above that level based on its own modelling. The focus is less on broad digitalization stories and more on AI enabled 3DEXPERIENCE usage and life sciences software depth.
On that view, a buyer today would be assuming Dassault Systèmes can execute on its AI and cloud roadmap and translate Medidata and ArisGlobal into stronger recurring earnings.
"The growing focus on subscription and ARR economics, with subscription already at half of recurring revenue and cloud revenue growing faster than total software, gives Dassault Systèmes more scope to reprice, upsell and cross sell as contracts renew. This can support steadier revenue growth and expanding operating margins."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 49% below our estimate - targets long-duration data center buildouts supported by contracted E-Infrastructure projects.
- Company 2 - 46% below our estimate - relies on public-works backlog while labor and technology costs pressure margins.
- Company 3 - 21% below our estimate - emphasizes healthcare sealing programs and efficiency initiatives to maintain group margins.
That is three of the list. See the full list of 188 companies trading below our estimate →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com