


Is ERAMET (ENXTPA:ERA) A Bargain Following Its Argentina Lithium Expansion Plan?
Eramet (ENXTPA:ERA) has moved into focus after a board meeting on 12 October 2026 to finalize reference shareholders’ subscriptions ahead of a planned fourth quarter capital increase related to its lithium expansion plans.
Set against these expansion plans, ERAMET’s share price has been under pressure, with a year to date share price return of down 36.88% and a 1 year total shareholder return of down 40.91%. However, the 4.40% 1 day share price move hints at investors reassessing both growth potential and project execution risk as news around Centenario Ratones and the upcoming capital increase filters through.
Spot fresh opportunities in critical minerals beyond ERAMET by scanning our curated 32 best rare earth metal stocks, which could also be gearing up for their next major capacity moves.ERAMET now pairs a weak recent share price record with fresh lithium momentum, which raises a simple issue for new money: Does the current valuation still skew the risk reward in favour of buyers after this bounce?
Price-to-Sales of 0.4x: Is it justified?
On valuation, ERAMET changes hands at a P/S ratio of 0.4x, which is materially lower than both peers and the level suggested by its own fair ratio work.
The P/S multiple compares the market value of the equity to yearly revenue. It is a blunt but useful way to see how much investors are willing to pay for each euro of sales for a miner like Eramet, where earnings can swing with commodity prices and new projects.
Here the gap is wide. ERA is flagged as good value versus peers at 0.4x compared to a 1.3x average. It also screens as cheap relative to the wider European metals and mining group, where the mean sits at 1.1x. In addition, the estimated fair P/S ratio is 2x, which is a level the market could move towards if sentiment around profitability and lithium execution improves.
Explore the SWS fair ratio for ERAMET.
Result: Price-to-sales of 0.4x (UNDERVALUED)
Still, ERAMET faces clear pressure points, including a recent loss of €520.0m and multi year share price weakness that could limit any rerating momentum.
Find out about the key risks to this ERAMET narrative.
Another View: ERAMET Through The SWS DCF Lens
The market is pricing ERAMET low on sales at a 0.4x P/S ratio, yet the SWS DCF model points to a very different picture. At €38.88, the share price sits against an estimated future cash flow value of €75.08. This implies ERAMET trades at a 48.2% discount. If both numbers are right, which one do you trust with your capital?
Look into how the SWS DCF model arrives at its fair value.
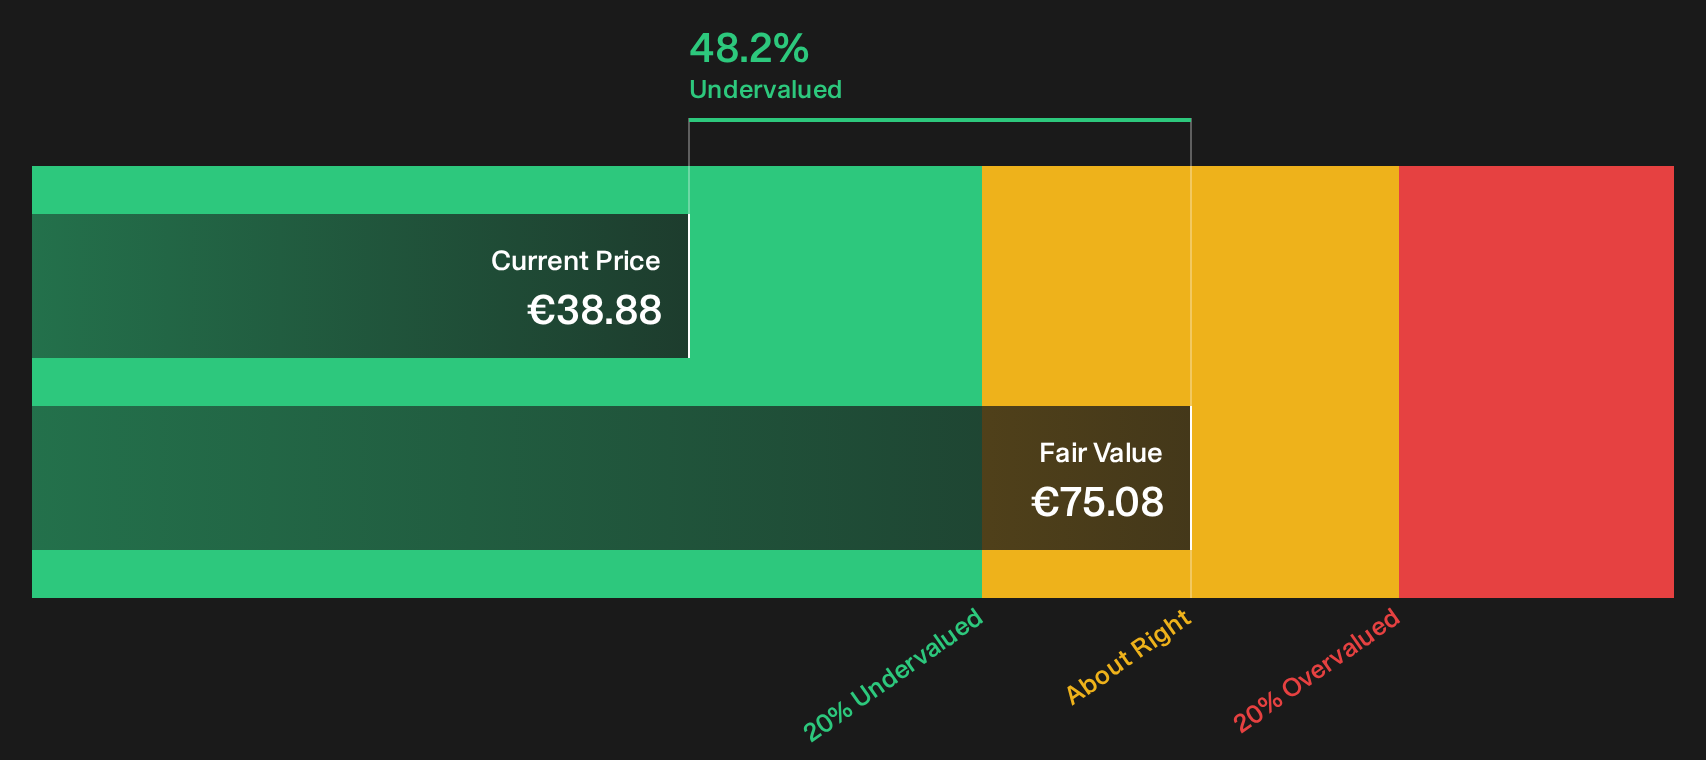
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ERAMET for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 188 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around ERAMET can feel confusing, yet the real edge comes from testing the numbers yourself and moving before sentiment settles. Take a closer look at the 4 key rewards and 1 important warning sign
Looking for more ideas beyond ERAMET?
If ERAMET has your attention but you want a broader watchlist, use targeted stock lists to quickly surface new opportunities that match your risk and income preferences.
- Target potential bargains by running through the 188 high quality undervalued stocks that combine attractive pricing with stronger fundamentals than the wider market.
- Lock in income-focused prospects by scanning the 216 dividend fortresses that prioritise higher yields alongside more resilient cash generation.
- Protect your downside by filtering for the 224 resilient stocks with low risk scores that emphasise balance sheet strength and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com