


Goosehead Insurance (GSHD) Stock May Still Look Pricey On Earnings
Goosehead Insurance has seen its share price under pressure in recent years, and that kind of slide naturally pushes investors to ask whether today's valuation still lines up with what the business is earning. With the stock changing hands around US$44.60 at the last close, the key issue is how that market tag compares with the insurer's profit power.
- Over the past 5 years the share price has fallen 73.2%, which puts the focus squarely on whether the current P/E can be supported by the underlying earnings profile.
- The company relies heavily on a franchise and agency-centric model that can support fee-based revenue and relatively low capital needs, which may result in a different earnings trajectory and risk profile compared with more balance sheet intensive insurers.
- Your read on Goosehead Insurance is one view; the desks covering it have another. See what analysts think Goosehead Insurance's shares could be worth.
The stock's next move may depend on whether Goosehead Insurance's current price is adequately backed by its earnings today and the profit stream investors expect it to produce over time.
If you are considering whether Goosehead Insurance's earnings justify its current P/E ratio, it may be helpful to compare this question with a broader set of 32 high quality undervalued stocks
Does Goosehead Insurance Look Pricey on Earnings?
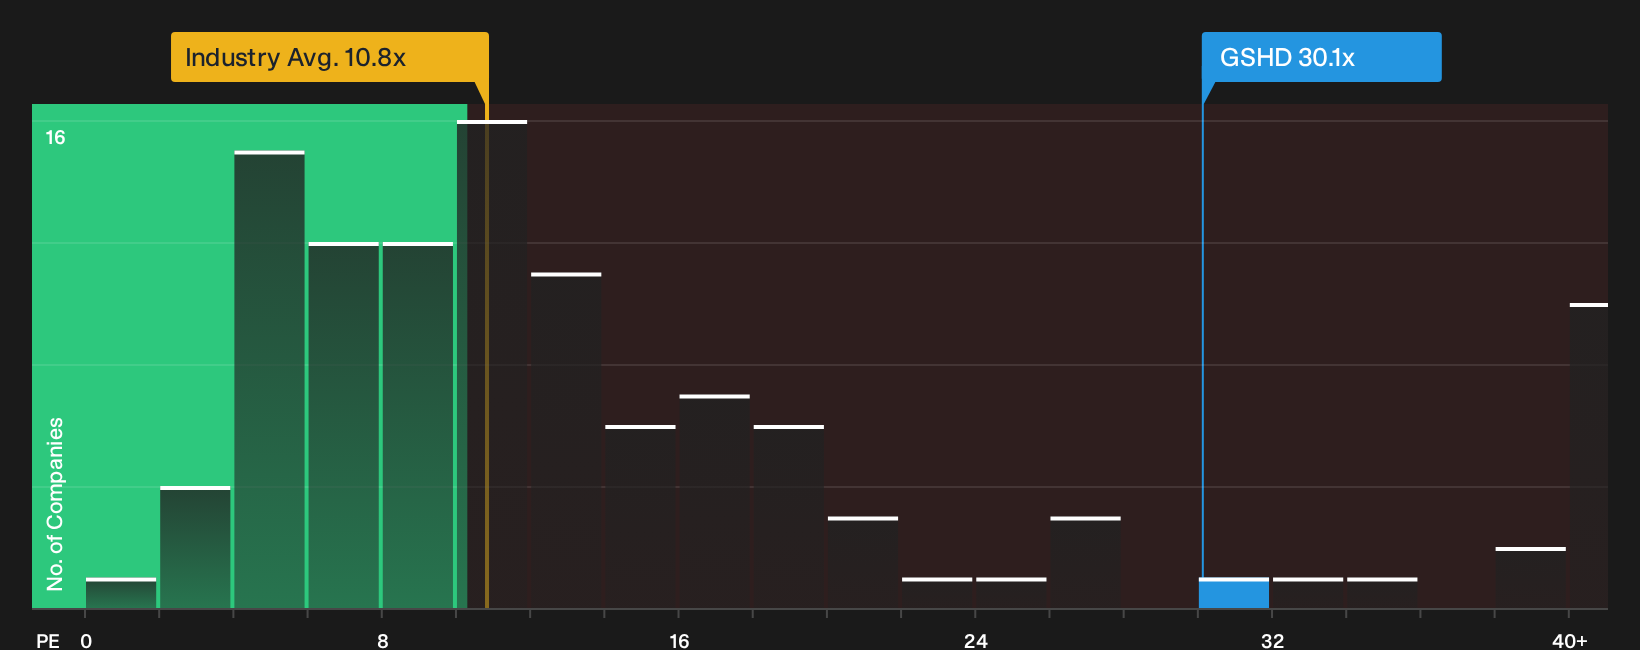
The P/E ratio suits Goosehead Insurance because earnings are a key focus for a fee-heavy franchise model. On this measure, the stock trades on roughly 30.1x earnings, which is much higher than the insurance sector average of about 10.8x. Compared with a peer group closer to 45.7x, the market is assigning Goosehead a lower tag than many direct comps but still a sizeable premium to the broader industry.
A tailored fair multiple, which blends the firm's growth profile, profitability and risk, suggests a lower P/E than the level the market is currently paying. That gap points to Goosehead Insurance screening as overvalued on this framework, even after the share price pressure already seen. For an investor, the key question is whether the franchise-led model and earnings path justify paying above that reference level or whether it makes more sense to wait for the multiple to move closer to the fundamentals. Explore the numbers behind Goosehead Insurance's P/E valuation.
The Goosehead Insurance Narrative: What Would Justify Today's Price?
Narratives on Goosehead Insurance pick up where the P/E puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than it does today. Each one links its number to a specific view on how Goosehead Insurance's scale, profitability and risk profile could evolve, giving you something you can revisit as fresh information arrives on Simply Wall St's Community page.
Community views on Goosehead Insurance are split between those who see more upside in the model and those who think much of that promise is already reflected.
Bull case: 54% undervalued
"Continued buildout of enterprise and embedded channels, which already supplied around one fifth of new business commissions in Q2 2026 and have access to millions of mortgage and home-services clients…"
Discover why this Narrative puts Goosehead Insurance at 54% undervalued.
Bear case: roughly fairly valued
"Although Goosehead Insurance is channeling considerable capital into Digital Agent 2.0 and AI tools such as the Lily voice assistant that currently automate a meaningful share of inbound calls, the plan to keep spending an additional US$25 million to US$35 million annually on these projects through at least 2027 risks outpacing incremental revenue gains…"
Explore why this Narrative puts Goosehead Insurance at roughly fairly valued.
One more Goosehead Insurance check that could change how you see the price tag
Price multiples tell you what the market pays today, but the real intrigue comes from where professional analysts think Goosehead Insurance might be a few years down the road. Explore where analysts expect Goosehead Insurance to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com