


South32 (ASX:S32) Is Getting Fresh Attention, What Is Behind It?
Improving earnings outlook puts South32 on investors’ radar
South32 (ASX:S32) has been drawing fresh attention after analysts lifted their consensus forecast for current year EPS, while the stock holds a strong Zacks Rank #2, pointing to a meaningfully improved earnings outlook.
Recent trading has been choppy, with the share price down over the past week and month. However, South32 still carries a 90 day share price return of 17.33% and a 1 year total shareholder return of 51.77%, which suggests momentum has been building over time as expectations around earnings shift.
Scan stocks riding similar earnings momentum by reviewing our curated list of 4 high quality undervalued stocks, which pairs upgraded outlooks with solid fundamentals.
South32’s sharp one year rebound and recent pullback can look like a classic sentiment swing, or a repricing that tracks improving earnings expectations. The valuation numbers now need to show which story fits.
Most Popular Narrative: 14% Overvalued
Against the last close of A$4.74, the leading South32 narrative pegs fair value nearer A$4.17, which frames the recent share price strength as somewhat ahead of current operating performance rather than obviously cheap.
At A$4.167 per share, South32 (ASX: S32) appears reasonably valued based on its current operating performance. South32 reports in US dollars and recorded first-half FY26 underlying earnings of US$435 million, or approximately US 9.7 cents per share. Annualising this result and using an exchange rate of US$0.70 per Australian dollar gives earnings of approximately A$0.277 per share and a P/E ratio of around 15 times.
See why 4 investors see South32 as 14% overvalued.
Result: Fair Value of A$4.17 (OVERVALUED)
Still, South32’s proposed aluminium asset sale and the capital intensity of Hermosa introduce execution and regulatory risks that could quickly shift today’s valuation story.
Find out about the key risks to this South32 narrative.
Another view on South32’s value
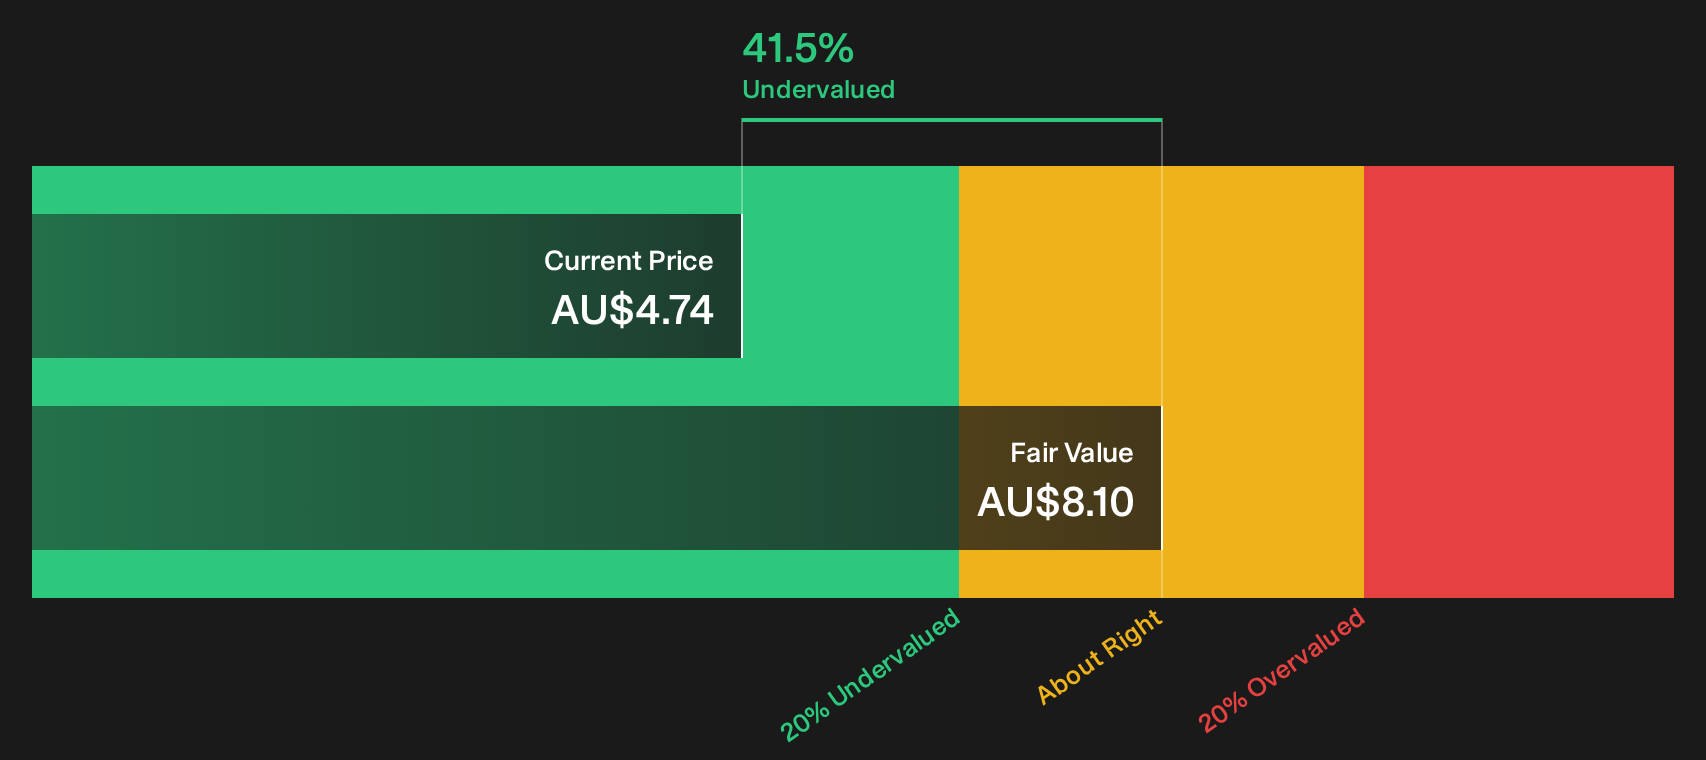
A different lens tells a very different story. Our DCF model puts South32’s future cash flow value near A$8.10 per share, compared with the current A$4.74 price. On that basis the stock screens as heavily undervalued, which leaves a simple question: Is the market missing something, or is the DCF too optimistic?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of caution and optimism around South32 feels familiar, move quickly to review the data and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond South32?
Do not stop with South32. Use the Simply Wall Street Screener to quickly surface fresh opportunities that match your style before the rest of the market focuses on them.
- Target stability first by checking companies that appear resilient in tough conditions through the 6 resilient stocks with low risk scores.
- Pursue steady income streams by reviewing businesses that feature stronger payouts in the 3 dividend fortresses.
- Hunt for tomorrow's quiet winners by scanning quality opportunities hiding in plain sight with the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com