


Energy Transfer (ET) Stock May Be Undervalued On Its Vaquero Midstream Deal
Energy Transfer has delivered a strong 5 year run, and the latest corporate moves are adding fresh attention to the stock. With that backdrop, the central question is whether today's market price lines up with what the business is earning.
- Over the past 5 years, Energy Transfer has returned 210.6%, which puts more pressure on the earnings story to support the current valuation.
- The planned US$2.63b acquisition of Vaquero Midstream may support future cash generation by adding more natural gas gathering and processing capacity, but it also increases the capital base that those earnings need to cover.
- Your read on Energy Transfer is one view; the desks covering it have another. See what analysts think Energy Transfer's shares could be worth.
The stock's next move may depend on whether Energy Transfer's earnings profile is strong enough to justify where the shares trade today.
To see how Energy Transfer compares on this theme, you can line it up against other 43 power grid technology and infrastructure stocks
Is Energy Transfer a Bargain on Earnings?
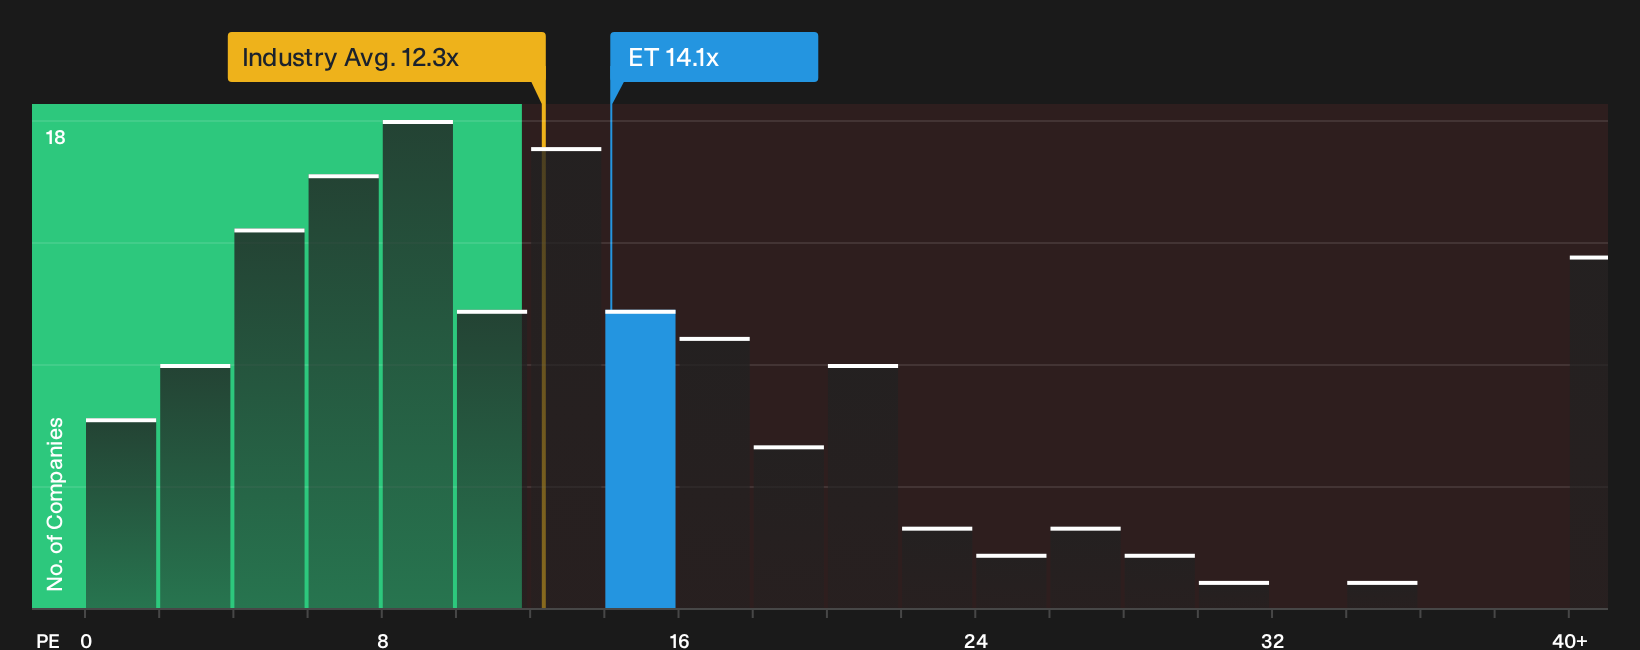
The P/E ratio fits Energy Transfer because earnings still anchor how investors tend to look at mature pipeline operators. On this measure, the stock trades at about 14.1x earnings, which is below the oil and gas industry average of roughly 12.3x but also below the broader peer group on about 18.4x. That combination suggests the market gives Energy Transfer a modest premium to the sector as a whole but not as rich a tag as some listed comparables.
Against a more tailored fair P/E that reflects Energy Transfer's own growth profile and risk mix, the current 14.1x screens on the undervalued side. Because the Vaquero Midstream deal adds scale and long term contracts, the fact that the multiple still comes in under this model based yardstick points to a market price that does not fully reflect those expansion plans. Explore the numbers behind Energy Transfer's P/E valuation.
The Energy Transfer Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Energy Transfer valuation puzzle leaves off and spell out which earnings, margin and growth paths would need to play out for the current price to look high or low. Each scenario links a fair value estimate to a clear view of Energy Transfer's possible catalysts and key risks, so over time you can see which storyline is getting closer to reality on the Community page.
One of the top community narratives on Energy Transfer: 16% undervalued
"Recent long term customer commitments on multi billion dollar projects are now supported by more than 6 Bcf/d of contracted pipeline capacity with demand pull customers…"
Discover why this Narrative puts Energy Transfer at 16% undervalued.
One more Energy Transfer check that belongs beside the price tag
Before closing the file on Energy Transfer, it is worth knowing that Simply Wall St's broader review has flagged specific issues that sit outside the valuation story and deserve a closer look. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com