


Premium Brands Holdings (TSX:PBH) Buyback Puts Its Undervalued Narrative Back In Focus
Premium Brands Holdings (TSX:PBH) has unveiled a share repurchase plan that allows it to buy back up to 1,000,000 shares over 12 months, with all reacquired stock set for cancellation.
The share repurchase plan comes after a weak run for Premium Brands Holdings, with the share price down 30.28% year to date and the 1 year total shareholder return declining 23.53%. The stock has edged up over the past week and on the day, which hints that sentiment may be starting to turn as management signals confidence in the business through buybacks.
Scan how Premium Brands Holdings compares with other consumer-focused businesses by reviewing our hand-picked 7 high quality undervalued stocks that also pair established operations with potential value gaps.
Bulls see Premium Brands Holdings cancelling shares at depressed levels and point to growing revenue and net income. Bears focus on weak multi year returns. Which side does the current valuation lean toward?
Most Popular Narrative: 38% Undervalued
Premium Brands Holdings is trading at CA$71.43 against a widely followed narrative fair value of about CA$115.67. This frames the buyback alongside a thesis built on future earnings power and cash generation under a 6.44% discount rate.
Investments in expanded distribution capacity (including $1.7 billion of recent sales capacity and further "slack" in existing plants) position the company to capitalize on both industry and consumer tailwinds, translating into scalable revenue growth and normalized higher earnings as capacity utilization improves. Advancement of efficiency initiatives (automation, supply chain optimization, and pass-through pricing) in response to past input cost volatility is expected to restore normalized net margins and earnings, especially as input costs (like chicken) begin to ease, and the company realizes efficiencies from recent capital investments.
See why 17 investors see Premium Brands Holdings as 38% undervalued.
Result: Fair Value of CA$115.67 (UNDERVALUED)
Still, the Premium Brands Holdings story can be knocked off course if execution around new facilities slips, or if higher input costs squeeze already thin net margins.
Find out about the key risks to this Premium Brands Holdings narrative.
Another View: Premium Brands Holdings On Earnings Multiples
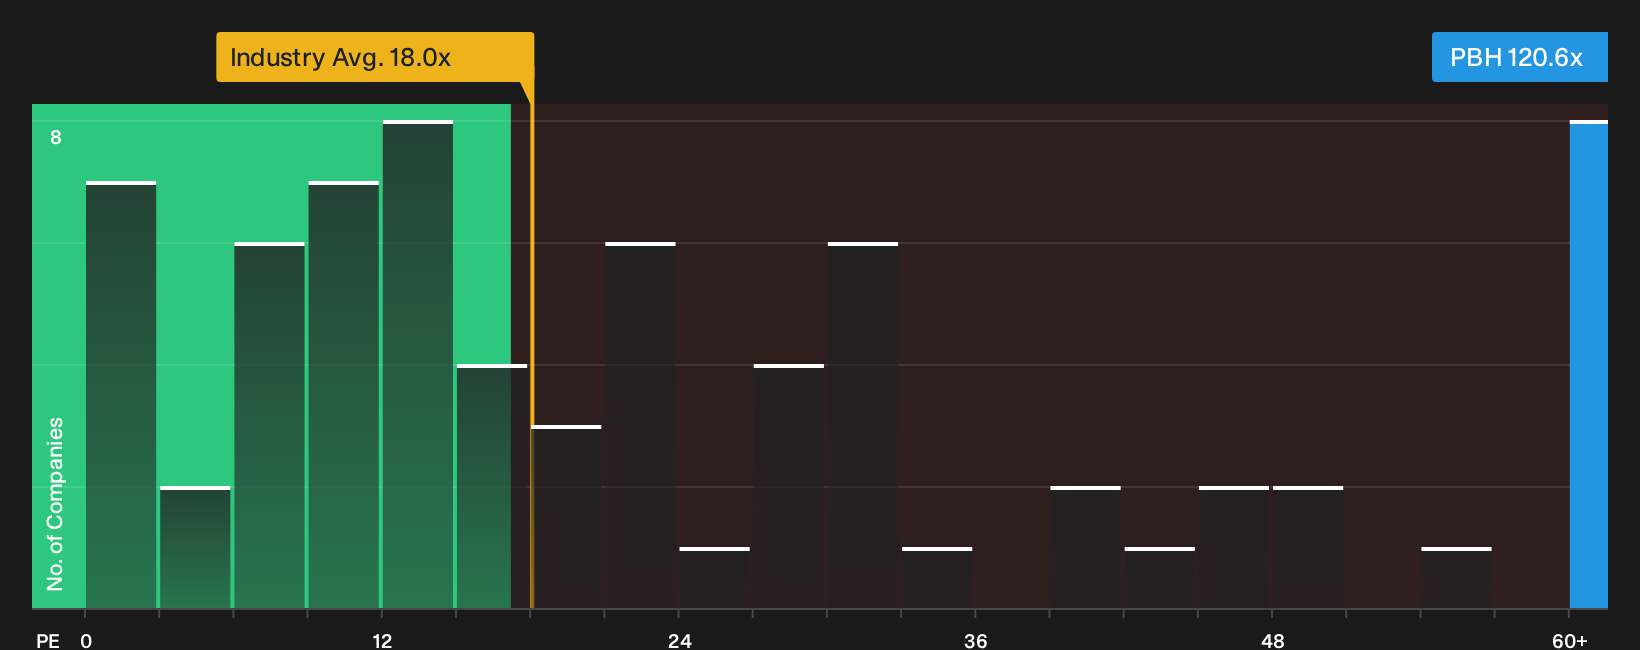
That 38% undervalued story runs into a very different picture once earnings multiples are brought into focus. Premium Brands Holdings trades on a P/E of 120.6x, compared with 21.5x for peers and a fair ratio of 59.7x. That gap points to clear valuation risk if profits do not ramp as expected.
For a closer look at how this pricing stacks up against earnings power, start with the detailed multiple breakdown and where the fair ratio suggests the market could drift over time. Then weigh how comfortable you are with that premium before leaning on the buyback signal See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this Premium Brands Holdings story feels mixed to you, that is exactly the point. Move quickly and weigh the full picture across 3 key rewards and 5 important warning signs.
Looking for more Premium Brands Holdings style investment ideas?
Premium Brands Holdings may sit on your watchlist already, but you do not want your next opportunity to slip past while attention stays on a single ticker.
- Spot potential mispricings early and scan a curated 7 high quality undervalued stocks that combines strong fundamentals with price tags that may not fully reflect them.
- Build a steadier portfolio and focus on income resilience with a hand-picked 3 dividend fortresses that screens for yields supported by underlying business strength.
- Sleep easier through market swings and sort for resilience first using a targeted 8 resilient stocks with low risk scores that emphasizes balance sheet quality and lower volatility profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com