


Starbucks (SBUX) Rejects Takeover Rumors And Refocuses Investors On Turnaround
- Starbucks (NasdaqGS:SBUX) publicly rejected rumors that it plans to acquire Chipotle, ending weeks of merger speculation.
- The company issued its denial after media reports suggested informal takeover discussions that could reshape the US restaurant sector.
- Starbucks indicated that its focus remains on executing its own turnaround efforts as an independent coffee chain.
- Starbucks’ clear rejection of a Chipotle deal is a fresh data point to weigh against the rest of our findings. We have also flagged 2 other big wins for Starbucks.
Starbucks is far from the only large consumer brand exposed to these consolidation themes. It is worth scanning a wider group of resilient, lower-volatility candidates through 32 resilient stocks with low risk scores.
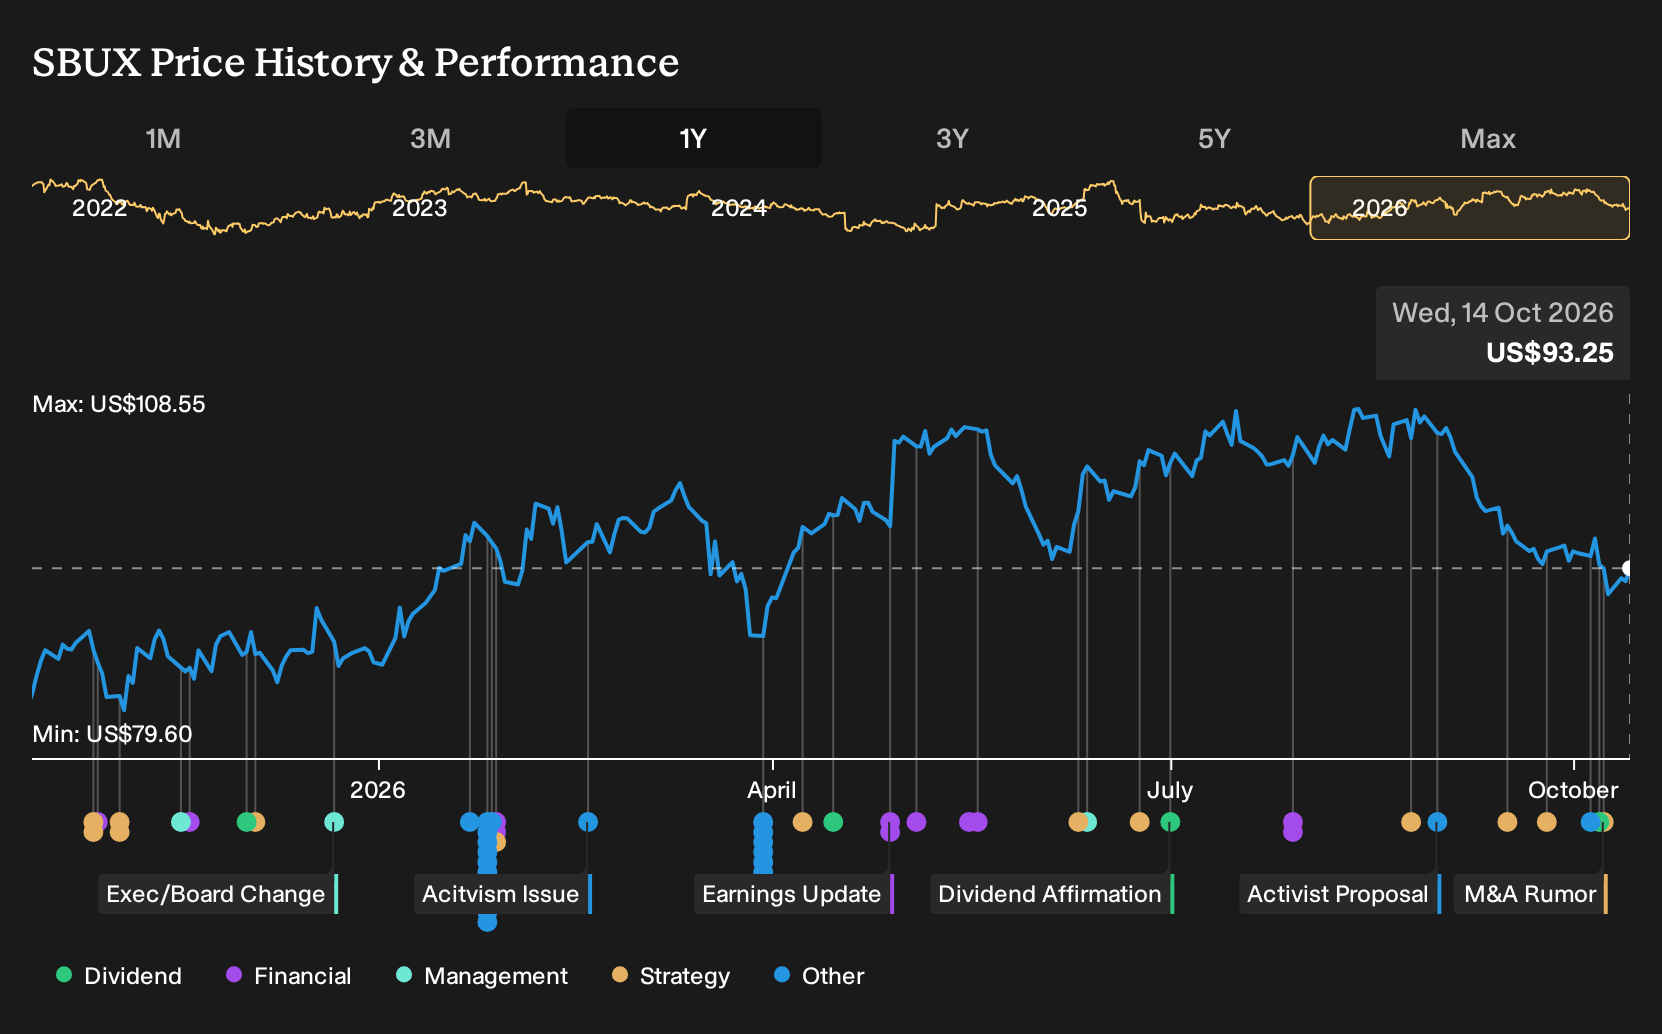
Starbucks operates as a global roaster, marketer, and retailer of coffee, which gives the business a very different product focus and customer experience compared with a fast casual chain like Chipotle. With a market cap of $104.9b, it sits among the larger US hospitality groups where takeover rumors often attract outsized attention.
See which insiders are buying and selling Starbucks following this latest news.
Starbucks backs its own playbook rather than buying growth
The Starbucks Narrative hinges on the idea that the real upside comes from squeezing more earnings out of the existing coffee platform, not from big-ticket acquisitions. Rejecting a Chipotle deal keeps the focus on whether the Back to Starbucks plan and capital-light moves can do the heavy lifting.
"The main requirement for success is that Starbucks translates its $2 billion cost-savings and labor investment agenda into higher and more stable operating margins..."
See how the full story points towards a $112 fair value for Starbucks.
This denial supports the view that management is committed to margin repair and capital-light international partnerships rather than stretching the balance sheet for scale. For holders who buy into that thesis, keeping cash and management bandwidth tied to Back to Starbucks, China joint ventures and North America store uplift is directionally consistent with the existing story.
On the bear side, the episode highlights how quickly sentiment can swing when investors suspect a large acquisition, especially for a business already flagged for high debt and negative equity. That reinforces concerns that the turnaround still depends on execution in labor, legal and store-remodel programs without the distraction of deal-making.
Events like this only become useful for you when they are weighed against a clear Starbucks Narrative that links headlines to margins, cash flows and balance-sheet risk.
Add Starbucks to your Watchlist and get alerts as these catalysts play out.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com