


Fortis (TSX:FTS) Draws Interest On Regulated Growth, Is The Stock Fully Priced?
Investor attention around Fortis (TSX:FTS) has sharpened as regulated asset growth plans, capital spending needs, and electricity demand trends intersect with questions around financing conditions and long term earnings resilience.
Recent trading has leaned positive for Fortis, with the share price at CA$77.94 and short term moves such as the 1 day share price return of 1.52% and 7 day return of 3.01% suggesting buyers are responding to its regulated growth plans and financing debates. At the same time, a 90 day share price return that is down 5.45% contrasts with a 1 year total shareholder return of 11.70% and a 5 year total shareholder return of 70.01%, which points to stronger longer run reward for investors who stayed through recent swings.
Scan regulated utility peers that share Fortis’s focus on capital investment, earnings resilience, and balance sheet strength by starting with our curated list of 8 resilient stocks with low risk scores.
Fortis looks like a sturdy regulated utility, and the recent share price rebound reinforces that story. The harder part is simple: at about CA$77.94, are you paying a fair price for that stability today?
Most Popular Narrative: 3.7% Undervalued
With Fortis last closing at CA$77.94 against a narrative fair value of CA$80.96, the story centers on a regulated utility priced only slightly below what that widely followed view considers reasonable, with the gap explained by how it invests and recoups capital over time.
Rapid growth in large data center and industrial load at ITC and Tucson Electric Power, including an approved 300 MW data center contract and negotiations for up to a further 1,000 MW, is expected to require additional transmission and generation projects that expand Fortis’s regulated rate base and support future revenue and earnings.
See why 90 investors see Fortis as 4% undervalued.
The most followed narrative applies a 6.46% discount rate to Fortis and leans heavily on that CAD 28.8b regulated capital plan. It connects a growing rate base, forecast revenue growth of about 6.2% a year and projected earnings of CA$2.3b by 2029 into that fair value of CA$80.96.
Investors weighing that view against the current CA$77.94 price also have to consider the risks flagged in the same storyline. Those include regulatory lag at UNS Energy, the effect of asset sales on earnings per share, and a funding profile where interest costs and external borrowing could bite into returns if conditions tighten.
Result: Fair Value of CA$80.96 (UNDERVALUED)
Still, the Fortis narrative leans on smooth execution, and regulatory lag at UNS Energy or higher borrowing costs on that CAD 28.8b plan could quickly test it.
Find out about the key risks to this Fortis narrative.
Another View: Fortis Through The P/E Lens
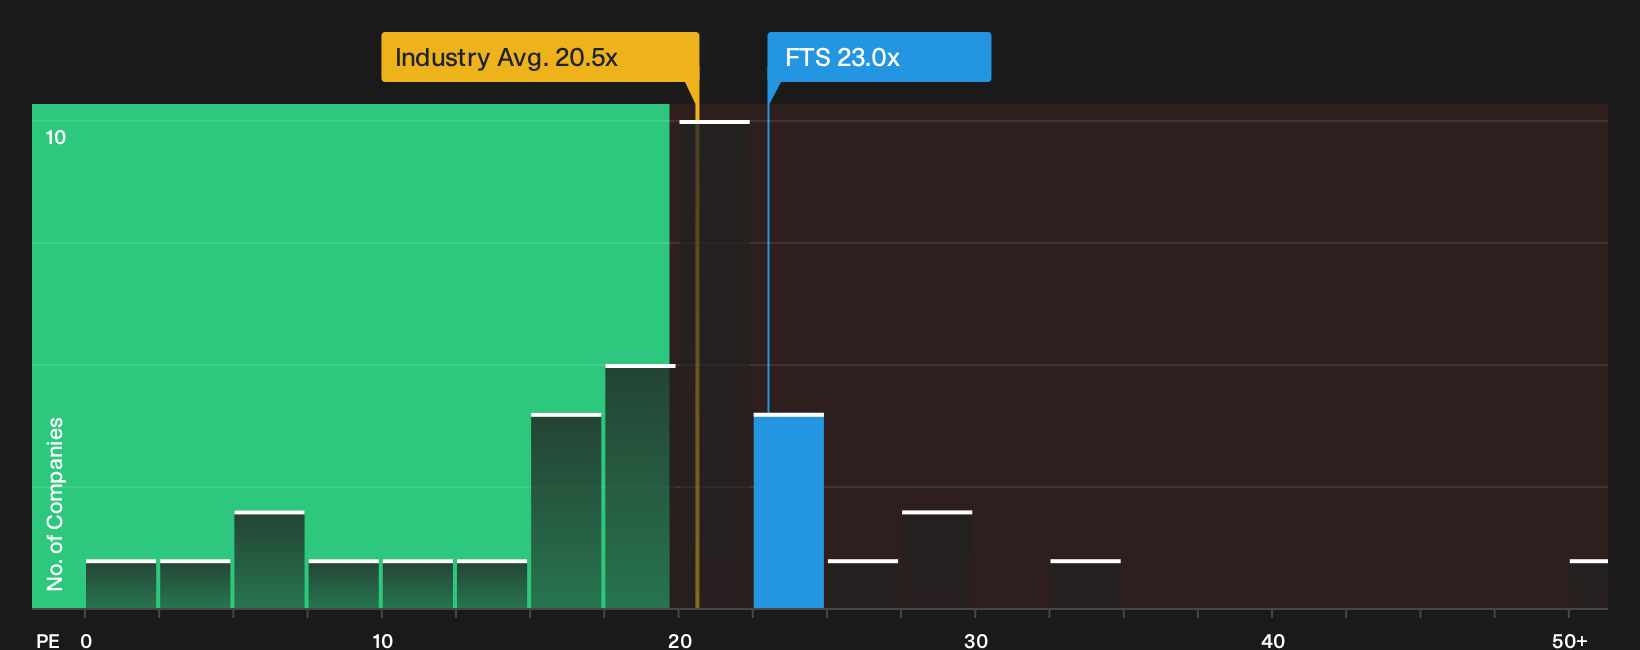
That 3.7% undervalued fair value of CA$80.96 rests on the consensus narrative. Yet Fortis at a P/E of 23x trades richer than both Canadian peers at 21.2x and the broader North American electric utilities group at 20.5x, even though its fair ratio sits higher at 29.8x. Is this a cushion, or are you paying up for comfort?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Fortis story are exactly why you should check the data for yourself and decide how comfortable you are with both sides. To see the balance between potential upside and the issues investors are watching, start with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Fortis?
You have seen how Fortis stacks up. Now give yourself options. Fresh ideas can sharpen your judgement on whether its current pricing really suits your goals.
- Target resilience first and scan a curated set of companies with robust financial footing through the list of solid balance sheet and fundamentals (8 results).
- Hunt for value opportunities by reviewing the 7 high quality undervalued stocks that pair quality fundamentals with what the data flags as attractive pricing.
- Prioritise steady income potential and compare yields and payout profiles using the 3 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com