


Volution Group (LSE:FAN) Could Be 15% Undervalued As Earnings And Dividend Rise
Volution Group (LSE:FAN) has put fresh numbers on the table, reporting full year sales of £484.8 million and net income of £62.5 million, alongside an 18.5% increase in total dividend.
The fresh earnings, dividend uplift and board update have arrived after a year where Volution Group’s share price has inched up, with a 30 day share price return of 2.9% and a 3 year total shareholder return of 93.5% hinting that long term momentum remains intact despite a slightly negative 1 year total shareholder return.
Scan for opportunities that may have similar earnings and dividend momentum to Volution Group by focusing on our curated list of 8 high quality undervalued stocks.
Recent gains and a softer 1 year return leave Volution Group at an interesting crossroads. Is the current share price mostly echoing better fundamentals, or does it already bake in a shift in sentiment that affects valuation?
Most Popular Narrative: 15% Undervalued
On the most followed view of Volution Group, a fair value of £7.54 sits above the last close of £6.43, which raises a clear question about what needs to go right to close that gap.
The acquisition of Fantech, which has consolidated Volution's leadership position in Australia and New Zealand, provides opportunities for cross-selling, new product introductions, and procurement efficiencies, with the potential to affect future revenue and net margin.
The focus on sustainability, including initiatives such as increasing recycled plastics usage and setting stringent targets for low carbon revenue, aligns with growing environmental regulations and may influence future revenues if customer demand for sustainable products increases.
Find out how 3 investors see Volution Group as 15% undervalued.
Result: Fair Value of £7.54 (UNDERVALUED)
Still, Fantech integration hiccups or prolonged weakness in New Zealand and the Nordics could quickly challenge the upbeat Volution Group narrative that investors are leaning on.
Find out about the key risks to this Volution Group narrative.
Another View: Volution Group Through A Cash Flow Lens
The first story around Volution Group leans on analyst targets and earnings expectations. A different take comes from our DCF model, which points to a future cash flow value of £5.71 against the current £6.43 share price. On that basis, the stock screens as overvalued rather than 15% undervalued. Which yardstick do you trust more for your own thesis?
Look into how the SWS DCF model arrives at its fair value.
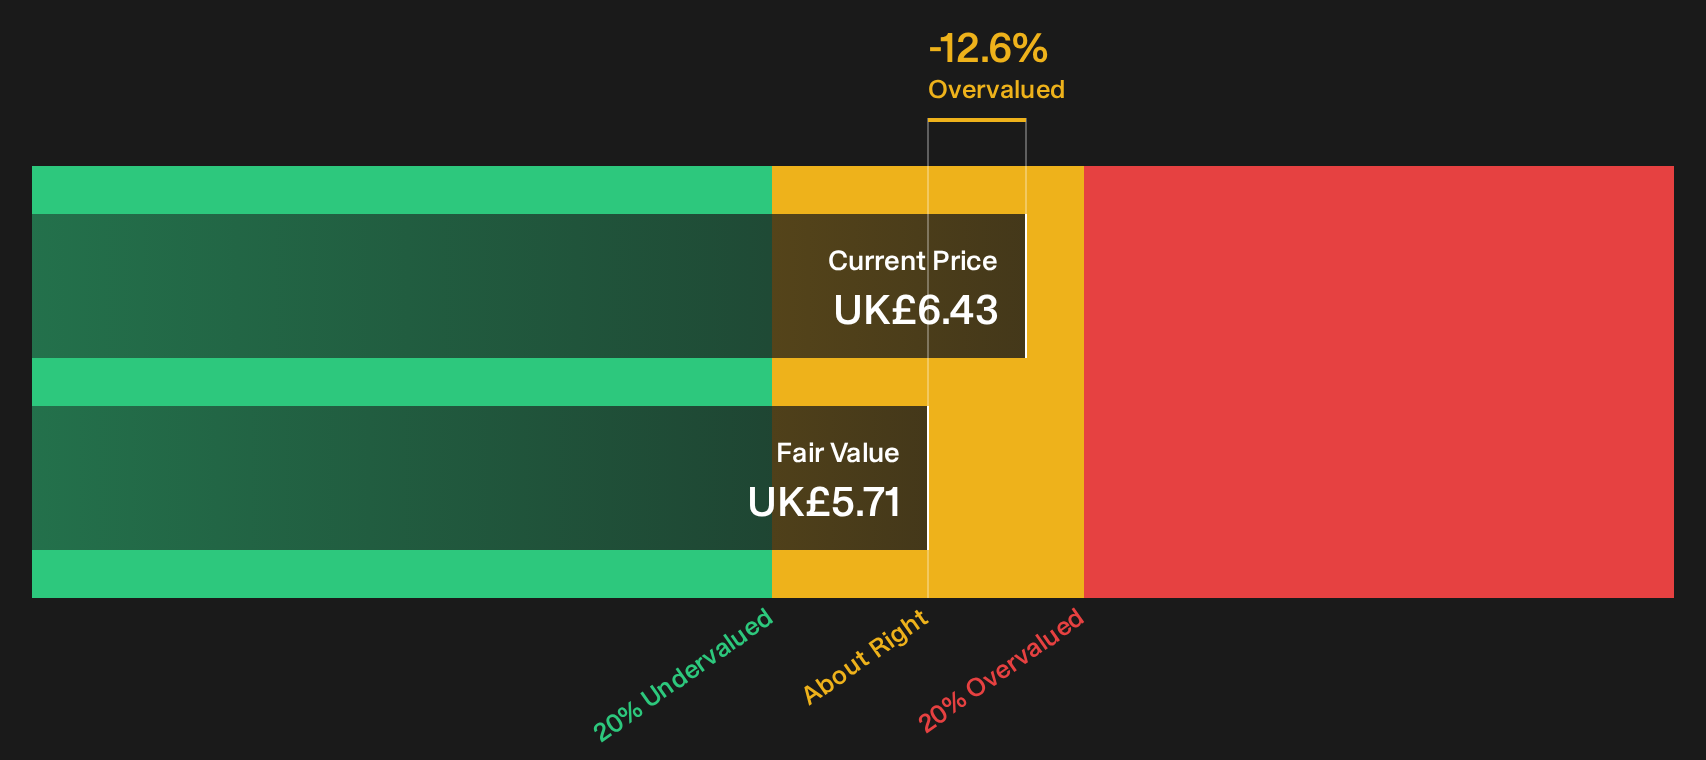
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Volution Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 8 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Volution Group's valuation story. If the numbers leave you on the fence, act quickly and review both sides of the investment case through 4 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Volution Group?
If Volution Group has sharpened your focus on quality, do not stop here. Broader idea hunting with targeted tools can keep your watchlist ahead of the crowd.
- Target potential high return outliers by checking the 13 elite penny stocks with strong financials that already show stronger balance sheets than many expect from lower priced shares.
- Focus on resilience first and filter for businesses that prioritise capital strength through our list of solid balance sheet and fundamentals (9 results), before shortlisting anything for deeper research.
- Hunt for tomorrow's leaders early by scanning the 5 high quality undiscovered gems that pair healthier fundamentals with relatively low market attention right now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com