


Daisan Co., Ltd. (TSE:4750) Pays A JP¥11.00 Dividend In Just Three Days
Some investors rely on dividends for growing their wealth, and if you're one of those dividend sleuths, you might be intrigued to know that Daisan Co., Ltd. (TSE:4750) is about to go ex-dividend in just 3 days. The ex-dividend date is usually set to be two business days before the record date, which is the cut-off date on which you must be present on the company's books as a shareholder in order to receive the dividend. It is important to be aware of the ex-dividend date because any trade on the stock needs to have been settled on or before the record date. Accordingly, Daisan investors that purchase the stock on or after the 19th of October will not receive the dividend, which will be paid on the 28th of December.
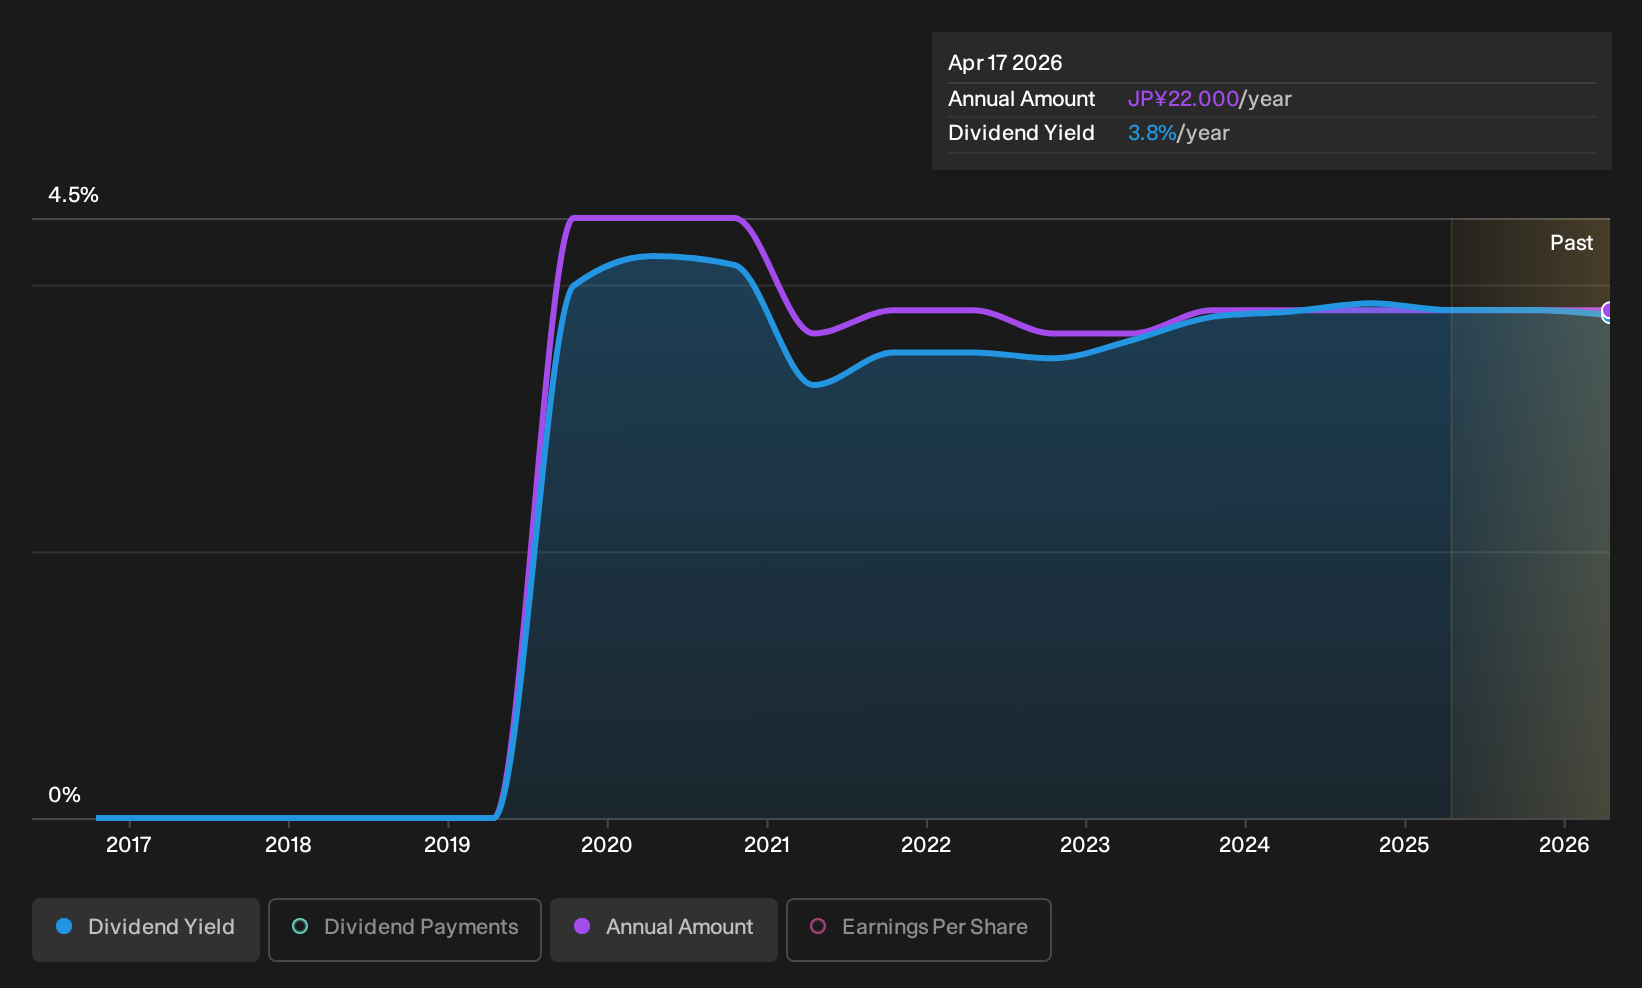
The company's next dividend payment will be JP¥11.00 per share, on the back of last year when the company paid a total of JP¥22.00 to shareholders. Based on the last year's worth of payments, Daisan has a trailing yield of 4.0% on the current stock price of JP¥552.00. If you buy this business for its dividend, you should have an idea of whether Daisan's dividend is reliable and sustainable. As a result, readers should always check whether Daisan has been able to grow its dividends, or if the dividend might be cut.
Dividends are usually paid out of company profits, so if a company pays out more than it earned then its dividend is usually at greater risk of being cut. Daisan paid out a disturbingly high 220% of its profit as dividends last year, which makes us concerned there's something we don't fully understand in the business. Yet cash flows are even more important than profits for assessing a dividend, so we need to see if the company generated enough cash to pay its distribution. Thankfully its dividend payments took up just 30% of the free cash flow it generated, which is a comfortable payout ratio.
It's good to see that while Daisan's dividends were not covered by profits, at least they are affordable from a cash perspective. If executives were to continue paying more in dividends than the company reported in profits, we'd view this as a warning sign. Very few companies are able to sustainably pay dividends larger than their reported earnings.
See our latest analysis for Daisan
Click here to see how much of its profit Daisan paid out over the last 12 months.
Have Earnings And Dividends Been Growing?
Businesses with strong growth prospects usually make the best dividend payers, because it's easier to grow dividends when earnings per share are improving. If earnings fall far enough, the company could be forced to cut its dividend. Fortunately for readers, Daisan's earnings per share have been growing at 13% a year for the past five years.
Many investors will assess a company's dividend performance by evaluating how much the dividend payments have changed over time. Daisan has seen its dividend decline 2.4% per annum on average over the past seven years, which is not great to see. It's unusual to see earnings per share increasing at the same time as dividends per share have been in decline. We'd hope it's because the company is reinvesting heavily in its business, but it could also suggest business is lumpy.
Final Takeaway
Is Daisan an attractive dividend stock, or better left on the shelf? It's good to see earnings per share growing and low cashflow payout ratio, although we're uncomfortable with Daisan's paying out such a high percentage of its profit. It might be worth researching if the company is reinvesting in growth projects that could grow earnings and dividends in the future, but for now we're not all that optimistic on its dividend prospects.
So while Daisan looks good from a dividend perspective, it's always worthwhile being up to date with the risks involved in this stock. For example - Daisan has 3 warning signs we think you should be aware of.
If you're in the market for strong dividend payers, we recommend checking our selection of top dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.