


This Bank Stock Just Raised Its Dividend by 20%
The third-quarter earnings season is starting, but bank stocks remain under pressure. Rising Treasury yields can reduce the value of banks’ bond holdings, narrow lending margins, and slow loan demand, even though higher rates can also help banks earn more. The State Street Financial Select Sector SPDR ETF (XLF) is up just slightly year-to-date (YTD) but up about 5% over the past 52 weeks.
Northpointe Bancshares (NPB), meanwhile, has raised its dividend shortly after its first anniversary as a public company. On Oct. 6, Northpointe Bancshares’ board declared a quarterly payment of $0.03 per common share, a 20% increase from $0.025.
The dividend is payable on Nov. 4 to shareholders of record on Oct. 15, bringing the annualized payout to $0.12 per share. The bank only began paying dividends after its IPO.
What gave Northpointe’s board the confidence to raise the payout just weeks before its third-quarter earnings report? Let’s find out.
The Earnings Behind the Higher Payout
Northpointe Bancshares, which primarily operates through its subsidiary Northpointe Bank, offers home loans nationwide, finances mortgage lenders, and provides retail banking services. Its shares are down 4.6% over the past 52 weeks and 5.4% YTD.
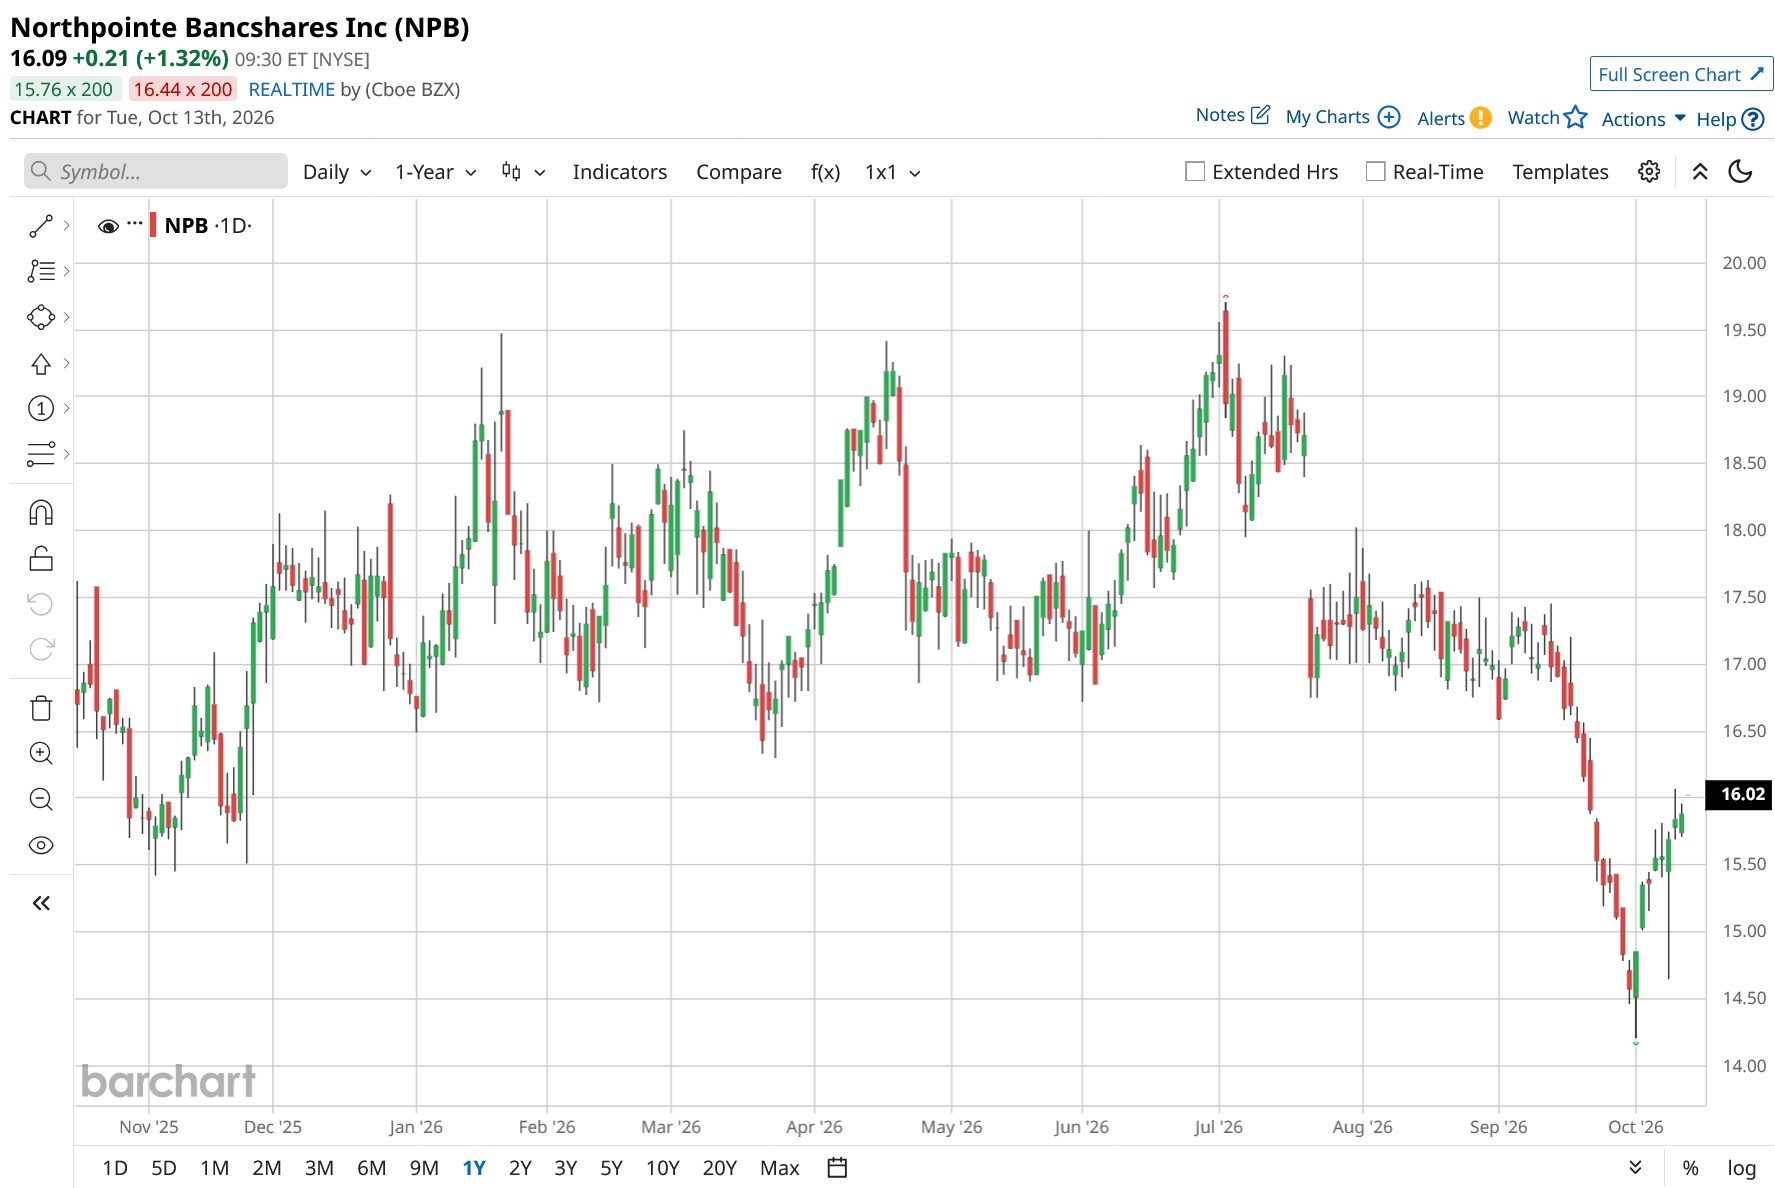
NPD stock trades at 6.33x expected earnings, compared with the sector’s 10.83x. That makes it cheaper than the sector, but not automatically a bargain.
The higher dividend adds to its appeal. Northpointe Bancshares raised its quarterly payment 20%, from $0.025 to $0.03, payable Nov. 4 to shareholders of record on Oct. 15. Annualized payments rise from $0.10 to $0.12, taking the yield from 0.63% to about 0.76% at current prices. The bank has one year of dividend increases, with a forward payout ratio of 3.83% before the latest raise.
Second-quarter earnings were higher than a year ago but slipped from the previous quarter. Net income was $21.3 million, or $0.60 per share, compared with $18 million and $0.51 a year earlier and $21.7 million and $0.62 in Q1. Net interest income rose to $42.4 million from $41.3 million in Q1 and $36.5 million a year earlier. That increase came despite the net interest margin falling to 2.33% from 2.42% and 2.44%, respectively. A larger lending business helped offset the narrower margin.
Costs, however, rose as other income fell. Non-interest income dropped to $21.9 million from $22.1 million in Q1 and $22.4 million a year earlier. Expenses increased to $35.2 million from $34.4 million and $31.7 million, respectively.
Assets reached $7.53 billion, up $134.1 million from Q1 and $1.10 billion year-over-year (YoY). Loans held for investment grew to $6.48 billion, rising $69 million from Q1 and 18% from a year earlier. Deposits reached $5.23 billion, up $231.9 million from Q1, with a 19% annualized growth rate and 17% YoY. Borrowings fell $119 million from Q1 to $1.51 billion but remained $237.6 million above last year. Tangible book value per share rose to $16.94 from $16.35 in Q1 and $14.67 a year earlier.
Where Northpointe’s Next Growth Could Come From
Northpointe’s Mortgage Purchase Program funds participating mortgage lenders, helping the bank grow beyond branches and local business loans. In Q2, program balances rose $77.3 million from the previous quarter and 36% YoY. Total loans funded through the program increased 42% from a year earlier. More lending can bring in additional income to support dividend payments.
First Northwest Bancorp (FNWB) is one of those partners. Its participation in Northpointe Bancshares’ program grew $2.7 million during the quarter, taking its balance from $42 million to about $44.6 million. Increasing business with existing partners or adding new ones could help Northpointe Bancshares grow its lending without buying another bank or taking on the costs and risks of combining businesses.
Northpointe also has a nationwide home loan business. In May, it reported that 27 of its loan originators made the 2026 Scotsman Guide Top Originators rankings. If housing activity picks up, that lending network could help the bank make more loans and earn more from selling and servicing them. Those earnings still depend partly on mortgage rates and demand for home loans.
What Analysts Expect From Northpointe
Northpointe Bancshares reports earnings on Oct. 20, after the market closes. Analysts expect September-quarter earnings of $0.60 per share, up 5.26% from $0.57 a year earlier. For fiscal 2026, they forecast $2.44 per share, a 15.64% increase from $2.11 in 2025.
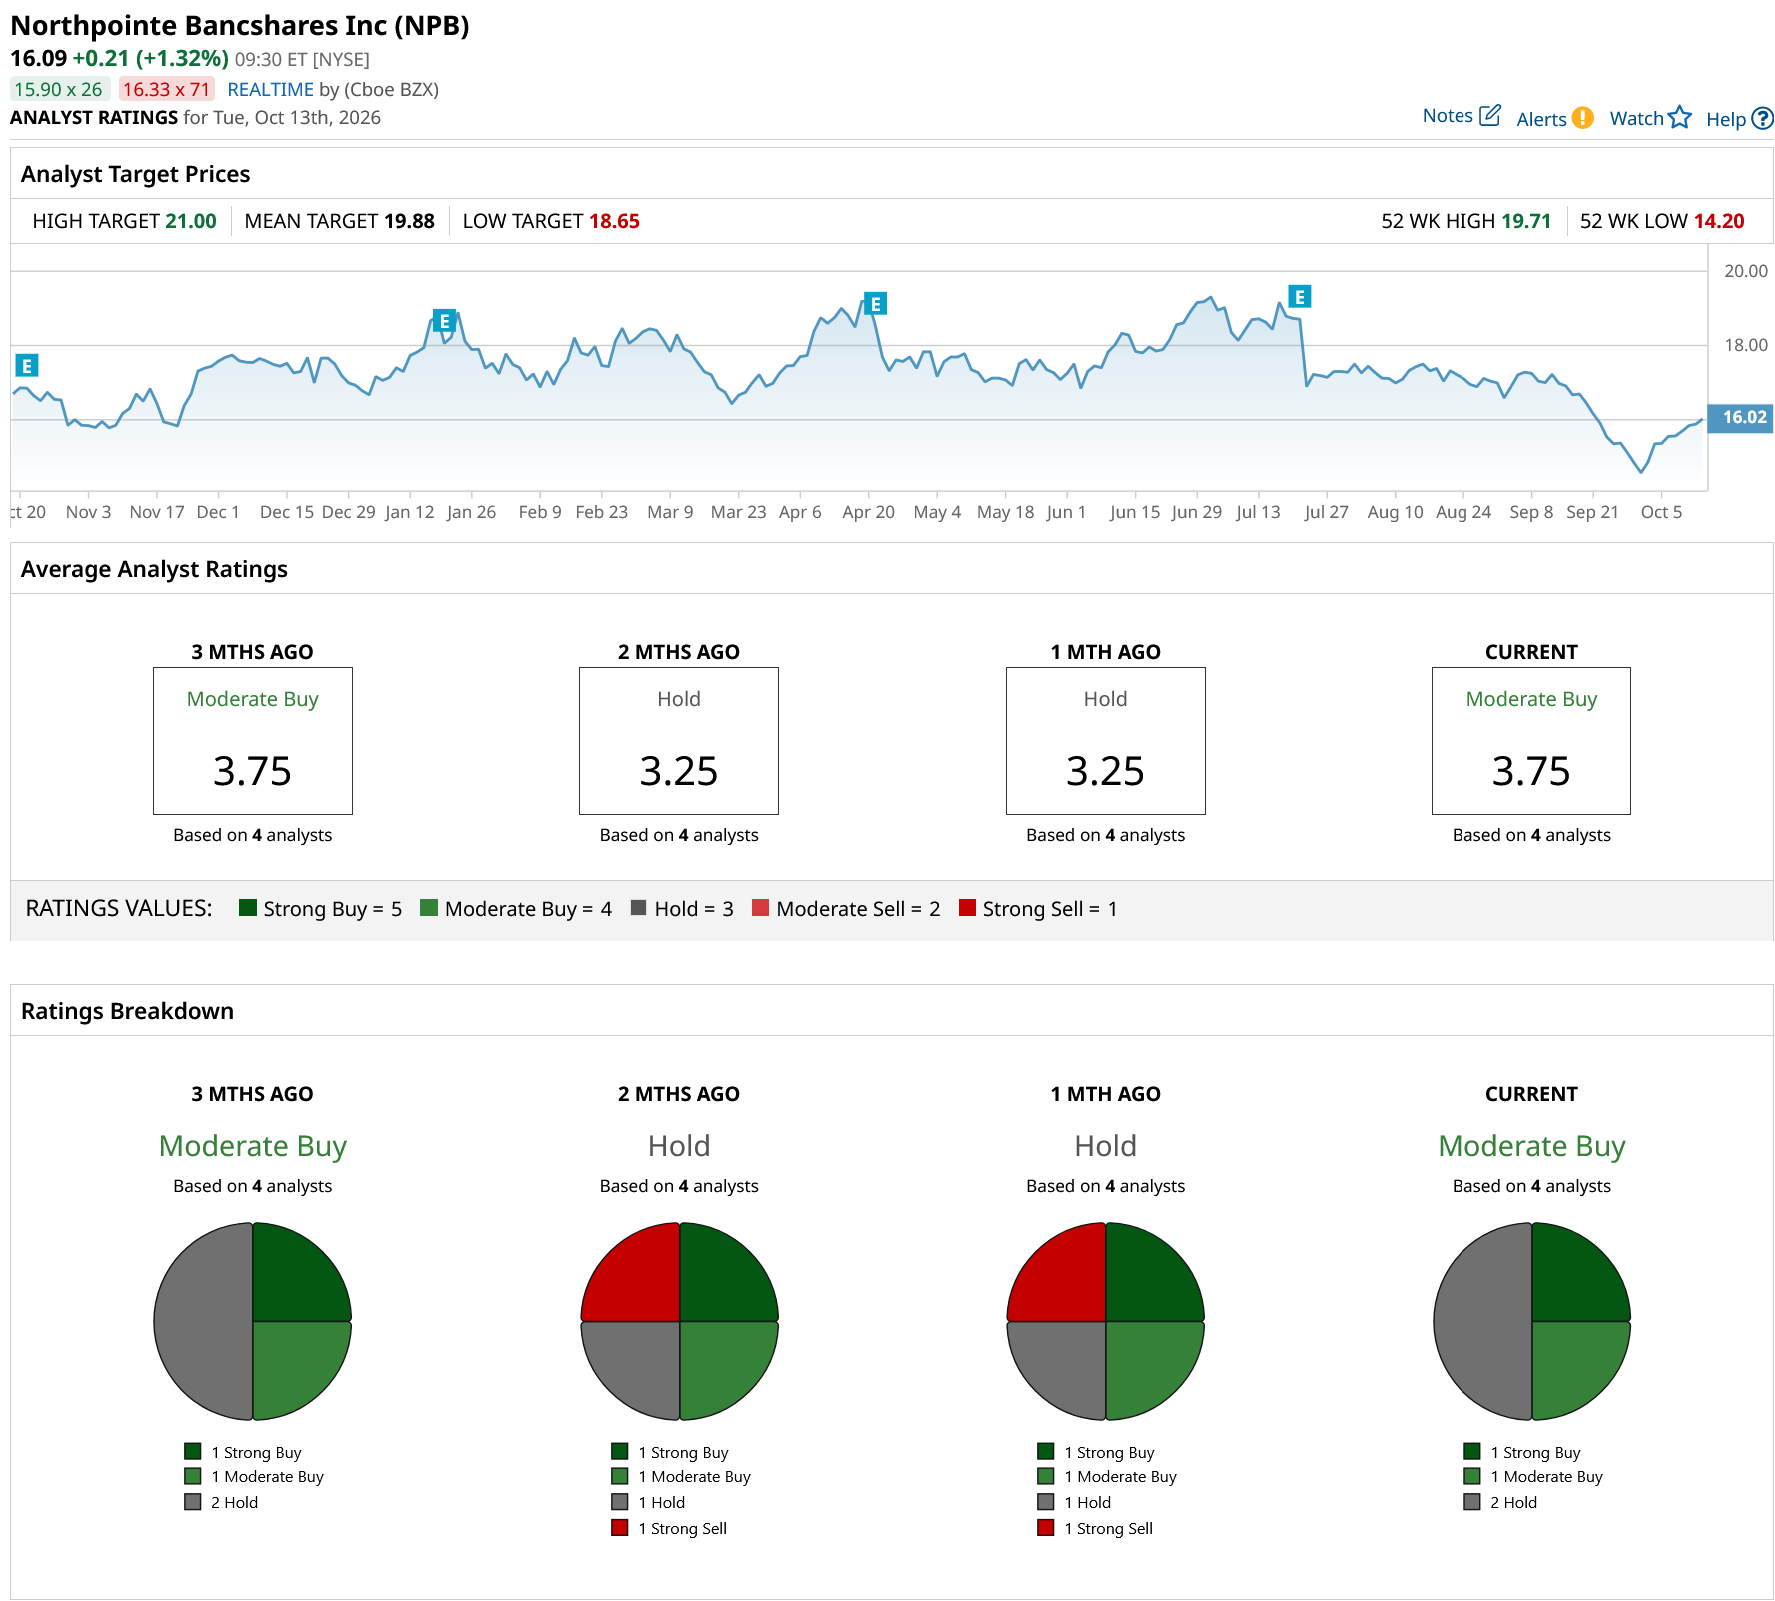
Analysts remain positive, though two have lowered their price targets. On Oct. 9, Piper Sandler analyst Crispin Love kept his “Overweight” rating but cut his target from $21.50 to $20. Keefe, Bruyette & Woods analyst Damon DelMonte kept his “Outperform” rating on July 23 while lowering his target from $22 to $21 after Northpointe’s Q2 report.
The four analysts surveyed give NPB stock a consensus “Moderate Buy” rating. Their average price target of $19.88 suggests 24% upside from the current share price levels.
Conclusion
Northpointe’s earnings growth and expanding lending business help explain why the board felt comfortable raising its dividend by 20%. But a yield of roughly 0.76% makes this a growth and valuation story more than a high-income opportunity. The discounted earnings multiple and positive analyst outlook suggest shares have room to move higher if earnings meet expectations. A gradual advance looks more plausible than a sharp rally, especially with margins narrowing and expenses rising. The Oct. 20 earnings report will help show whether loan and deposit growth can keep offsetting those pressures and support further dividend increases.
On the date of publication, Ebube Jones did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.