


Is Oxford Nanopore Technologies (LSE:ONT) Fully Valued As India Genomics Expansion Lifts Its Story?
Oxford Nanopore Technologies (LSE:ONT) is back in the spotlight after the inauguration of the India Genomics Centre of Excellence with UK partners, putting fresh attention on how this collaboration might influence long term commercial prospects.
The share price tells a mixed story. Oxford Nanopore Technologies has fallen 1.1% over the past day and 5.4% across the week, yet it has delivered a 79.9% 3 month share price return and a 50.5% 1 year total shareholder return. This suggests momentum has been rebuilding as investors reassess growth potential and valuation risk around moves like the India Genomics Centre of Excellence.
Spot fresh momentum stories around Oxford Nanopore Technologies by scanning our hand-picked 8 healthcare AI stocks that sit at the crossroad of genomics, data, and AI-enabled research.After a nearly 80% surge over the past three months and fresh attention from the India Genomics Centre of Excellence, is the real upside in Oxford Nanopore Technologies still ahead, or has the share price already captured most of the story?
Preferred Price-to-Sales Multiple of 8.7x: Is it justified?
On valuation, the big tension for Oxford Nanopore Technologies is simple. The stock closed at £2.09 while carrying a P/S multiple of 8.7x, yet peers in Europe trade on far lower sales-based valuations.
The price to sales ratio compares the market value of a business to its annual revenue. For a loss-making life sciences tools group like Oxford Nanopore Technologies, investors often fall back on P/S because there is no positive earnings base to support a P/E measure. In effect, the market is placing a rich tag on each £1 of current turnover and its future growth potential.
That richness is clear in the comparisons. The P/S of 8.7x is flagged as expensive against a peer average of 2.2x and also against the broader European Life Sciences industry average of 3.9x. It also sits above an estimated fair P/S ratio of 6.9x, which suggests the current pricing embeds more optimism than that fair ratio level the market could move towards if expectations cool.
Explore the SWS fair ratio for Oxford Nanopore Technologies.
Result: Price-to-Sales of 8.7x (OVERVALUED)
Still, the story can break if Oxford Nanopore Technologies fails to turn rising revenue into profits, or if sentiment reverses after such a sharp recent rally.
Find out about the key risks to this Oxford Nanopore Technologies narrative.
Another view on Oxford Nanopore Technologies’ value
Multiples present Oxford Nanopore Technologies as expensive. The SWS DCF model points in the same direction. It places the value of future cash flows at about £1.50 per share, compared with a recent price around £2.09, which suggests investors are already paying a premium that reflects a high level of optimism.
Look into how the SWS DCF model arrives at its fair value.
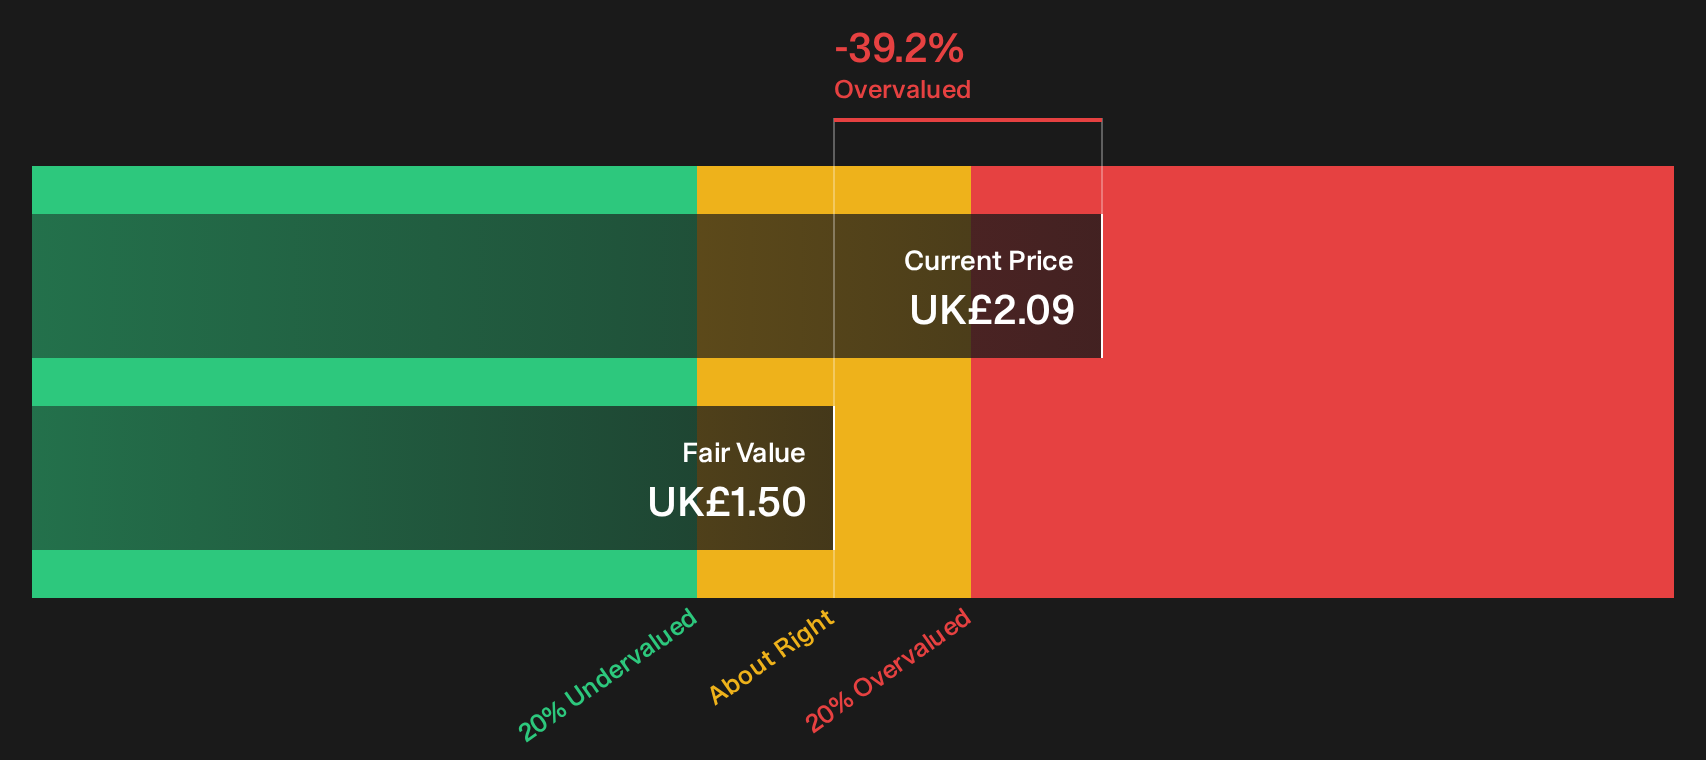
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Oxford Nanopore Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 8 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
So is the mood around Oxford Nanopore Technologies too hot, or still cautious enough to leave room for surprise? Act fast, review the underlying numbers yourself, and then balance your own view against the 1 key reward and 2 important warning signs.
Looking for more ideas beyond Oxford Nanopore Technologies?
Do not stop at one stock. Use the Simply Wall St Screener to pressure test your thinking across other opportunities and avoid getting anchored to a single story.
- Target stronger quality at a fairer price by checking companies that pass through the 8 high quality undervalued stocks with both business strength and appealing valuation profiles.
- Prioritise resilience by scanning the list of solid balance sheet and fundamentals (9 results) so you focus on businesses with sturdier finances backing their share prices.
- Hunt outside the usual watchlists by reviewing the 5 high quality undiscovered gems that pair robust fundamentals with less crowded investor attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com