


The Bet Honda Motor Holders Made
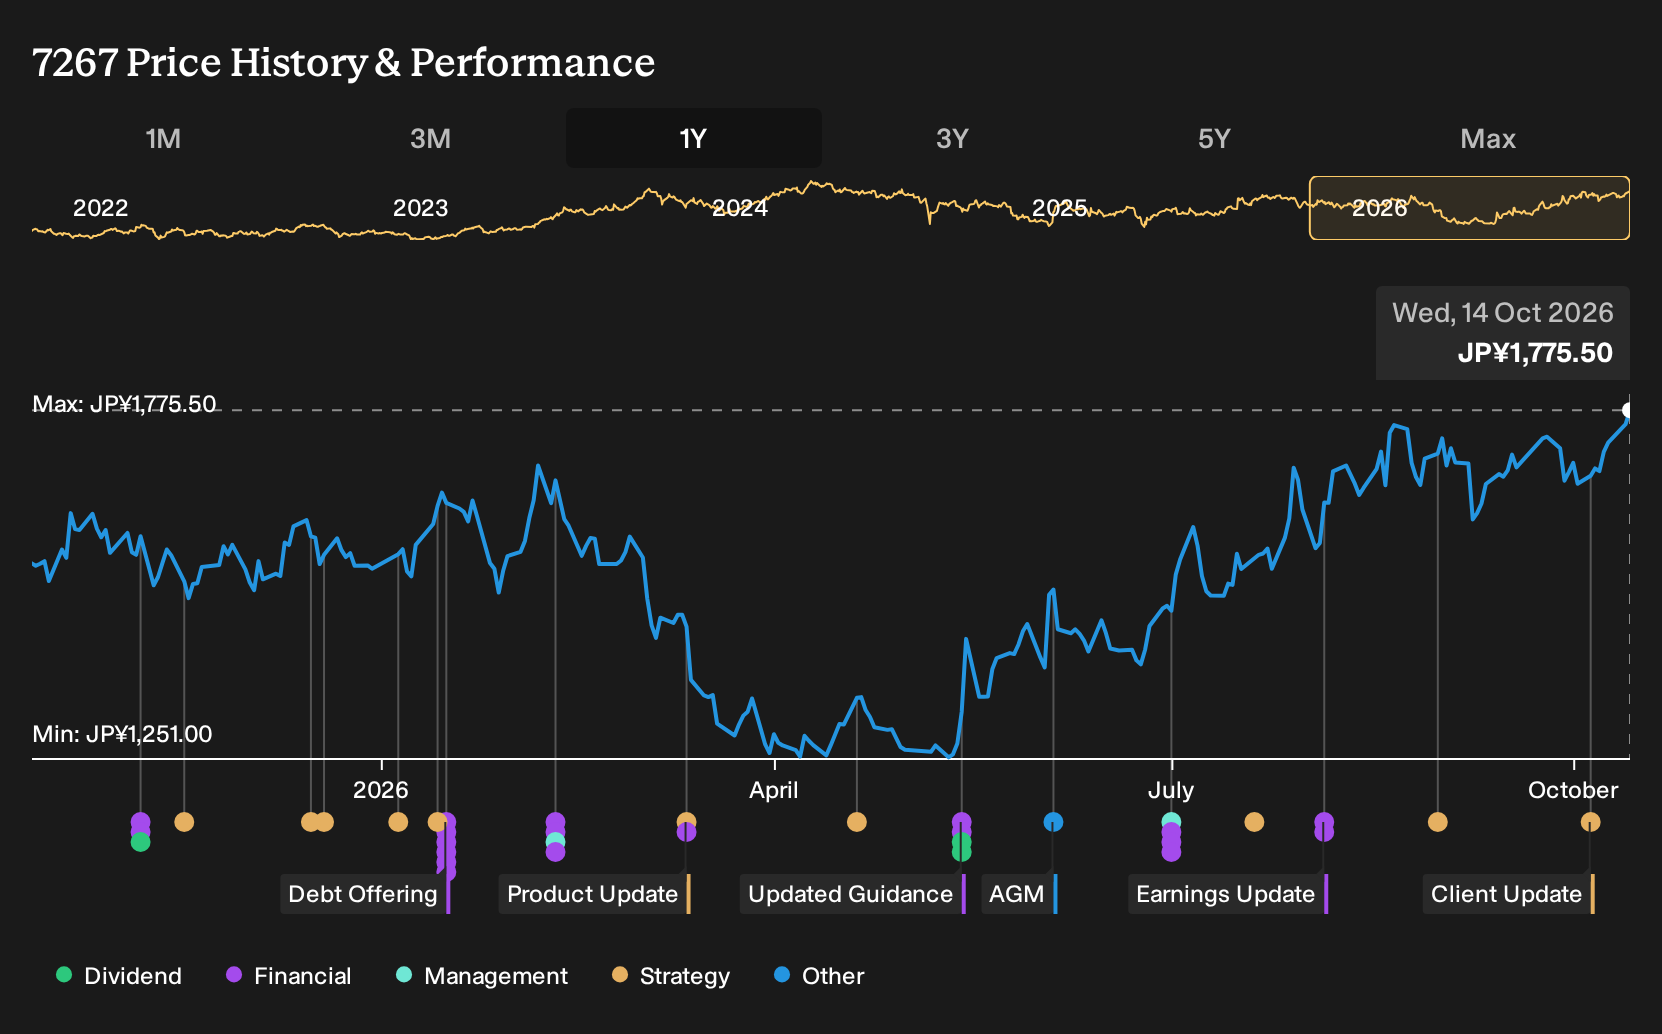
If Honda Motor was on your watchlist rather than in your portfolio, the past year may feel like an opportunity that slipped. Holding Honda Motor over the past year would have returned 20.6%, including dividends. The key question is what, back in October 2025, could have helped you spot that potential when analysts were split on whether US localization and emerging market motorcycles could really support revenue growth and a higher long term profit margin.
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
This theme extends beyond Honda Motor. See which of 90 robotics and automation stocks may still merit a closer look.
The Two Stories Honda Motor Investors Had To Weigh
The shares cost ¥1,538 at the start of the period, and anyone looking at Honda Motor then faced two very different but reasonable stories about what came next.
On the optimistic side, the bull narrative put Fair Value at ¥1,713, assuming revenue growth of 1.2%, a 3.8% profit margin and a future P/E of 9.0x, supported by expanding motorcycle sales in emerging markets as well as more localized hybrid production in the US.
The bearish view pointed to a Fair Value of ¥1,317, focused on rising tariffs, delayed battery electric projects and the risk that weaker EV positioning and tougher trade policies could pressure revenue and margins for years.
What The Results Changed For The Honda Motor Debate
Honda Motor’s later pivot, including more than ¥1.4 trillion of EV restructuring charges, an operating loss and scrapped Canada BEV plans, leaned toward the cautious thesis that pure EV bets were risky. Subsequent Q1 2027 figures told a different story. Revenue and net income were higher than Q1 2026, and net margin widened from 3.7% to 7.4%. Overall, the evidence cut both ways.
The key assumption was which drivetrain mix would support better economics. For other automakers, that can be tested by tracking net margin and segment commentary around EV and hybrid programs each reporting season, and by checking whether the chosen mix actually improves profitability over time.
What Today's Honda Motor Price Already Assumes
Honda Motor shares now trade at ¥1,776 after a 20.6% gain over the past year. The selected Narrative’s Fair Value sits below that price, which frames today’s level as already incorporating a demanding outcome rather than treating it as a clear mispricing.
This view depends on execution. A buyer today is effectively assuming the motorcycle and hybrid pivot converts restructuring and joint programs into durable cash flow. The question is how that compares with the Narrative’s focus on execution risk and potential strain on margins.
"The main condition for improvement is that Honda Motor turns its motorcycle and next-generation hybrid programmes, including cost cuts and localization in autos, into stable cash generation that more than offsets restructuring costs and weakness in China. The numbers imply that Honda Motor’s share price already reflects strong outcomes on record motorcycle profits, ambitious margin targets and large projected cash flows, leaving limited room for disappointment if execution or demand falls short."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Go Straight To The Source
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 19% below our estimate - supplies high precision photomasks that chipmakers adopt for newer packaging and nanoimprint processes.
- Company 2 - 35% below our estimate - designs complex air and heat systems that facility owners upgrade for cleaner, more controlled environments.
- Company 3 - 37% below our estimate - sells low code workflow platforms teams switch to once spreadsheets can no longer track projects.
Three companies from the same screener. Open every one of the 15 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com