


Salesforce (CRM) Stock May Be Undervalued As AI Deal Activity Builds
Salesforce has pushed deeper into artificial intelligence with a string of acquisitions and product moves, yet the share price has been roughly flat over the past year. This brings the focus back to a basic question about what investors are paying for its earnings today.
- Over the past 5 years the stock has delivered a decline of 17%, which makes the current P/E and earnings power especially important for anyone reassessing what the business is worth now.
- New AI oriented deals such as Listen Labs and Loops, along with products like the Koa model and Agentforce, can influence how investors think about future profit growth and the timing of cash generation from Salesforce's platform.
- There is a second opinion on Salesforce worth weighing. See what analysts think Salesforce's shares could be worth.
For investors, the debate is whether Salesforce's current share price around US$238 is adequately supported by the earnings it is generating today.
If you want to test the same earnings question you are asking of Salesforce across a wider set of AI focused platforms, start with 92 AI infrastructure stocks.
Is Salesforce Still Cheap on Earnings?
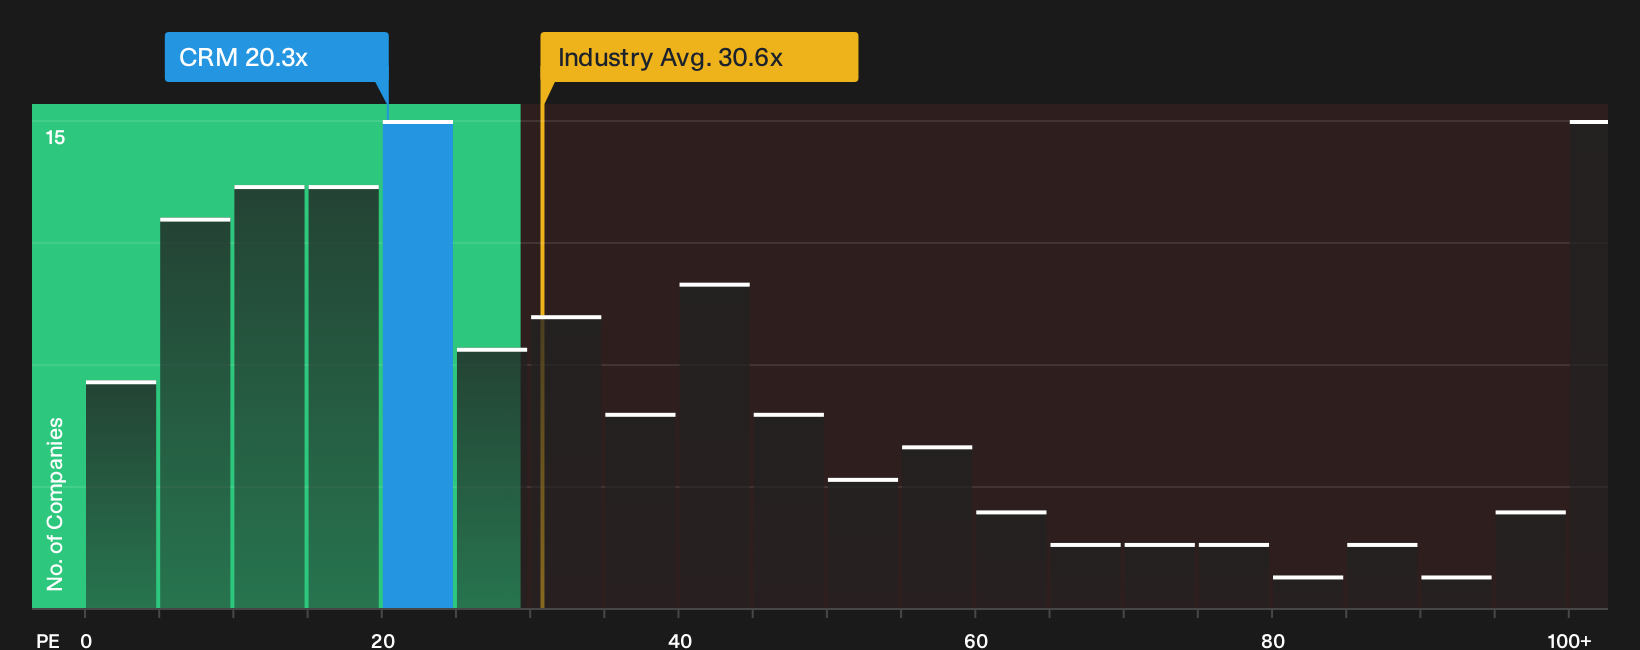
The P/E ratio suits Salesforce because investors often focus on how much they are paying for each dollar of earnings from its large, mature software platform. At a current P/E of about 20.3x, Salesforce trades below the broader software industry average of 30.6x and well under the peer group at roughly 46.3x, which points to a discount against both its sector and closer competitors.
Bank of America’s recent upgrade that leaned on Salesforce's AI roadmap and platform resilience has lifted sentiment, yet the P/E still sits below the level a tailored fair multiple model suggests for a company with its profitability profile. That framework, which weighs factors like margins, growth outlook, market size and risk, indicates the stock trades under the multiple you might expect on those fundamentals. If you think the AI push and acquisitions such as Listen Labs and Loops will strengthen earnings quality over time, this gap on the earnings multiple becomes a central part of the investment debate. Explore the numbers behind Salesforce's P/E valuation.
The Salesforce Narrative: What Would Justify Today's Price?
Simply Wall St's Narratives for Salesforce pick up exactly where the P/E puzzle leaves off, by setting out the future paths for growth, margins and earnings that would need to play out for the stock to be worth materially more or materially less than today's share price, and they sit on the Community page. Instead of giving a single output from a ratio or model, these scenarios spell out the future that figure relies on so you can keep checking whether Salesforce's actual progress still lines up with it.
One of the top community narratives on Salesforce: 19% undervalued
"Salesforce may sell governed work, which means trusted data, permissions, workflows, audit trails, agent actions, and enterprise context…"
Discover why this Narrative puts Salesforce at 19% undervalued.
One more check for Salesforce that belongs next to the P/E
The final piece to line up with Salesforce's earnings multiple is who is steering the ship and how their rewards line up with your goals as a shareholder. See who runs Salesforce and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com