


What Apple Hospitality REIT Shares Earnings Beat Means For Shareholders
- Apple Hospitality REIT reported second quarter MFFO of $0.52 per share against a monthly dividend of $0.08, with comparable RevPAR growth of 5.3% and an adjusted hotel EBITDA margin of 38.1%, which supports higher 2026 Adjusted EBITDAre guidance.
- The gap between MFFO and the current monthly payout highlights dividend coverage, while expanding hotel level margins point to operating efficiency across Apple Hospitality REIT’s rooms focused portfolio.
- We will now examine how Apple Hospitality REIT’s raised 2026 Adjusted EBITDAre guidance could reshape its investment narrative for income focused investors.
Compare Apple Hospitality REIT’s income profile with other high-yield opportunities by scanning our hand picked 8 dividend fortresses across the market.
Apple Hospitality REIT Investment Narrative Recap
To own Apple Hospitality REIT, you need to be comfortable with a rooms focused hotel portfolio that leans on steady RevPAR and disciplined spending to support cash generation. The latest quarter shows MFFO of $0.52 per share against a $0.08 monthly dividend, which points to current coverage. The near term upside story depends on hotel performance holding up as renovations and market specific softness are managed.
The biggest operational swing factor right now is how quickly renovated properties in markets such as Anchorage and Seattle return to normal occupancy and rate. On the risk side, commentary like Jim Cramer’s rate warning highlights an existing pressure point. Higher for longer financing costs would matter, but the Mad Money soundbite itself does not change Apple Hospitality REIT’s day to day business drivers.
The most relevant recent data point is management’s decision to raise 2026 Adjusted EBITDAre guidance to a range of $453 million to $476 million. That outlook is being supported by current hotel level trends, including 5.3% comparable RevPAR growth and a 38.1% adjusted hotel EBITDA margin in the latest quarter. For income focused holders, that guidance range is now a key reference.
It effectively sets a benchmark for how well Apple Hospitality REIT needs to execute on renovations, capital allocation and rate discipline across markets that may not all move in the same direction. Any clear deviation from that 2026 EBITDAre range, especially if driven by weaker RevPAR or slower ramps at upgraded assets, would relate directly to both the dividend profile and the medium term investment thesis.
Apple Hospitality REIT's current analyst narrative points to revenues of US$1.5b and earnings of US$190.3m by 2029. This rests on 2.4% yearly revenue growth and an earnings increase of about US$15m from US$175.3m today to the 2029 consensus figure.
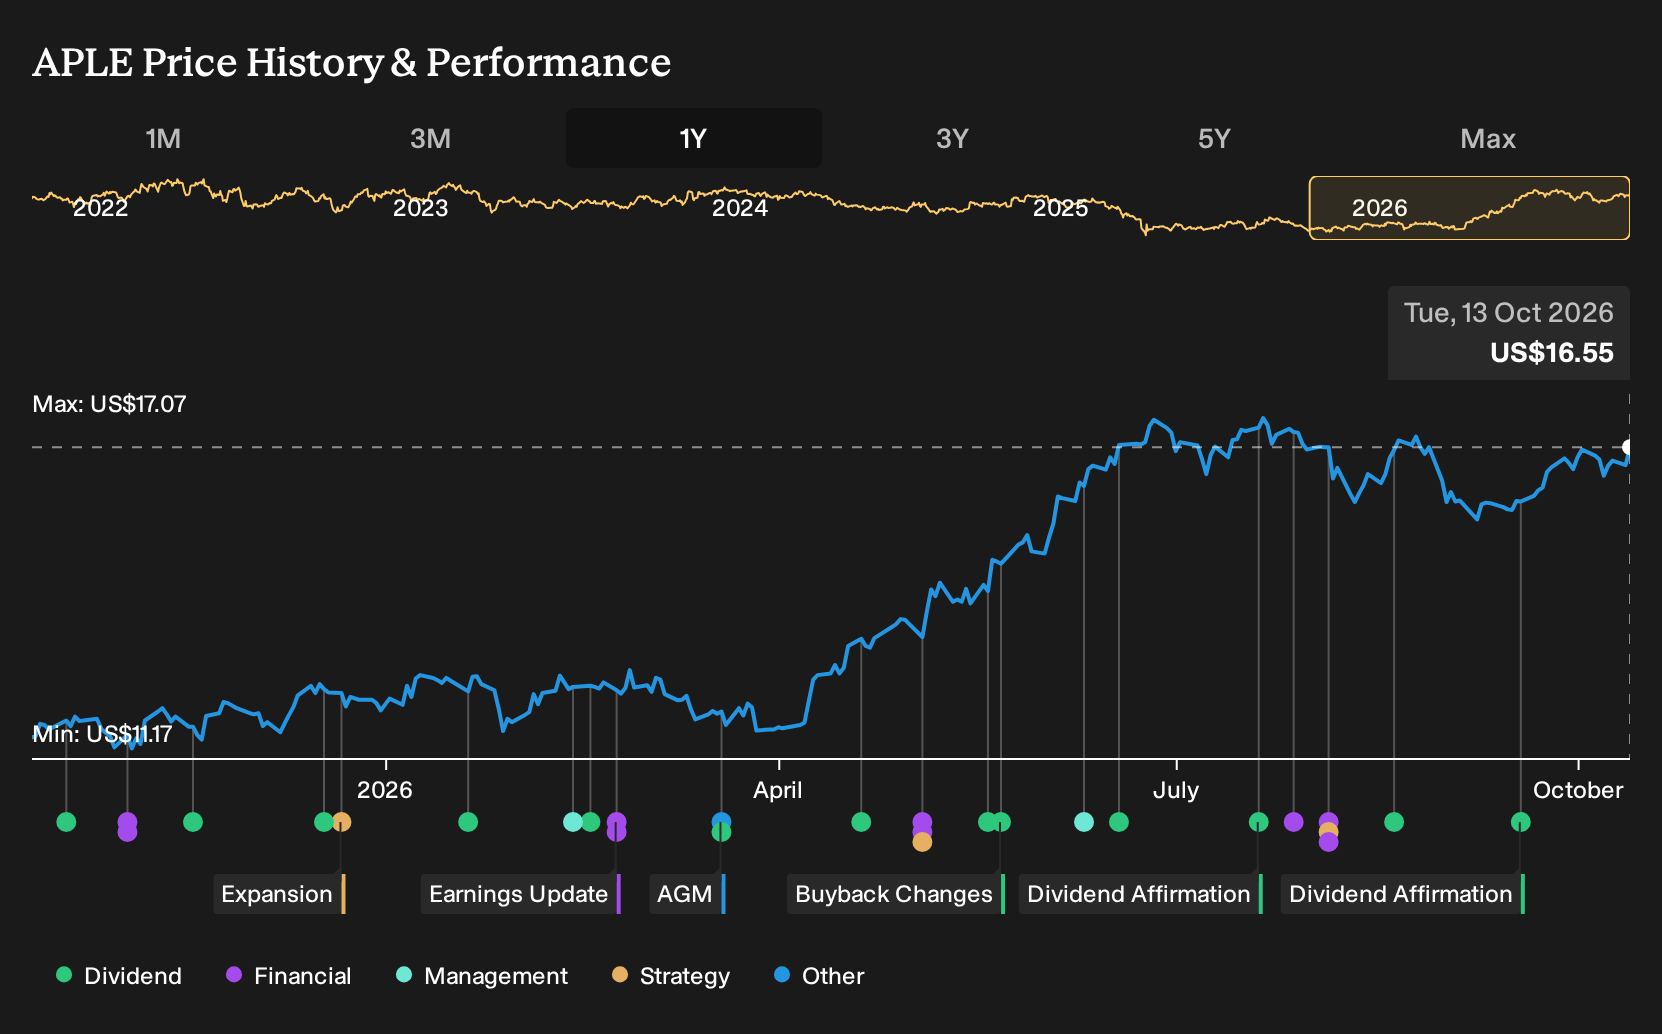
Uncover why Apple Hospitality REIT's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$17.17 to US$37.60, which shows how sharply views on Apple Hospitality REIT can diverge. You have income focused investors watching monthly dividends and MFFO, while others focus on renovation risk and muted hotel transaction activity as potential brakes on future performance.
Explore another Apple Hospitality REIT fair value estimate, including one that suggests as much as 127% potential increase from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Apple Hospitality REIT research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Apple Hospitality REIT. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Apple Hospitality REIT's overall financial health at a glance.
Looking For More Investment Ideas Beyond Apple Hospitality REIT?
If you want to put Apple Hospitality REIT into context, it helps to line it up against other opportunities that match your income, quality, or risk preferences. The Simply Wall St Screener can surface groups of companies with similar traits so you can pressure test your thesis and avoid anchoring on a single stock.
- If capital preservation matters most, start with resilient companies that historically show fewer red flags by reviewing 32 resilient stocks with low risk scores.
- For investors who care about quality and price discipline, compare Apple Hospitality REIT with other financially strong businesses using our 20 high quality undiscovered gems.
- If balance sheet strength is your first filter, narrow the field to companies with healthier funding profiles and robust fundamentals via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com