


Is ALSO Holding (SWX:ALSN) Undervalued As Its Huntress Partnership Expands Its European Reach?
Huntress has just signed a new distribution partnership with ALSO Holding (SWX:ALSN), using the Swiss group’s pan European network and Cloud Marketplace to push the Huntress Agentic Security Platform into 31 countries.
ALSO Holding’s latest move with Huntress comes after a mixed run in the market, with the share price at CHF203.0 and short term gains such as a 1 month share price return of 4.42% set against a weaker long term picture that includes a 1 year total shareholder return decline of 8.36% and a 5 year total shareholder return decline of 18.47%. This suggests that recent momentum is improving, but longer term holders have faced pressure.
Scan how ALSO Holding stacks up against other European IT distributors by running the curated list of solid balance sheet and fundamentals (203 results) aligned with resilient cash generation and balance sheet strength themes.
Short term momentum has picked up at ALSO Holding while longer term returns still lag. Is most of the easy recovery already reflected in the CHF203 share price, or does the current valuation still leave meaningful upside on the table?
Preferred Price-to-Earnings of 20.5x: Is it justified?
ALSO Holding currently trades on a P/E of 20.5x, with the CHF203 share price sitting modestly below both an estimated fair value and an internal cash flow appraisal of CHF216.03. Together, these figures point to a market that is not pricing the stock as aggressively as some peers.
The P/E ratio compares what investors pay today for each unit of current earnings. For ALSO Holding, a 20.5x multiple means the market is paying CHF20.50 for every CHF1 of profit. For a technology services distributor with €14,664.853m of revenue and €135.432m of net income, this perspective helps show how much of the current ICT and cloud distribution story is already embedded in the price.
There is a clear tension in how that earnings tag looks. On one side, the stock is described as good value relative to an estimated fair P/E of 29x, which indicates the market could move toward paying a richer earnings multiple if current conditions persist. On the other side, ALSO Holding trades slightly above the broader European Electronic industry average P/E of 20.1x, so the share sits on a small premium to regional peers even though its returns over 1 and 5 years have lagged the wider Swiss market and sector.
Explore the SWS fair ratio for ALSO Holding.
Result: Price-to-Earnings of 20.5x (UNDERVALUED)
Still, ALSO Holding faces pressure from a declining 5 year total return and recent year to date weakness, particularly if distributor competition further compresses margins.
Find out about the key risks to this ALSO Holding narrative.
Another View: ALSO Holding Through The DCF Lens
The P/E points to ALSO Holding looking inexpensive, yet the SWS DCF model is more restrained. At CHF203 the share price sits roughly 6% below an estimated future cash flow value of CHF216.03, which implies only a limited margin of safety. Is that discount enough for the risk you are taking?
Look into how the SWS DCF model arrives at its fair value.
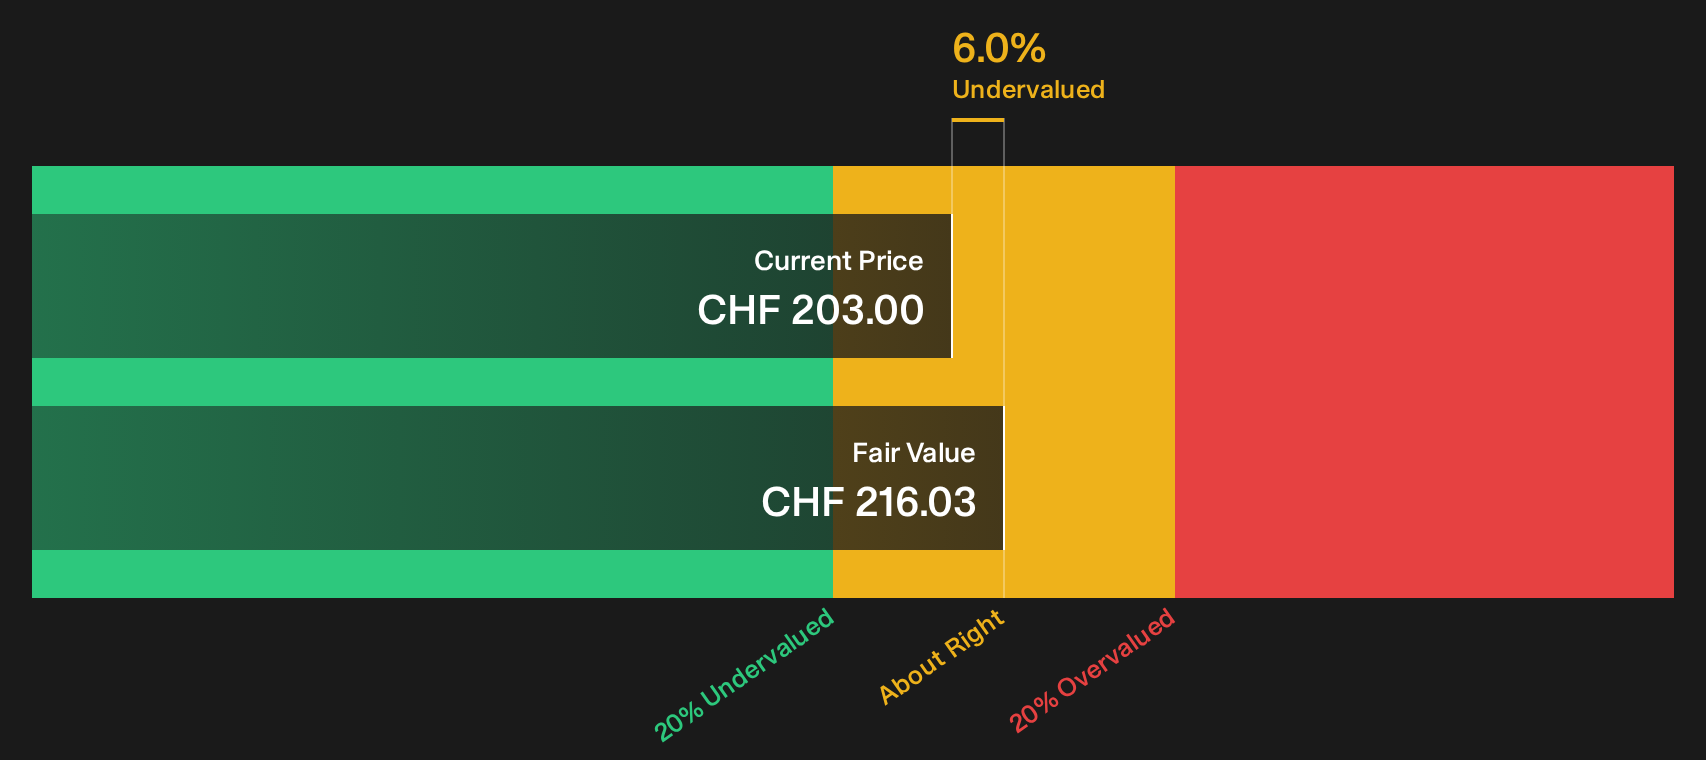
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ALSO Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 184 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around ALSO Holding can pull you in either direction, so act while the data is fresh and weigh both sides for yourself with the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond ALSO Holding?
If ALSO Holding is on your radar, do not stop there. Broader context across other opportunities can sharpen your decisions and highlight better fits.
- Target higher quality potential by scanning companies that combine strong cash generation with attractive pricing through the 184 high quality undervalued stocks.
- Pursue stability and sleep better at night by reviewing the 223 resilient stocks with low risk scores that focuses on resilient businesses with lower risk scores.
- Spot lesser known opportunities before the crowd by running the 617 high quality undiscovered gems and comparing them against your current watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com