


How Investors May Respond To Newmont Stock As Earnings Near
- Newmont is preparing to report quarterly results on 22 October 2026, with analyst forecasts pointing to higher earnings per share and revenue supported by the integration of Newcrest Mining assets.
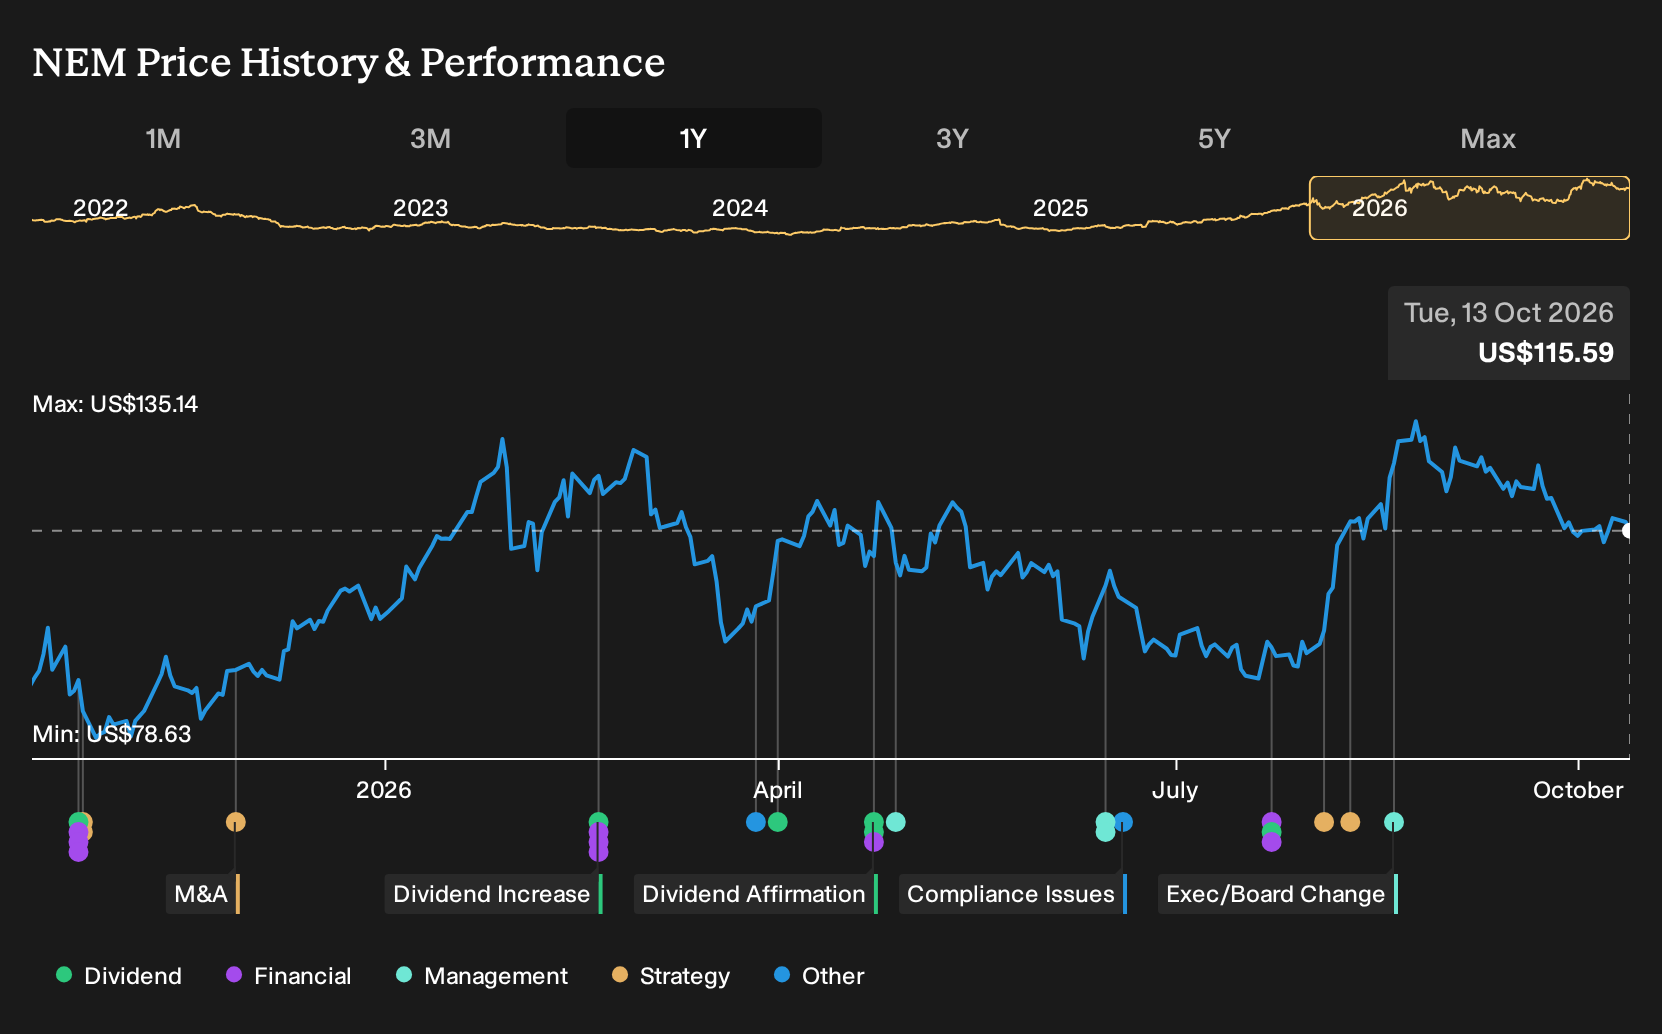
- The pullback in Newmont's shares comes as investors weigh expected earnings gains against risks from mine performance and rising capital spending pressures on cash flow.
- Next, the focus shifts to how Newmont's broader investment narrative aligns with the upcoming earnings release and integration progress.
Compare Newmont's setup with a curated group of peers by scanning the 36 elite gold producer stocks that may also be gearing up for earnings and production catalysts.
Newmont Investment Narrative Recap
To own Newmont, you need to be comfortable with a miner that is leaning on its larger production base and the Newcrest acquisition to keep earnings and cash generation resilient over time. The upcoming 22 October earnings release is the key short term check on that story, especially around how the combined asset base is running day to day.
The biggest operational swing factor right now is whether higher production and synergy capture can offset rising sustaining and development capital spending. Recent share price weakness does not materially change that equation. The main near term risk remains mine underperformance or safety incidents that force further cost, delay or regulatory pressure just as spending is already elevated.
The most relevant recent data point tied to this setup is the anticipated 12.28% year on year increase in earnings per share and 8.8% revenue uplift to US$6.01b that analysts expect for the upcoming quarter. Those figures sit against a backdrop of historical earnings growth of 45.2% per year over the past 5 years and current net margins of 33.4%.
For you as a shareholder, the question is whether Newmont can translate the Newcrest asset integration into sustained operational stability while absorbing higher capital needs at sites like Cadia, Peñasquito and Lihir. The coming report should help clarify if cost control, productivity work and synergy delivery are keeping that balance on track or if cash flow is tightening.
Newmont's current analyst storyline points to revenue of US$31.3b and earnings of US$12.6b by 2029, built on 6.7% yearly top line growth and an earnings increase of US$4.0b from the US$8.6b figure reported today.
Discover why Newmont's fair value signals a 19% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Newmont leans hard into demand risk. The most bearish analysts worry that weaker long term interest in gold drags on the top line, which is why they were only pencilling in revenue of about US$24.9b and earnings of US$9.4b for 2029. Those pre news estimates paint a much more cautious story than consensus, and the upcoming results could easily shift both narratives. Retail investors may want to compare these sharply different assumptions and consider which version of the outlook they find more realistic.
Explore 8 other Newmont fair value estimates, including one that suggests as much as 19% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so rely on your own analysis.
- A great starting point for your Newmont research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Newmont. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Newmont's overall financial health at a glance.
Looking For More Ideas Beyond Newmont?
If you want to stress test your Newmont thesis, compare it against a wider field of opportunities using the Simply Wall St Screener. Lining up different types of businesses side by side can help you see whether Newmont still earns a spot in your portfolio or if there are alternatives that better fit your priorities on risk, income or value.
- For investors who care most about quality at a sensible entry price, scan a curated set of potential value opportunities through the 32 high quality undervalued stocks.
- If capital preservation and balance sheet strength sit at the top of your checklist, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions.
- When you want to uncover underfollowed opportunities before they are widely talked about, filter for hidden prospects using a 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com