


Did New AI Power Products Just Shift Advanced Energy Industries' (AEIS) Investment Narrative?
- Advanced Energy Industries recently introduced higher power density M-CRPS power supplies, the Centra Smart Hub temperature control platform, and a 33 kW ORv3 High-Power Rack option, all aimed at data centers, AI, telecom, and semiconductor equipment.
- The cluster of launches shows Advanced Energy Industries pushing deeper into high power density and precision control, which can shift where it earns the most content per rack and per semiconductor tool.
- The next area of focus is how these higher power density OCP-compliant supplies might reshape Advanced Energy Industries' broader investment narrative.
Advanced Energy Industries Investment Narrative Recap
For a shareholder in Advanced Energy Industries, the core belief is that demand for precision power in AI data centers and semiconductor tools keeps pulling more of its portfolio into customer racks and process chambers. The near term catalyst is execution on these higher power density platforms while integrating new capacity and inventory without letting capital efficiency slip.
The biggest operational risk is that heavy CapEx, rising inventories and the US$1.15b convertible note leave returns on that spending below expectations if utilization disappoints. The new launches sharpen the product story but do not on their own remove valuation and dilution concerns that are already front of mind.
The new 3,600 W OCP compliant M CRPS power supplies look closest to the current catalyst around AI data center programs and 800 V platforms. Higher power density in the same chassis gives existing customers a technical path to put more Advanced Energy Industries content into each rack without a wholesale redesign of their mechanical infrastructure.
Operationally, that creates more surface area for design wins, but it also raises the bar on reliability, thermal management and cybersecurity that these units explicitly target. Execution on volume ramp and field performance will influence how much of the planned capacity build and margin ambition is supported by repeat AI and cloud orders versus more cyclical industrial and semiconductor spending.
Advanced Energy Industries' narrative centers on analysts expecting US$4.0b in revenue and US$904.8 million in earnings by 2029, based on a projected 25.0% yearly revenue growth rate and a move from US$220.7 million in earnings today to the 2029 consensus. This implies roughly a 4x earnings increase over that period.
Uncover why Advanced Energy Industries' fair value indicates a 56% potential upside to its current price that may not last much longer.
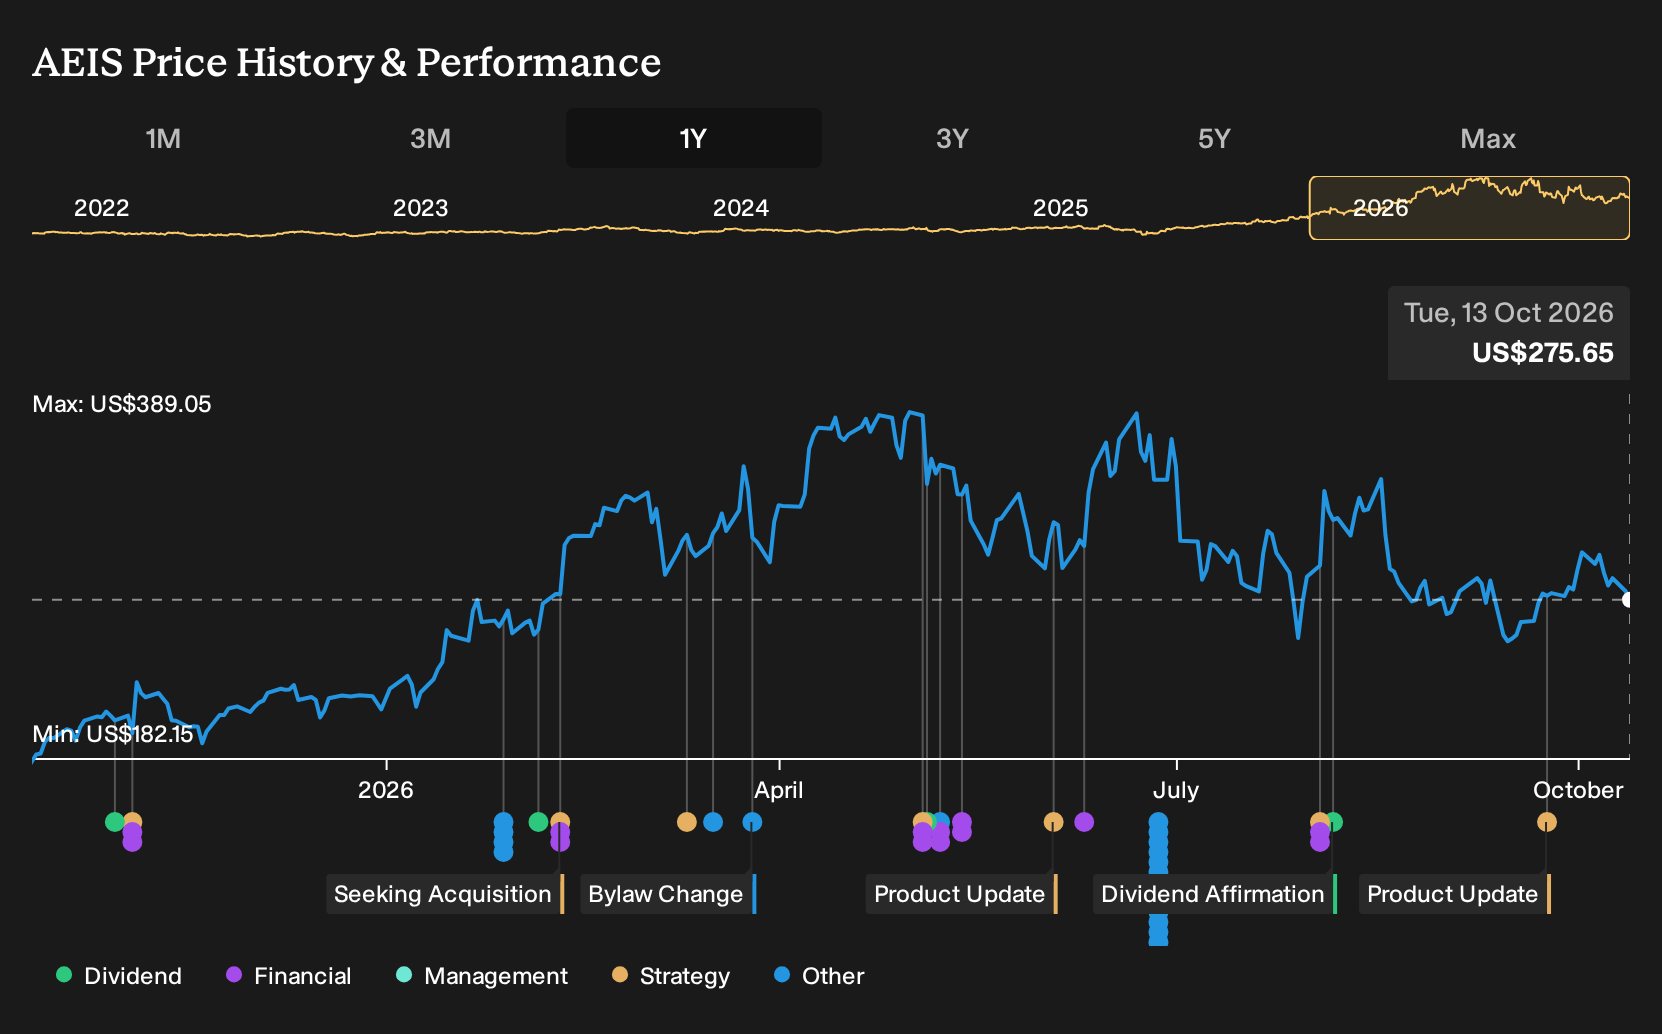
Exploring Other Perspectives
One alternate view is that capacity risk, not AI upside, is the real swing factor for Advanced Energy Industries. The most cautious analysts were only penciling in about US$3.9b of revenue and US$904.3 million of earnings by 2029 before this news, and they used a lower 24.7x P/E. These forecasts came before the new OCP power supplies and Centra Smart Hub, so you may see those bears revisit their models. It is worth comparing both stories yourself to decide which assumptions feel closer to how you think demand for high power racks and precision temperature control will actually develop.
Explore 4 other Advanced Energy Industries fair value estimates, including one that suggests it could be worth just $360.00!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Advanced Energy Industries research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Advanced Energy Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Advanced Energy Industries' overall financial health at a glance.
Looking for more investment ideas beyond Advanced Energy Industries?
If the Advanced Energy Industries story has sharpened your interest in precision power and AI infrastructure, it may be a good moment to widen the lens and compare it with other candidates using the Simply Wall St Screener.
- For investors hunting for quality at a discount, scan a curated group of 32 high quality undervalued stocks that combine fundamentals with what our models view as attractive pricing.
- If balance sheet strength is non negotiable for you, focus on a list of solid balance sheet and fundamentals (25 results) that score well on debt, liquidity and financial resilience.
- For those who like to get in early before wider attention arrives, sift through a set of 20 high quality undiscovered gems that pair solid fundamentals with lower market visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com