


Diageo (LSE:DGE) Launches India Festive Blend On A Narrative That Still Sees Value
Product launch puts Diageo’s India exposure in focus
Diageo (LSE:DGE) has turned attention to its Johnnie Walker portfolio with the new Blue Label Indian Festive Blend, a limited release tailored to India’s festival season and cuisine.
The release leans on Diageo’s access to more than 10 million aging whiskies, where only a small fraction is considered suitable for Blue Label. It also extends the brand’s collaboration with Indian couturier Rahul Mishra into a second year.
India already represents a sizeable part of Diageo’s footprint, with £3,213 million of revenue attributed to the country. A premium, locally resonant whisky expression gives the group another way to engage higher end consumers in that market.
Recent price action has picked up for Diageo, with a 1-day share price return of 2.36% and a 90-day gain of 11.82% pointing to building momentum, even though the 3-year total shareholder return is down 40.12%.
Spot 8 high quality undervalued stocks that, like Diageo, combine global brands with sizeable cash generation and could be setting up for their own momentum turn.After an 11.82% gain in 90 days but a 40.12% decline in total return over three years, Diageo now sits at an awkward crossroads. Is the recent bounce the main act, or just the warm up before valuation does more work?
Most Popular Narrative: 15% Undervalued
On Simply Wall St's most followed narrative, Diageo's fair value sits at about £20.07 against a last close of £17.13. This frames the current rebound as a move inside a wider valuation gap rather than the whole story.
Diageo is intensifying its focus on premiumization and category expansion (notably in tequila and ready-to-drink beverages) to capture rising consumer affluence and elevated brand preferences in both emerging and developed markets, supporting future revenue growth and gross margin expansion. The company is executing a multiyear overhaul to deepen locally tailored, occasion-led marketing and distribution strategies across key regions (Europe, Asia-Pacific, and Africa), positioning itself to leverage demographic shifts such as urbanization and a growing legal drinking-age population, which are expected to drive volume and sales momentum over the long term.
See why 150 investors see Diageo as 15% undervalued.
That storyline anchors a fair value around 15% above the current price, built on a discount rate assumption of 7.56% and forecast profit margins of about 21.2%. It leans on earnings expected to rise faster than the wider UK market, even as revenue growth assumptions remain modest at roughly 1.4% a year.
Analysts in that narrative also accept a lower future P/E multiple of about 17.7x on those projected earnings compared with a higher implied multiple today. In plain terms, the thesis assumes Diageo can lift earnings without needing investors to pay the same premium multiple they currently do.
Result: Fair Value of £20.07 (UNDERVALUED)
Still, the narrative could unravel if consumer moderation towards alcohol is more severe than expected or if execution stumbles in higher risk regions such as Africa and Latin America.
Find out about the key risks to this Diageo narrative.
Another View: Diageo looks pricey on earnings
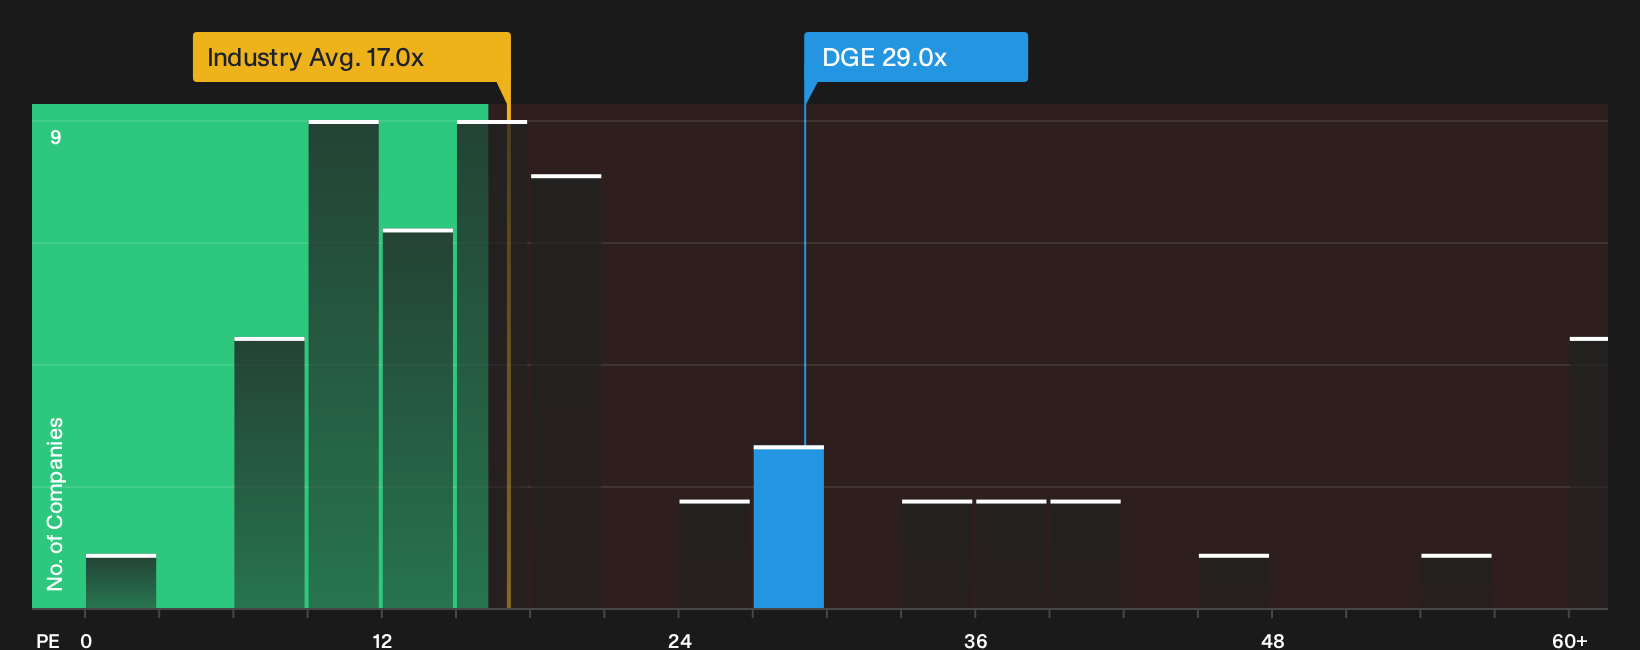
Diageo may screen as undervalued on fair value models, yet its current P/E of 29x tells a different story. That figure sits well above the European beverage group average of 17x and even edges past its own 28.5x fair ratio, which suggests limited cushion if sentiment cools.
The gap between Diageo's P/E and both industry peers and its fair ratio points to higher valuation risk, not a clear bargain. If earnings forecasts slip or investors demand a lower multiple, how comfortable are you owning a stock that already prices in this kind of optimism?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed stories on valuation and sentiment only get you so far. Move quickly, look through the underlying metrics yourself and build a view that fits your risk tolerance and time horizon, then pressure test it against the 2 key rewards and 3 important warning signs
Looking for more Diageo-like investment ideas?
If Diageo’s story has you thinking about valuation, quality and timing, do not stop with a single ticker. Cast the net wider and pressure test your conviction across a range of potential opportunities using focused screeners built to surface specific traits.
- Target resilience by reviewing companies with strong finances and conservative leverage through the list of solid balance sheet and fundamentals (9 results).
- Hunt for potential mispricings by scanning for 8 high quality undervalued stocks that line up with your return expectations and risk limits.
- Spot quieter opportunities by checking the 5 high quality undiscovered gems that combine solid fundamentals with less crowded investor attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com