


Is Tokenised Deposits Altering The Investment Case For HSBC (LSE:HSBA)?
- HSBC Holdings and Ant International recently expanded their collaboration, with Ant International announcing live use of HSBC’s Tokenised Deposit Service for real-time treasury transactions in the Middle East, including intra-UAE dirham transfers and cross-border US dollar payments.
- The combination of blockchain-based treasury management and AI agent micropayment tests signals HSBC’s push to rewire core transaction workflows. This development could influence cost efficiency, client stickiness, and product differentiation across key trade corridors.
- We will now look at how HSBC’s investment narrative around Asian trade and digital efficiency could shift with tokenised deposit adoption.
Scan how HSBC Holdings' tokenised deposit push compares with other banks leaning into real-time finance by reviewing the 92 AI infrastructure stocks that is shaping tomorrow’s transaction rails.
HSBC Holdings Investment Narrative Recap
To own HSBC Holdings, you essentially need to buy into a story of Asian led growth in wealth, trade and transaction banking, supported by heavy digital investment. The near term bull case rests on earnings holding up as the bank leans into fee income, tokenised deposits and AI driven efficiency, while still keeping capital deployment disciplined.
The biggest short term swing factor is credit quality and margins tied to Hong Kong commercial real estate and global rate moves. The Ant related tokenisation news is directionally interesting but not yet material to group earnings. Execution risk remains around tech spend, bad loan coverage and restructuring benefits landing cleanly.
The most relevant adjacent development is the technical test with Ant Digital Technologies that linked HSBC’s Tokenised Deposit Service with Ant’s Jovay and Anvita Flow infrastructure for AI agent micropayments. That experiment put real time, blockchain settled transactions inside HSBC’s existing risk and compliance framework, which matters if you care about transaction banking as a core earnings pillar.
If these tokenised and AI driven payment rails scale, they could influence how much operating leverage HSBC squeezes from its global transaction network and Asian corridors. The same buildout ties back to the key risk though. Technology and digital transformation spending can drag on the cost to income ratio if client adoption is slower than hoped or if credit costs and regulatory demands absorb the savings.
HSBC Holdings' current analyst storyline assumes revenue reaching $86.0b and earnings of $34.0b by 2029, based on 8.5% yearly top line expansion and an earnings increase of about $12.9b from $21.1b today.
Uncover why HSBC Holdings' fair value indicates a 7% potential upside to its current price that may not last much longer.
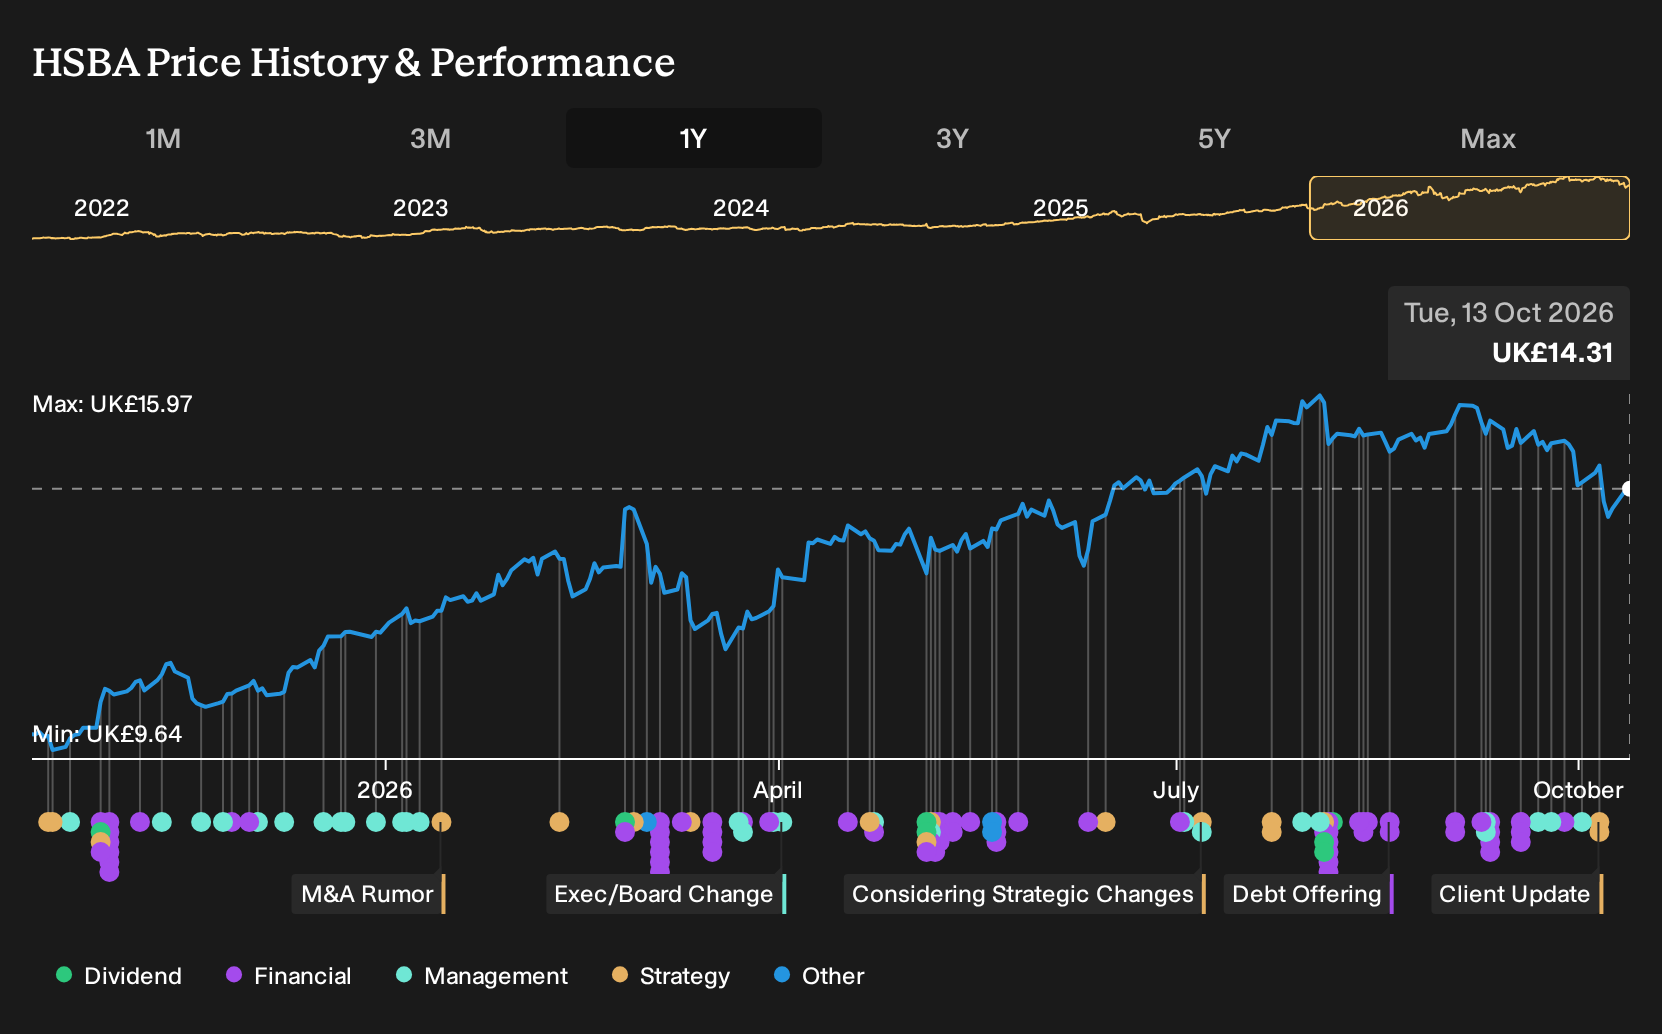
Exploring Other Perspectives
Some of the most optimistic analysts frame the Hang Seng Bank privatization plan as the key swing factor, not tokenised deposits. Before this news, that bullish camp was mapping out revenue of about $89.6b and earnings near $39.3b by 2029. You can treat this new Ant International collaboration as fresh input that could reshape those expectations.
Explore 11 other HSBC Holdings fair value estimates, including one that suggests as much as 60% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your HSBC Holdings research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for HSBC Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HSBC Holdings' overall financial health at a glance.
Looking for more HSBC Holdings sized investment ideas?
If this HSBC Holdings story has sharpened your thinking, you can use the same framework on a broader universe of companies by running a few focused screens.
- If you want potential value on your side, start with a basket of 8 high quality undervalued stocks that already combine stronger fundamentals with attractive pricing.
- If resilience matters more to you than excitement, concentrate on 4 resilient stocks with low risk scores that score well on financial strength and business stability.
- If you care most about balance sheet quality, filter for companies drawn from a list of solid balance sheet and fundamentals (9 results) and then apply your own judgment on which stories fit your playbook.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com