


Denison Mines (TSX:DML) Gains Interest Following Kindersley Study, Is It A Bargain?
Denison Mines Stock Reacts to Kindersley Lithium Project Milestone
Denison Mines (TSX:DML) drew fresh attention after Grounded Lithium Corp. released a pre-feasibility study for the Kindersley Lithium Project, outlining initial Mineral Reserves and clarifying Denison’s option to secure a majority working interest.
The Kindersley update landed during a choppy spell for Denison Mines, with the share price at CA$3.46 after a 1-day share price return of 2.67% that follows a 30-day share price decline of 17.42% and a 1-year total shareholder return decline of 22.94%. However, a 3-year total shareholder return gain of 71.29% signals that longer term holders have still seen substantial value creation despite recent pressure.
Spot opportunities around Denison Mines by scanning a curated set of nuclear energy infrastructure peers through the 16 nuclear energy infrastructure stocks.After a sharp pullback, yet a sizeable discount to both fair value estimates and analyst targets, is Denison Mines cheap for a reason, or has caution gone too far ahead of the valuation math?
Price-to-Book of 10.8x: Is Denison Mines’ Premium Justified?
On simple valuation markers, Denison Mines trades on a rich P/B multiple of 10.8x compared with a 2x average for the Canadian Oil and Gas group and 3.8x for its closest peers. That premium sits against a CA$3.46 share price and a SWS DCF model estimate of future cash flow value at CA$13.50, which together paint a more complicated picture than a single ratio suggests.
P/B compares the market value of the equity to the accounting value of net assets on the balance sheet. For an exploration and development player with limited current earnings and only CA$4 million of reported revenue, this metric often captures how investors weigh future project potential and resource optionality rather than today’s cash generation.
The broad gap to both the sector and peer P/B averages signals that the market is paying a substantial premium for Denison Mines’ uranium portfolio and expected growth, including forecasts that revenue could expand 58% per year with earnings growth projected at 66.36% per year and a path to profitability within three years. Given current losses of CA$275.568 million and a very weak historic return on equity, that valuation suggests investors are heavily front-loading those growth assumptions into the price.
Compared with the Canadian Oil and Gas industry at 2x and peer companies at 3.8x, a 10.8x P/B is more than double the peer benchmark and over five times the wider group. That scale of premium is hard to ignore and leaves less room for error if forecasts on revenue and profitability do not materialize as expected.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-book of 10.8x (OVERVALUED)
Still, Denison Mines faces clear tripwires, including the risk that uranium project timelines slip and that continued losses of CA$275.568 million weigh on investor patience.
Find out about the key risks to this Denison Mines narrative.
Another View: Denison Mines Through the DCF Lens
While the 10.8x P/B ratio makes Denison Mines look expensive beside a 2x sector average and 3.8x peers, the SWS DCF model presents a different perspective. On that framework, the shares at CA$3.46 are compared with an estimated future cash flow value of CA$13.50, which frames current pricing as potentially undervalued rather than stretched. The question is whether you place more weight on the balance sheet snapshot or on the long runway of projected cash generation.
Look into how the SWS DCF model arrives at its fair value.
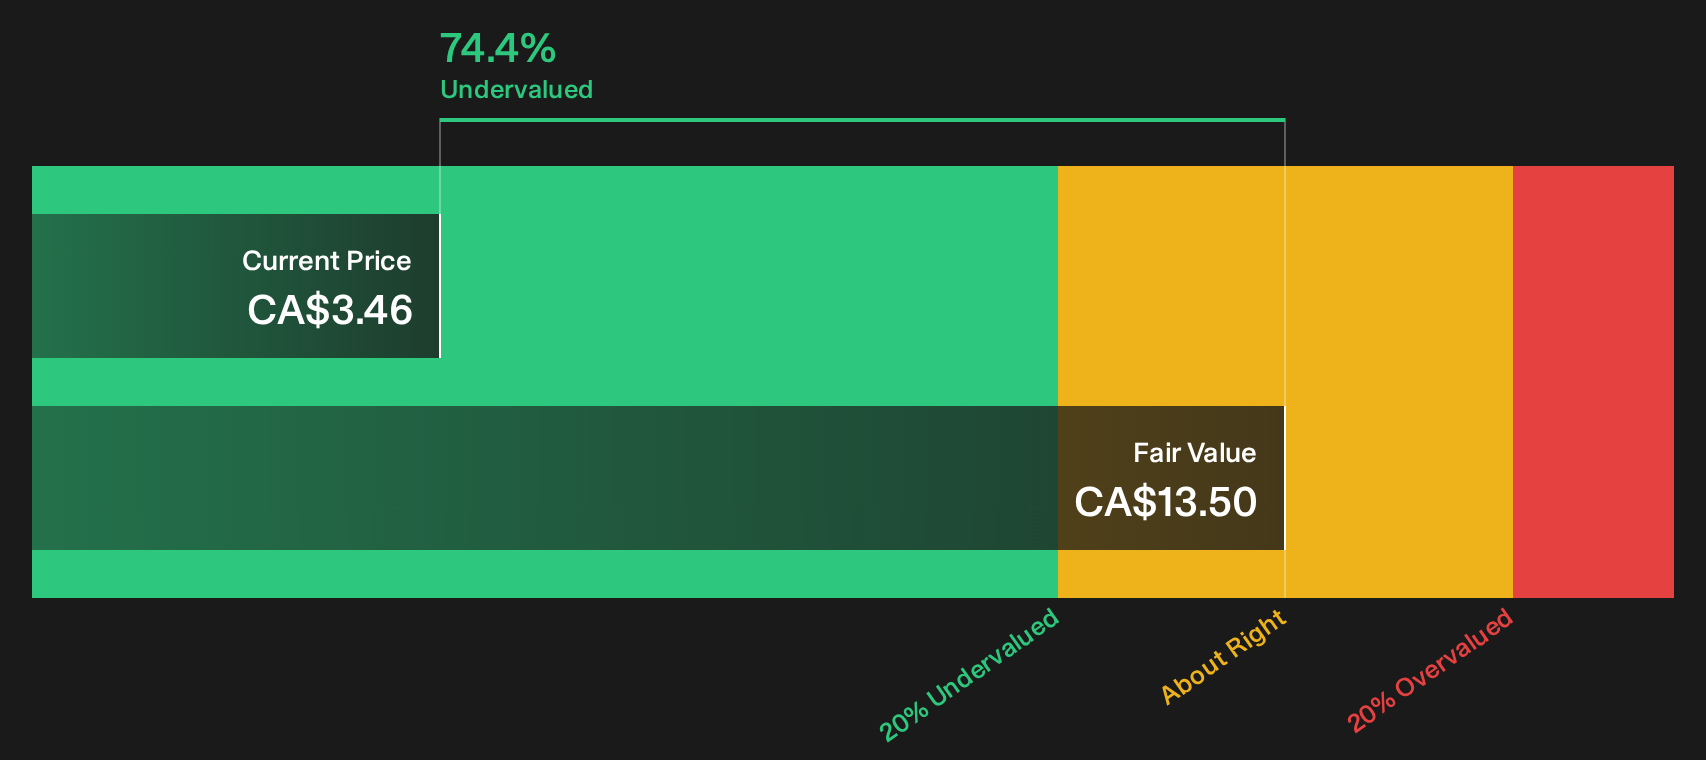
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Denison Mines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 8 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Denison Mines can feel messy, so consider reviewing the underlying numbers promptly and anchoring your own thesis around 3 key rewards and 1 important warning sign
Looking For More Ideas Beyond Denison Mines?
Denison Mines might be on your radar, but building a resilient portfolio means backing more than one opportunity that fits your style and risk tolerance.
- Target quality at a discount by checking companies that combine strong fundamentals with appealing valuations through the 8 high quality undervalued stocks.
- Strengthen your income stream by spotting potential high-yield payers with resilient payouts via the 3 dividend fortresses.
- Dial down portfolio stress by focusing on businesses with steadier risk profiles using the 8 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com