


CAVA Group (CAVA) Names A New CMO, Is The Stock Too Pricey?
CAVA Group (CAVA) just appointed John Ludeke as Chief Marketing Officer, a move that puts an experienced consumer brand builder at the center of its national expansion and guest engagement efforts.
CAVA Group’s share price has softened recently, with a 1-day share price return of a 2.01% decline and a 90-day share price return down 24.88% at a last close of US$52.56. However, the 3-year total shareholder return of 54.68% signals that longer term investors have still seen meaningful gains despite a 1-year total shareholder return decline of 17.01% as the market reassesses growth prospects and risk around its expansion story and new leadership moves such as the CMO hire.
Scan beyond CAVA Group and size up other growth-focused restaurant operators and consumer brands with the 20 high quality undiscovered gems that are still flying under most investors’ radar.
CAVA Group now trades well below where many analysts peg fair value, with a wide gap between the US$52.56 share price and their target range. Is that discount justified once the assumptions get unpacked?
Most Popular Narrative: 36% Undervalued
CAVA Group’s most followed storyline pegs fair value at $82.75 against a last close of $52.56. The gap rests on how convincingly management can translate expansion, menu breadth and digital tools into durable earnings.
Current valuation implies the share price already reflects continued rapid unit growth, solid restaurant level margins in the mid 20s and effective use of cash including the US$100m buyback. As a result, the stock appears priced for strong execution rather than for disappointment.
See why 73 investors see CAVA Group as 36% undervalued.
Result: Fair Value of $82.75 (UNDERVALUED)
Still, CAVA Group’s story can change quickly if leadership depth lags its unit growth, or if fresh produce food safety scares resurface and hurt guest trust.
Find out about the key risks to this CAVA Group narrative.
Another View: What The P/E Ratio Says About CAVA Group
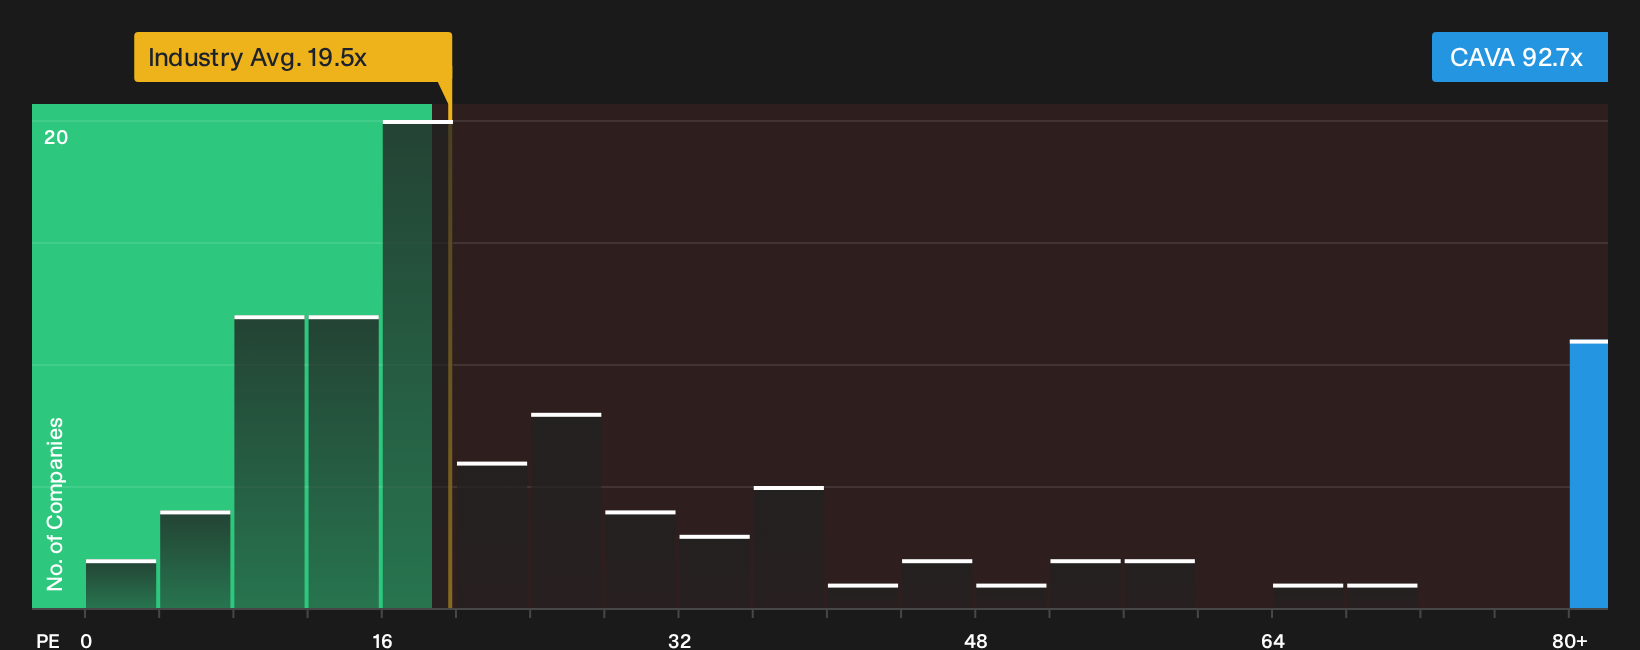
The story shifts when you stop at the income statement and look at what investors are paying for each dollar of CAVA Group earnings. The stock trades on a P/E of 92.7x, compared with 19.5x for the US Hospitality industry and 30.3x for peers, while the fair ratio sits at 27.5x. That gap points to meaningful valuation risk if sentiment cools or growth expectations ease. How comfortable are you with paying more than triple the fair ratio for this growth profile?
For a closer look at how that P/E premium stacks up against CAVA Group fundamentals, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this CAVA Group story feels split between promise and pressure, do not wait around for consensus to form before checking the details yourself and weighing the trade off between upside and risk. To see the full picture that investors are already debating, including 1 key reward and 1 important warning sign
Ready for more CAVA Group sized opportunities?
If CAVA Group has you rethinking what growth and valuation can look like, do not stop here. Broader ideas often shift a portfolio more than one stock.
Use the Simply Wall St screener to widen your net before the next move passes you by.
- Target potential mispricings by scanning a curated pool of companies that combine quality metrics with attractive valuations through the 29 high quality undervalued stocks.
- Build a more resilient core around your higher risk ideas by filtering for companies with stronger financing and liquidity profiles using the list of solid balance sheet and fundamentals (25 results).
- Hunt for overlooked stories that still show robust fundamentals by running a focused search with the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com