


Can Southern (SO) Justify Its Valuation After Its Utility Scale Solar Portfolio Update?
Southern (SO) drew fresh attention after a recent update on its utility scale solar portfolio, which outlined 17 GW of contracted large load deals and an 8 GW late stage pipeline supported by long term agreements.
Recent price action has been choppy for Southern, with the share price slipping around 9% over the past three months but supported by a 3.9% gain over the past week. Longer term total shareholder returns of about 43% over three years and 67% over five years point to sentiment that has improved over time, even as the 1 year total shareholder return is down roughly 8%.
Scan how Southern stacks up against peers by reviewing a hand picked 43 power grid technology and infrastructure stocks that are building and upgrading the backbone of tomorrow's electricity system.
After a sharp three month pullback, followed by a stronger recent bounce, Southern now sits at a crossroads for fresh capital. Do current fundamentals and contracted growth justify taking that risk for the potential reward?
Most Popular Narrative: 13% Undervalued
Southern's most followed narrative assigns a fair value of $99.76 using a 7.24% discount rate, compared with the recent $87.04 close. This frames today’s pullback as a gap between contracted growth plans and the current share price.
Accelerating large load and data center activity in Southern’s territories, including more than 17 GW of contracted large load agreements for the mid 2030s, a late stage pipeline of about 8 GW and a prospective funnel above 75 GW, points to a long runway of usage driven revenue and regulated rate base growth that may not be fully reflected in current valuation.
See why 67 investors see Southern as 13% undervalued.
Result: Fair Value of $99.76 (UNDERVALUED)
Still, the Southern story can wobble if large load contracts or project execution slip, or if equity and DOE backed funding pressures earnings instead of supporting them.
Find out about the key risks to this Southern narrative.
Another View: Southern Through The Earnings Lens
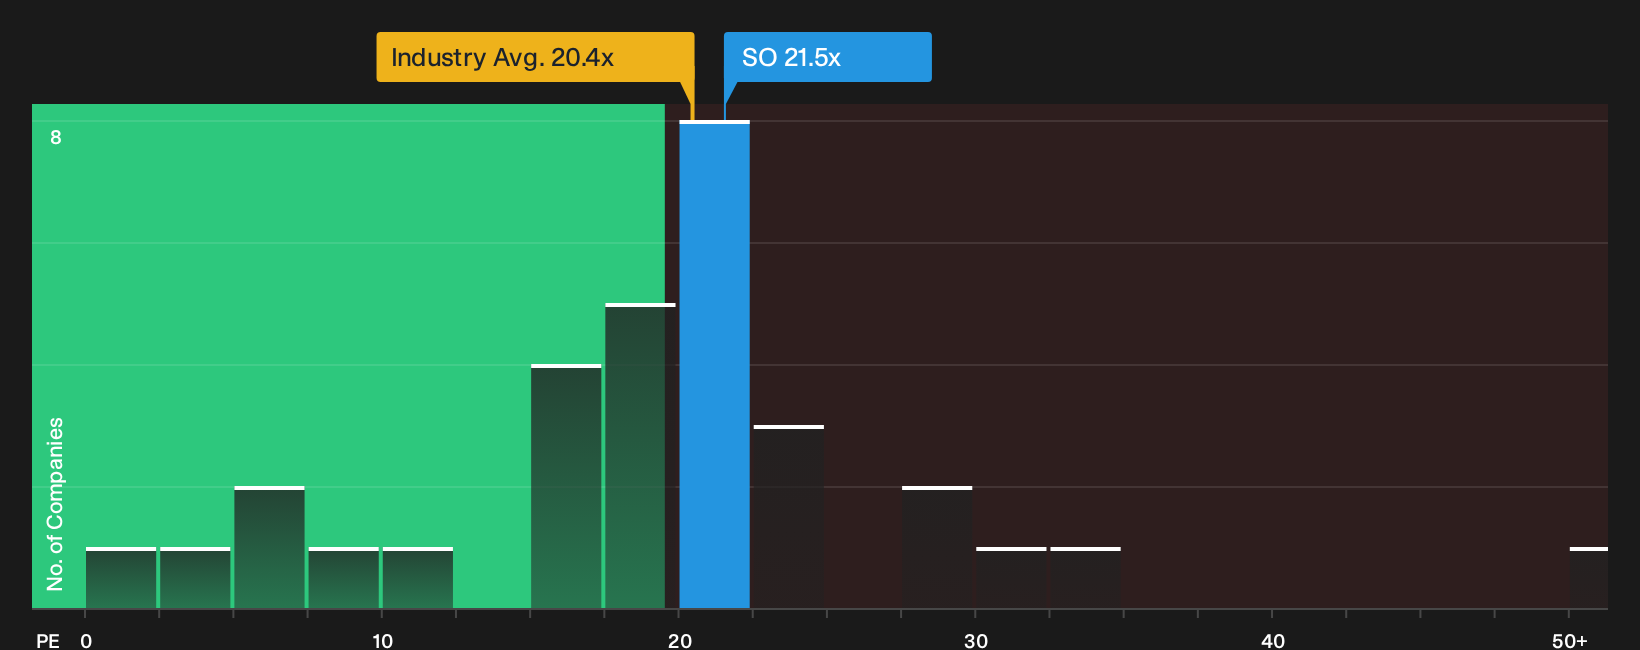
Set the DCF model to one side and Southern looks different on plain P/E math. The stock trades at about 21.5x earnings versus 20.4x for the US Electric Utilities group and 21.7x for close peers, while the fair ratio sits slightly higher at 22.1x.
That mix of a small premium to the sector, alignment with peers and a fair ratio just above today’s multiple points to limited margin of safety if expectations slip, yet only moderate valuation stretch if growth plans stay on track. Which of those two paths do you think the market is really paying for right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Southern so far. If the mix of potential risks and upsides matters to you, take a closer look at the 2 key rewards and 2 important warning signs
Looking For More Ideas Beyond Southern?
If Southern has you thinking harder about your portfolio, do not stop here. Fresh ideas often appear where the market pays less attention.
- Target higher income potential by scanning a curated 8 dividend fortresses that focuses on durable payouts rather than headline yield alone.
- Hunt for mispriced quality by reviewing a 29 high quality undervalued stocks that blends solid cash flows with balance sheets that can handle shocks.
- Reduce gut driven decisions by filtering for a 31 resilient stocks with low risk scores built to highlight businesses with steadier risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com