


Earnings Preview: What to Expect From Willis Towers Watson's Report
London, the United Kingdom-based Willis Towers Watson Public Limited Company (WTW) operates as an advisory, broking, and solutions company worldwide. Valued at $27.7 billion by market cap, the company provides a range of insurance brokerage, reinsurance, and risk management consulting services. The leading global advisory, broking, and solutions company is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Thursday, Oct. 29.
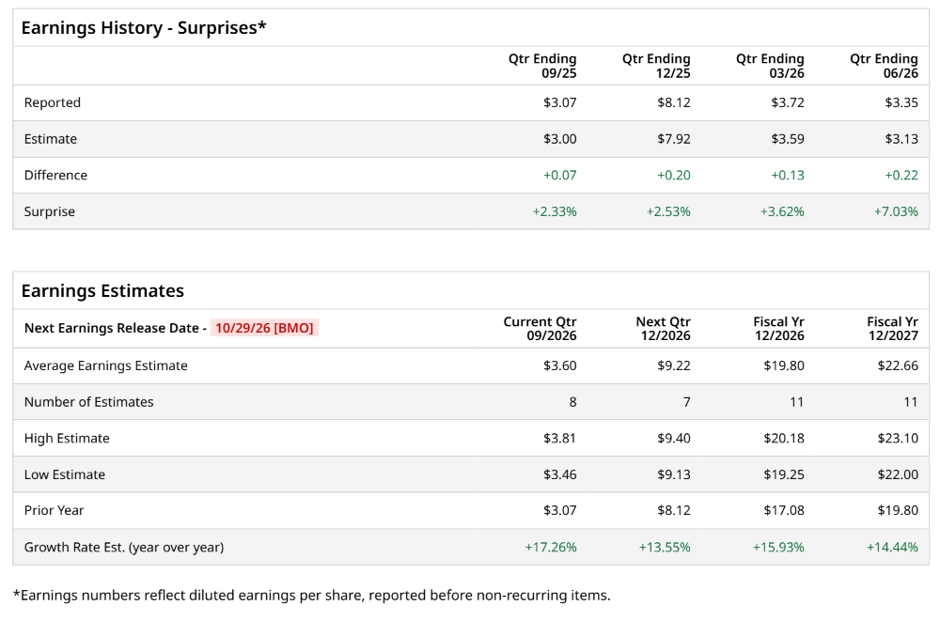
Ahead of the event, analysts expect Willis Towers Watson to report a profit of $3.60 per share on a diluted basis, up 17.3% from $3.07 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
For the full year, analysts expect Willis Towers Watson to report EPS of $19.80, up 15.9% from $17.08 in fiscal 2025. Its EPS is expected to rise 14.4% year over year to $22.66 in fiscal 2027.
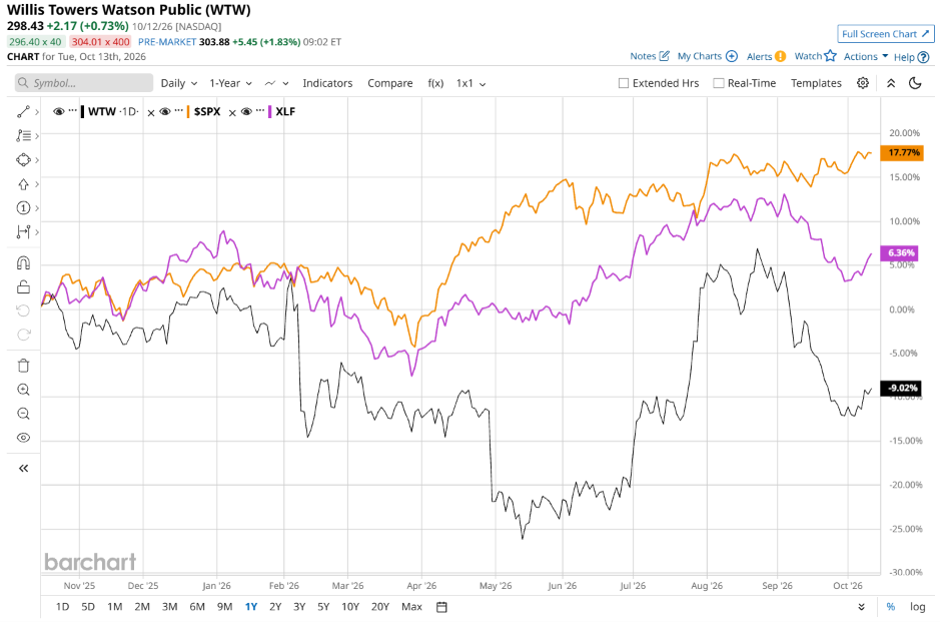
WTW stock has notably underperformed the S&P 500 Index’s ($SPX) 19.2% gains over the past 52 weeks, with shares down 10.6% during this period. Similarly, it underperformed the State Street Financial Select Sector SPDR ETF’s (XLF) 5.1% returns over the same time frame.
WTW has underperformed over the past year primarily due to disappointing organic revenue growth and softer-than-expected momentum in its core Risk & Broking and Health, Wealth & Career segments. Investors have penalized the stock for top-line deceleration and margin pressures that fell short of expectations relative to its larger brokerage peers, compounded by project delays, a softer commercial pricing environment, and initial cost headwinds from strategic investments and restructuring efforts.
Analysts’ consensus opinion on WTW stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 24 analysts covering the stock, 14 advise a “Strong Buy” rating, one suggests a “Moderate Buy,” and nine give a “Hold.” WTW’s average analyst price target is $370.19, indicating a potential upside of 24% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.