


How Investors Are Reacting To Vaisala Oyj Stock (HLSE:VAIAS) Raised 2026 Outlook
- Vaisala Oyj raised its full year 2026 outlook in October, lifting net sales guidance to €610 to €630 million and increasing its EBITA estimate, supported by growth and stronger profitability in the Industrial Measurements business area.
- The updated guidance explicitly excludes both the planned Atmo Inc. acquisition and any major market shifts, which helps investors isolate how Vaisala’s core operations are currently performing.
- We will now look at how Vaisala Oyj’s higher 2026 net sales and EBITA guidance may reshape the existing investment narrative.
Vaisala Oyj Investment Narrative Recap
To own Vaisala Oyj, you need to believe that demand for precise environmental and industrial measurements can support resilient sales and that the mix shift toward Industrial Measurements can sustain healthier EBITA over time. The higher 2026 net sales range, now €610 to €630 million, points to a still constructive operating backdrop within that framework.
The key short term swing factor remains how quickly order flow in more cyclical areas like renewable energy and public meteorology stabilises relative to the steadier Industrial Measurements activity. The raised guidance does not remove core risks around public sector budgets, currency moves, or trade policy, so those pressure points still matter.
The clearest related catalyst is Vaisala Oyj’s upcoming January to September 2026 interim report, due on 27 October 2026. Management has already flagged higher 2026 net sales and EBITA expectations, helped by Industrial Measurements, so investors now get a near term checkpoint on how that business area is tracking underneath the new numbers.
That update, together with the webcast hosted by the CEO and CFO, should give you better line of sight on order intake quality, any shifts in end market demand, and how pricing and margins in Industrial Measurements offset softer renewables or weather projects. Execution against the reiterated guidance range, without leaning on the planned Atmo Inc. acquisition, is likely the focus.
Vaisala Oyj's current analyst narrative points to revenues of €751.7 million and earnings of €104.5 million by 2029. This reflects assumed yearly top line growth of 7.5% and an earnings increase of about €39.2 million from €65.3 million today.
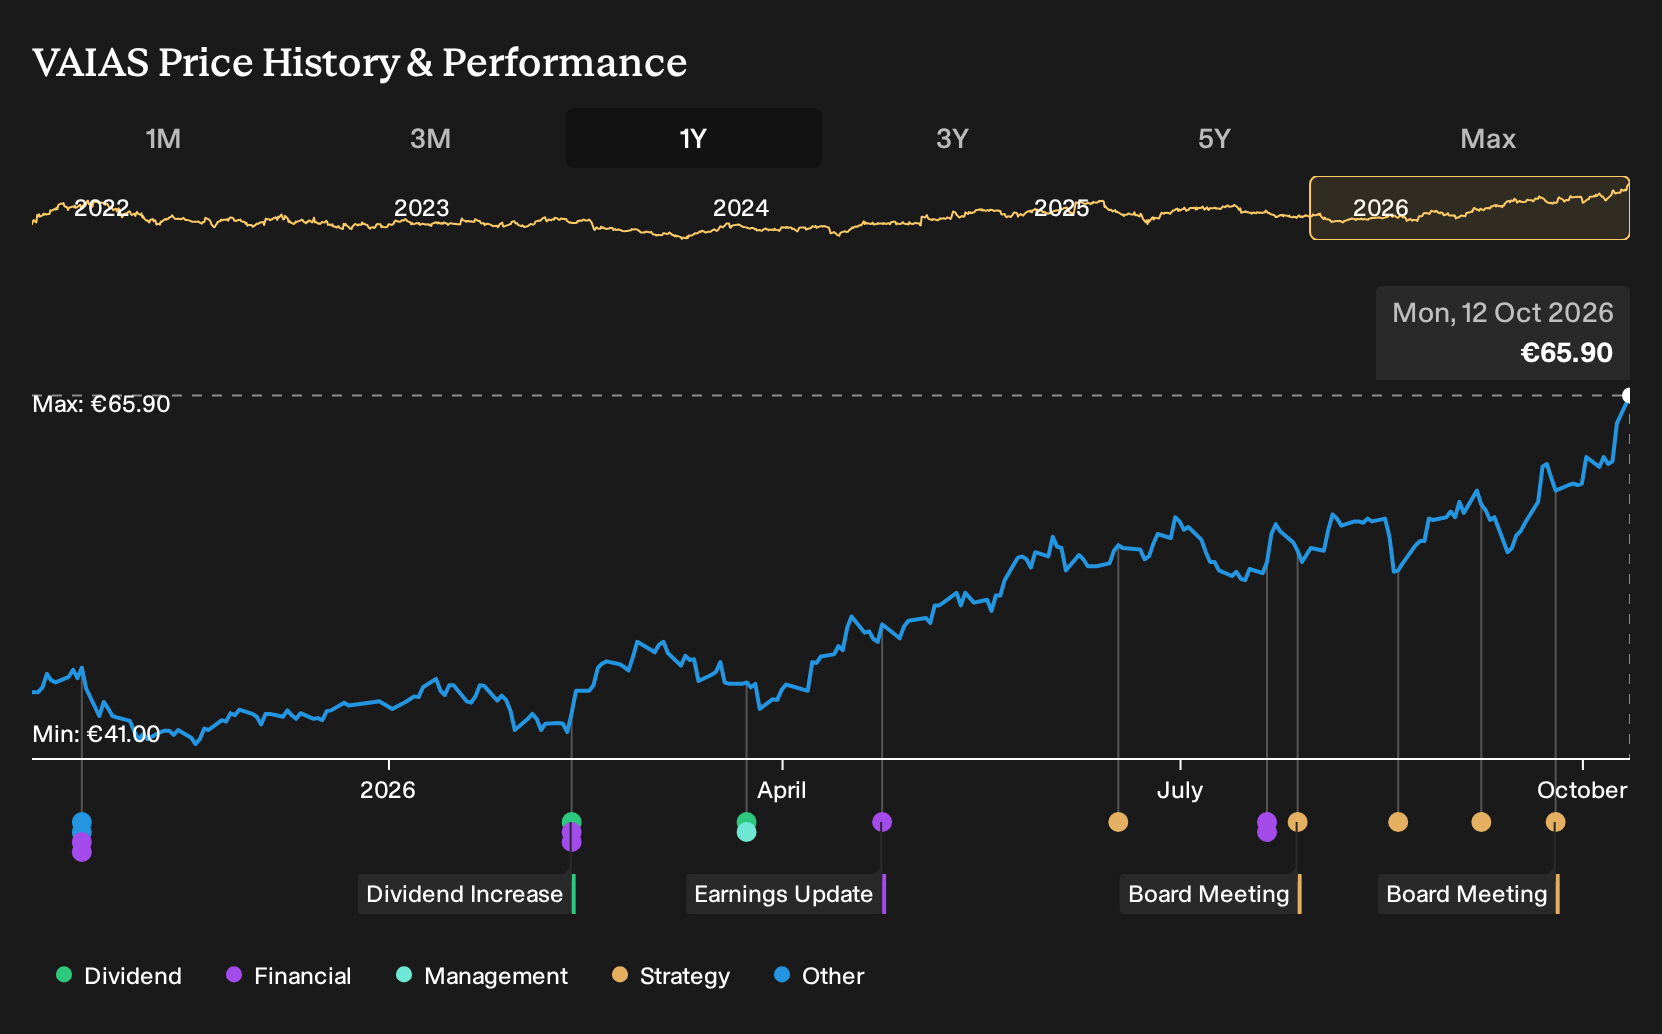
Uncover why Vaisala Oyj's fair value signals an 8% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster tightly between €60.8 and about €66.4, which hints at only a modest spread between bullish and cautious members. Those opinions predate the raised 2026 guidance from Vaisala Oyj and the upcoming October 27 interim report, so fresh numbers could shift how you weigh both upside and execution risk.
Explore 2 other Vaisala Oyj fair value estimates, including one that suggests as much as 8% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Vaisala Oyj research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Vaisala Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vaisala Oyj's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vaisala Oyj?
If the updated outlook for Vaisala Oyj has sharpened your thinking, use that momentum to broaden your watchlist with companies that fit different risk and quality profiles.
- For investors who want resilient balance sheets and robust fundamentals at the core of their portfolio, start with a list of solid balance sheet and fundamentals (202 results) that already meet those criteria.
- If income is a priority and you care about meaningful payouts backed by real businesses, shortlist companies from a 217 dividend fortresses that focus on higher yields.
- When you are hunting for underfollowed opportunities with solid metrics that the market may be overlooking, scan through a 620 high quality undiscovered gems that combine quality with lower visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com