


Marriott International (MAR), Why Is Its Latest Update Drawing Attention?
The opening of JW Marriott Costa Elena Resort & Spa gives Marriott International (MAR) a fresh all-inclusive concept in Costa Rica. For investors, this raises questions about capital efficiency, brand reach, and long term return potential.
Marriott International shares trade at US$369.30, with a 30 day share price return of 10.34% and a year to date share price return of 17.83%. Total shareholder return over the past 12 months sits at 41.45% and extends to 141.95% over five years, suggesting investors have recently been rewarding the business for its expansion moves such as the Costa Elena launch and reassessing both its growth potential and risk profile over time.
Scan how Marriott International's momentum compares with other travel and leisure plays by checking a curated set of 20 high quality undiscovered gems that may not yet be on most investors' radars.
Marriott International now trades only slightly below analyst targets, even as the new Costa Elena all inclusive concept introduces fresh execution questions. The key issue is whether that small discount is enough to compensate for the added risk and ambition.
Most Popular Narrative: 3% Undervalued
On the most followed view, Marriott International screens as slightly undervalued, with a fair value of $380.80 versus a last close of $369.30. This puts the focus squarely on how repeatable its fee engine really is.
Diversification of high margin offerings and alternate fee streams continues to build, as luxury and premium properties show higher RevPAR in recent quarters and co branded credit card economics are expected to add about US$30 million of incremental 2026 fees and potentially US$100 million to US$125 million of incremental annual fees by 2028, which supports higher gross fee revenue and earnings.
See why 31 investors see Marriott International as 3% undervalued.
Result: Fair Value of $380.80 (UNDERVALUED)
Still, the Marriott International thesis leans on assumptions that could crack if Middle East travel remains weak or if Bonvoy economics fail to reignite owner growth.
Find out about the key risks to this Marriott International narrative.
Another View: Rich Multiples For Marriott International
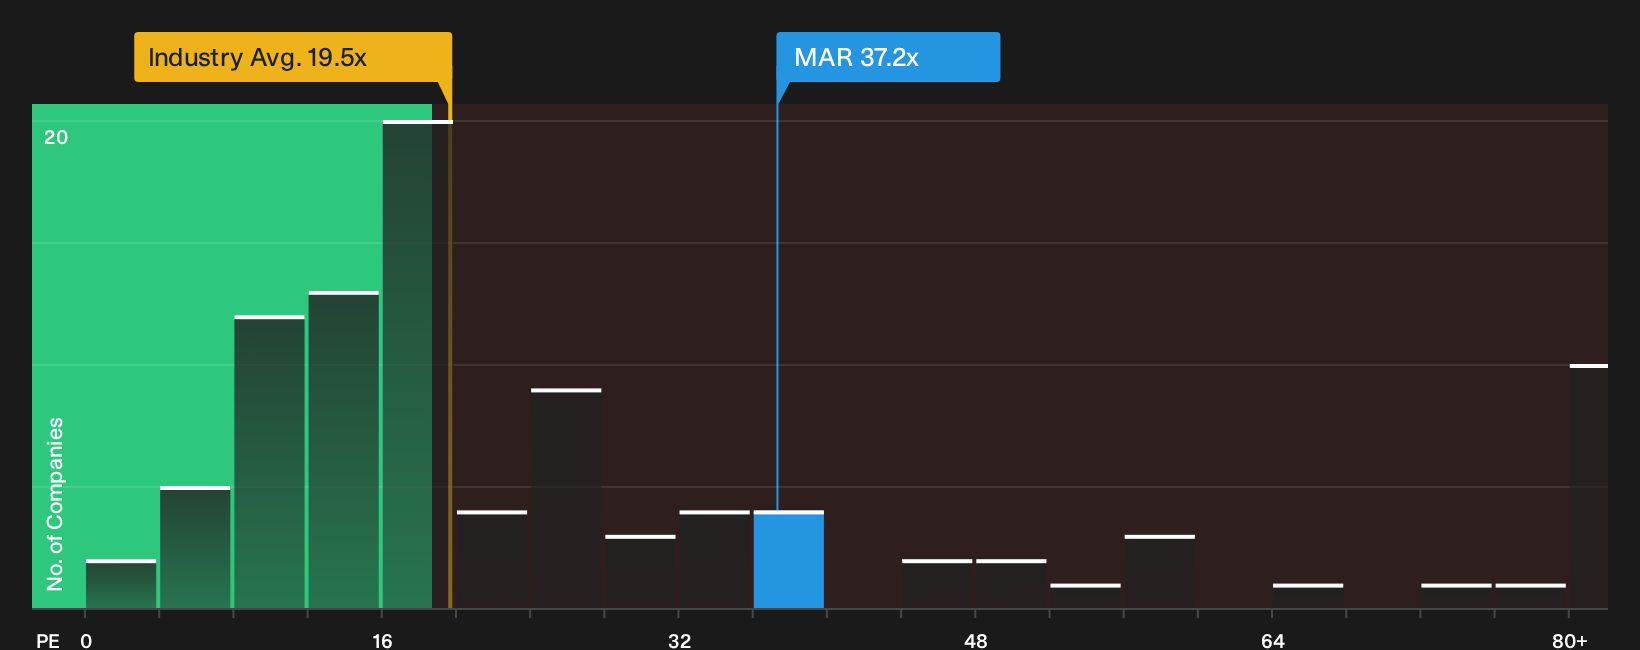
Look past that 3% gap to fair value and Marriott International starts to look expensive on simple earnings math. The stock trades on a P/E of 37.2x, while the US Hospitality industry sits at 19.5x and direct peers average 29x. The fair ratio is 27.1x, which is the level the market could move toward if enthusiasm cools. That leaves you weighing how much execution risk around Costa Elena and fee growth you are willing to pay up for.
Before leaning too hard on one narrative, it is worth seeing what the numbers say at different earnings multiples through the full valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
For a clearer visual on how Marriott International’s current earnings multiple lines up against peers and the wider sector, review the comparison chart here:
Next Steps
Mixed messages around Marriott International's price and risk reward profile are clear. Move quickly, pull up the underlying data, and weigh it against your own expectations as an investor. To see how the upside case and the risk list stack up side by side, review the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Marriott International?
Use what you have learned from Marriott International, then widen the lens so your portfolio is not tied to a single story or sector.
Do not leave potential value on the table when you can scan 29 high quality undervalued stocks that combine strong fundamentals with pricing that may not yet reflect their strengths.
Protect your downside by reviewing 31 resilient stocks with low risk scores that score well on resilience and may help steady your overall returns when conditions get tougher.
Balance those ideas with a 8 dividend fortresses that can introduce reliable income into your mix while you wait for capital gains to materialize.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com