


What UMH Properties Shares Board Challenge Means For Shareholders
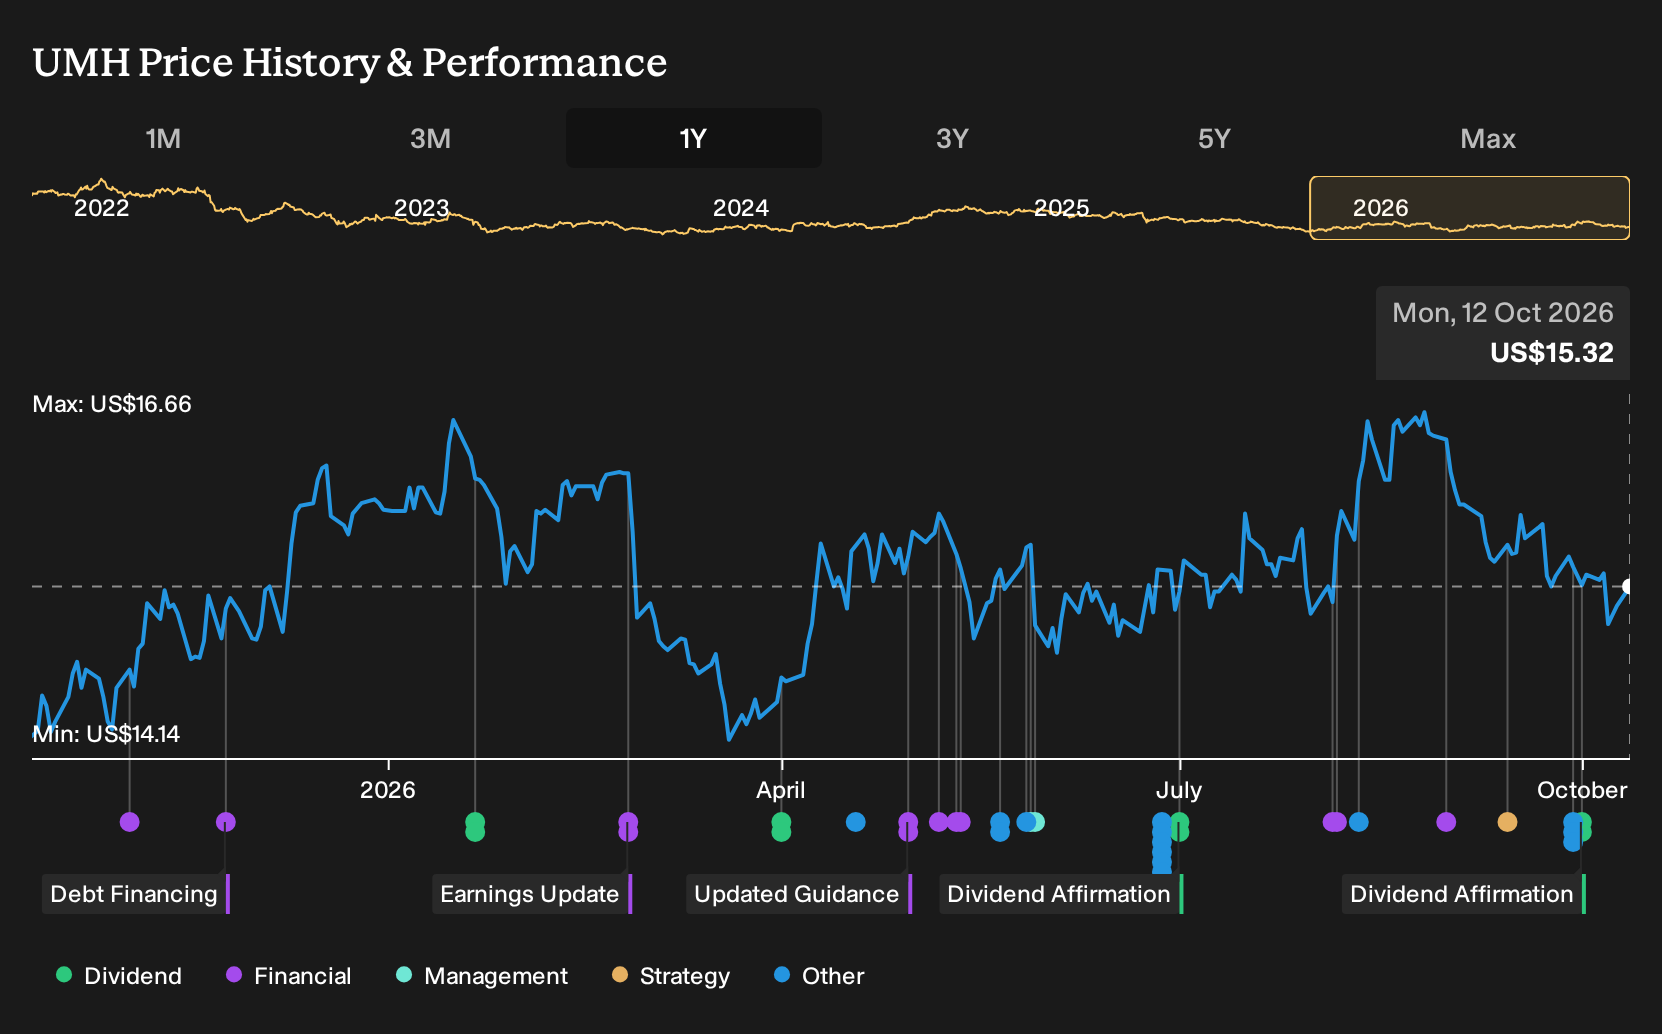
- UMH Properties’ board recently declared quarterly cash dividends of $0.225 per common share and $0.3984375 per Series D preferred share, both payable on December 15, 2026, to shareholders of record on November 16, 2026.
- The dividend affirmations arrive at the same time that Erez Asset Management is publicly pushing for board changes, placing UMH Properties’ capital allocation and governance decisions under increased scrutiny.
- We will now look at how UMH Properties’ investment narrative could shift as Erez’s board campaign challenges management’s current direction.
UMH Properties Investment Narrative Recap
For UMH Properties, the basic belief is that affordable manufactured housing and occupancy in its 145 communities can support steady rental income, with home sales and self storage as add ons. The most important near term catalyst is still execution on new developments and acquisitions, which management previously flagged as uncertain. The fresh dividend affirmations do not materially change that operational picture.
The biggest risk remains funding that growth while interest payments are not well covered by earnings and while dividends are not fully covered either. Higher borrowing costs could squeeze margins further if external capital needs of roughly $120 million to $150 million each year continue without a clear pipeline of accretive projects.
The October 1 decision to maintain a quarterly dividend of $0.225 per common share and $0.3984375 on the Series D preferred puts UMH Properties’ capital allocation in sharper focus as Erez Asset Management presses for change. Income focused holders now have a concrete payout level to weigh against concerns around dividend coverage and interest burdens.
For catalysts, that payout commitment can cut both ways. On one hand, a stable $0.90 per share annual common dividend may keep income oriented investors engaged while activist pressure highlights governance and capital structure questions. On the other hand, if earnings or financing costs move against the business, that same cash obligation could limit flexibility just as the board is under public scrutiny.
UMH Properties' analyst narrative points to forecast revenue of US$330.1 million and projected earnings of US$19.7 million by 2029, based on an assumed 7.5% yearly revenue growth and an earnings increase of about US$10.9 million from current earnings of US$8.8 million.
Uncover why UMH Properties' fair value indicates a 27% potential upside to its current price before the discount to UMH Properties' shares narrows.
Exploring Other Perspectives
For UMH Properties, the most bearish twist in the story comes from margins. The lowest analysts were modelling profit margins slipping to 2.2% and earnings of about US$7.3 million by 2029, even while revenue estimates hovered near US$333.8 million. Those forecasts were set before this dividend decision and Erez’s campaign, so opinions may evolve as new information lands.
Explore 2 other UMH Properties fair value estimates, including one that suggests it could be worth just $18.88!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your UMH Properties research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for UMH Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UMH Properties' overall financial health at a glance.
Looking for more investment ideas beyond UMH Properties?
If UMH Properties has you thinking more broadly about income potential, balance sheet strength, and where risk really sits in your portfolio, it can help to line it up against a wider field of candidates using the Simply Wall St Screener.
- For investors who want yield supported by resilience, check out a curated 8 dividend fortresses that may help you spot income opportunities with sturdier payouts.
- If capital preservation sits high on your priority list, scan a focused set of 31 resilient stocks with low risk scores that aim to keep volatility in check while still offering room for returns.
- When you are hunting for quality that the wider market may be overlooking, use the 20 high quality undiscovered gems to surface under-followed businesses with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com