


3 UK Penny Stocks With Market Caps Under £400M To Consider
The United Kingdom's markets have recently faced challenges, with the FTSE 100 and FTSE 250 indices experiencing declines amid concerns over China's economic recovery. Despite these broader market pressures, penny stocks—often representing smaller or newer companies—continue to attract attention for their potential value and growth opportunities. While the term "penny stocks" may seem outdated, these investments can still offer intriguing prospects when backed by solid financials and a clear path forward.
Below we spotlight a couple of our favorites from our exclusive screener.
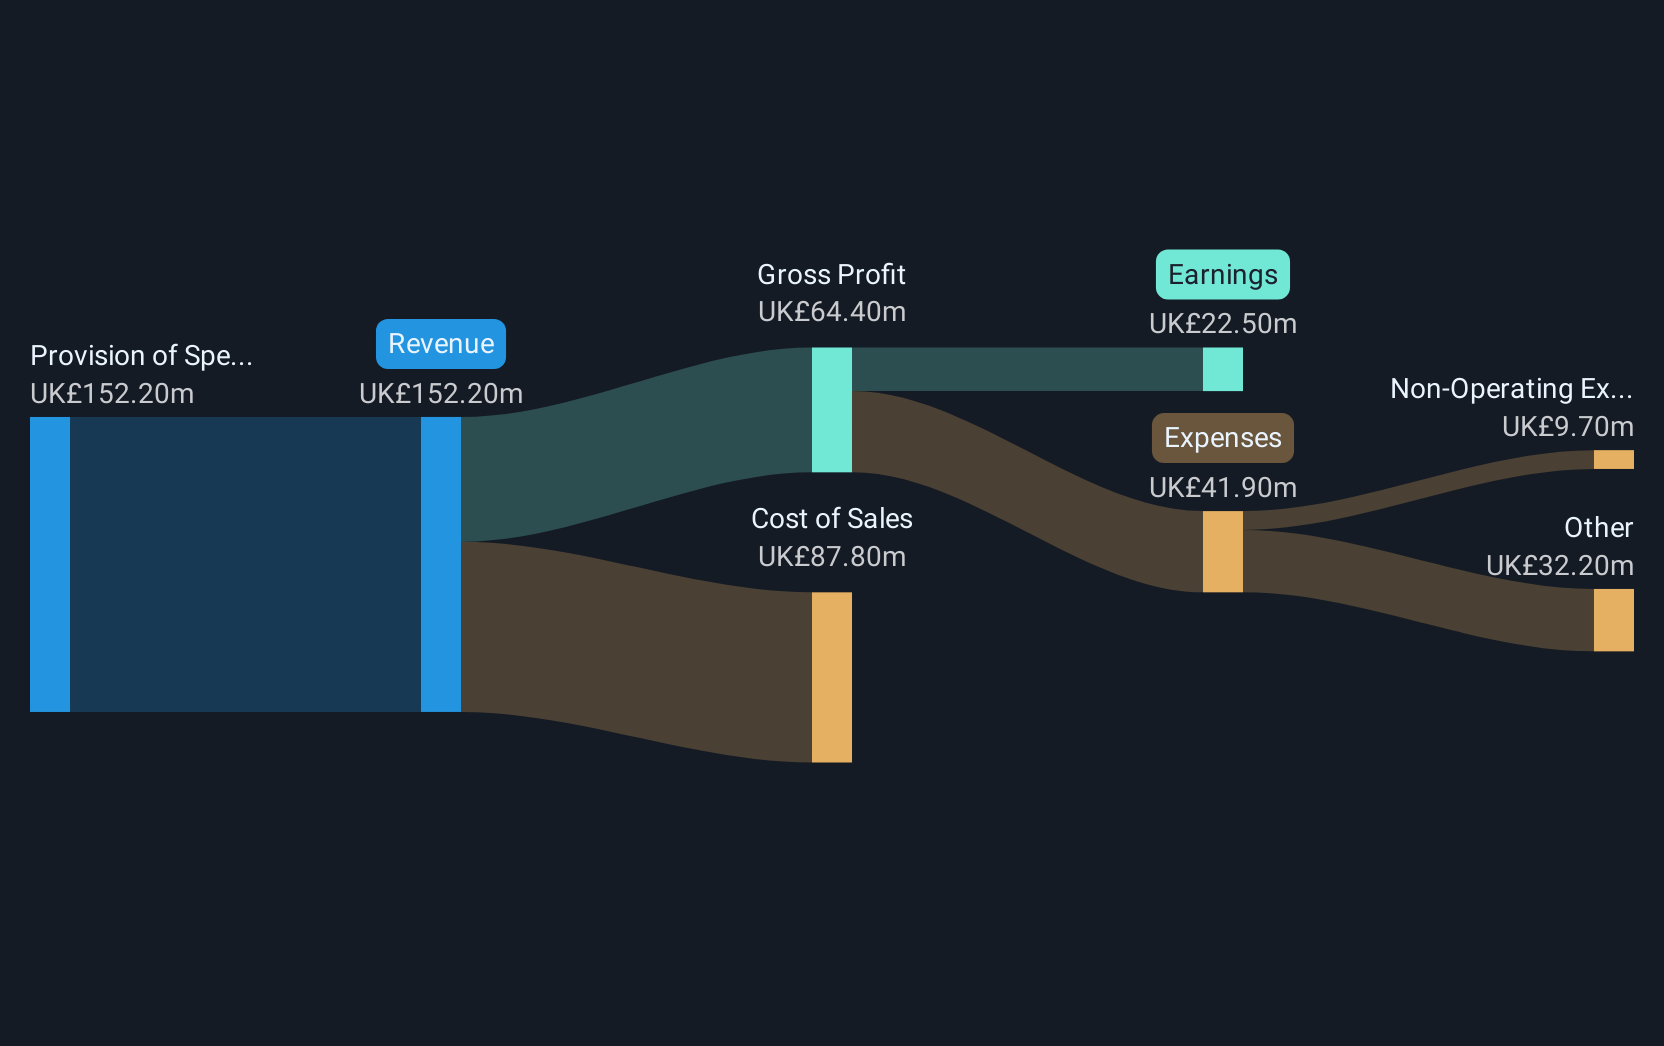
FRP Advisory Group (AIM:FRP)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: FRP Advisory Group plc offers business advisory services to companies, lenders, investors, individuals, and other stakeholders in the United Kingdom with a market cap of £281.59 million.
Operations: The company generates £177 million in revenue from its specialist business advisory services segment.
Market Cap: £281.59M
FRP Advisory Group, with a market cap of £281.59 million, presents a compelling case in the penny stock arena due to its robust financial health and growth trajectory. The company is debt-free, with short-term assets significantly exceeding both short and long-term liabilities, indicating strong liquidity. Earnings have grown by 17.9% annually over the past five years, supported by high-quality earnings and a return on equity of 23.5%. Recent dividend increases reflect confidence in sustained profitability, while analysts suggest potential for significant stock price appreciation. However, recent earnings growth has slightly decelerated compared to its historical average.
- Take a closer look at FRP Advisory Group's potential here in our financial health report.
- Assess FRP Advisory Group's future earnings estimates with our detailed growth reports.
Personal Group Holdings (AIM:PGH)
Simply Wall St Financial Health Rating: ★★★★★★
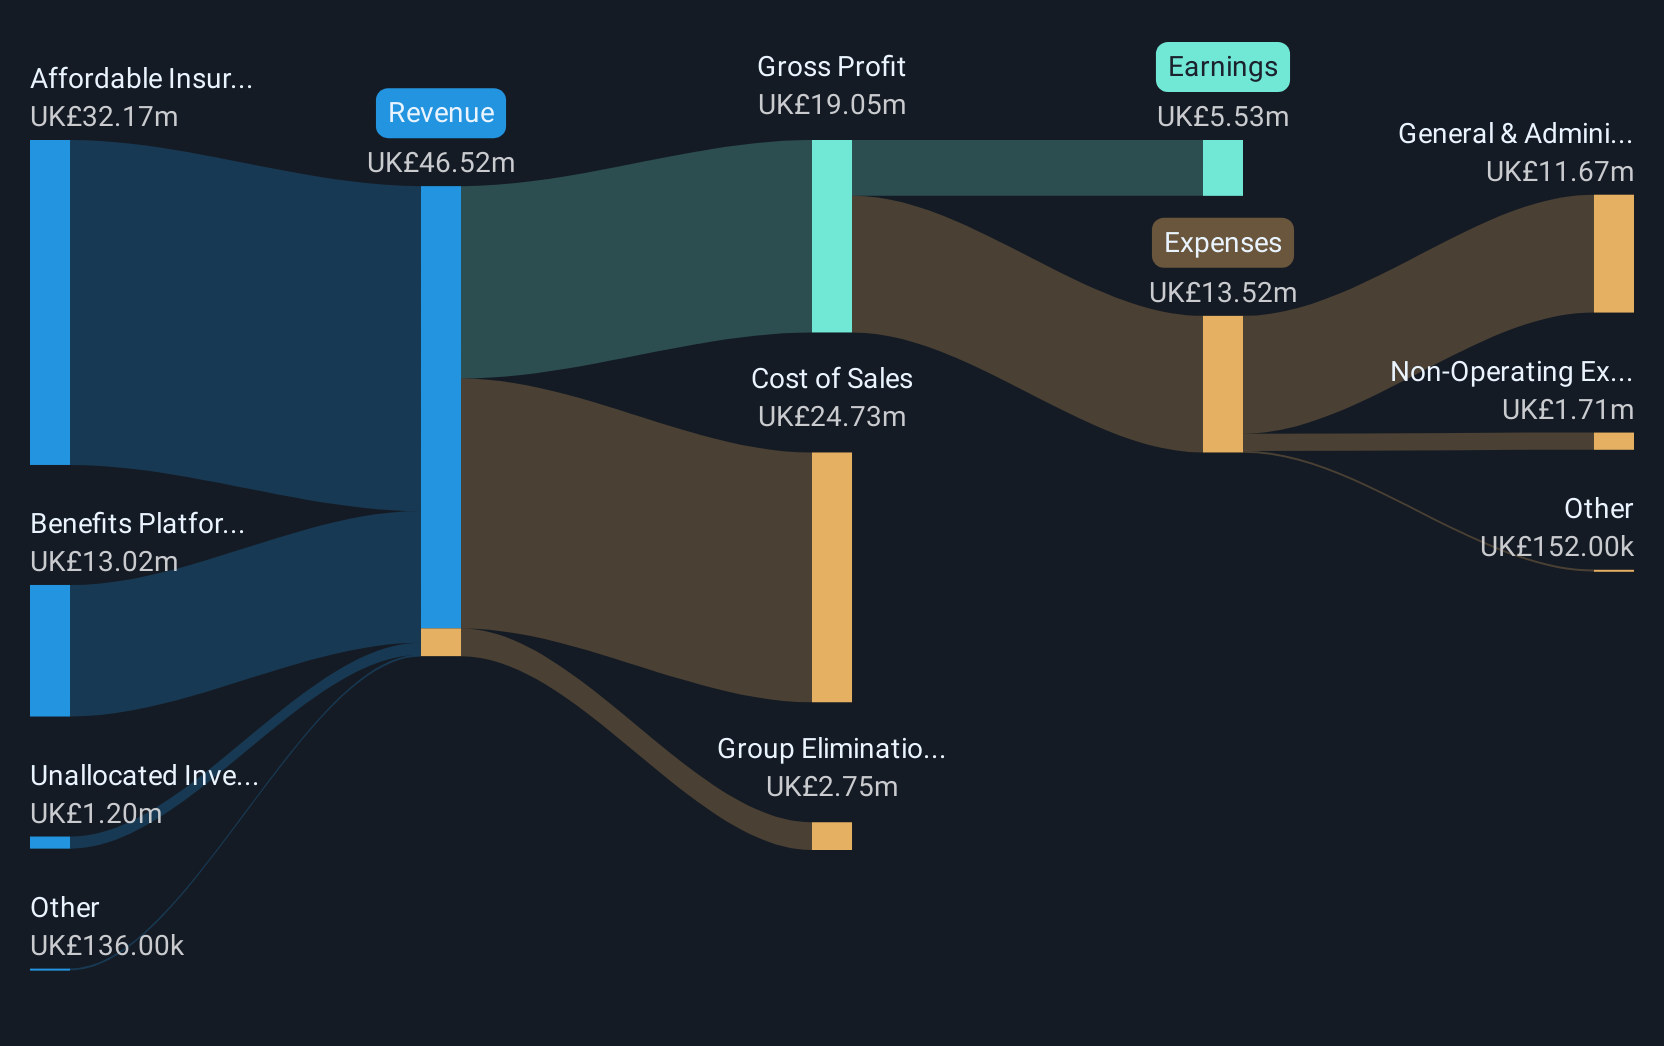
Overview: Personal Group Holdings Plc provides employee services and salary sacrifice technology products in the United Kingdom, with a market cap of £137.37 million.
Operations: The company's revenue is primarily generated from two segments: Affordable Insurance, contributing £38.21 million, and Benefits & Reward, which adds £14.09 million.
Market Cap: £137.37M
Personal Group Holdings, with a market cap of £137.37 million, stands out in the penny stock sector due to its debt-free status and solid financial performance. The company reported half-year revenue of £25.68 million and net income of £3.87 million, reflecting growth from the previous year. Its return on equity is high at 22.6%, supported by stable profit margins and undiluted shareholder value over the past year. Despite a dividend yield that isn't fully covered by earnings, recent increases indicate management's confidence in future profitability. A strategic partnership with Simplyhealth enhances its employee benefits platform, potentially expanding market reach.
- Click here to discover the nuances of Personal Group Holdings with our detailed analytical financial health report.
- Gain insights into Personal Group Holdings' future direction by reviewing our growth report.
Luceco (LSE:LUCE)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: Luceco plc, with a market cap of £313.22 million, designs, manufactures, and delivers residential and commercial electrification products and systems across the United Kingdom, Europe, the Americas, the Middle East, Africa, and the Asia Pacific.
Operations: The company's revenue is derived from three main segments: LED Lighting (£80.6 million), Portable Power (£72.4 million), and Wiring Accessories (£135.3 million).
Market Cap: £313.22M
Luceco plc, with a market cap of £313.22 million, has shown significant earnings growth of 44.1% over the past year, surpassing its five-year average decline. Despite trading at 28.7% below estimated fair value and having high-quality earnings, its high net debt to equity ratio of 63.4% raises concerns about financial leverage. Recent leadership changes with Dr. Thorsten Müller as CEO may drive strategic acquisitions and investments in electrification markets like EV chargers and solar panels, aligning with Luceco's capital allocation policy while maintaining comfortable leverage at 1.5x bank EBITDA for potential M&A activities.
- Dive into the specifics of Luceco here with our thorough balance sheet health report.
- Understand Luceco's earnings outlook by examining our growth report.

Key Takeaways
- Investigate our full lineup of 253 UK Penny Stocks right here.
- Curious About Other Options? The latest GPUs need a type of rare earth metal called Neodymium and there are only 33 companies in the world exploring or producing it. Find the list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com