


VEON (VEON) Stock Looks Richly Priced On Its Bangladesh Satellite Launch
VEON Ltd. has delivered a powerful run in recent years, and the question now is whether the current share price lines up with what its earnings can support. After a move like this, investors often want to know if they are paying a fair price for the profit engine behind the story.
- Over the past 3 years, VEON has produced a very large total return of about 4.2x, which puts a lot more weight on whether the present earnings justify the market's optimism.
- Recent moves into satellite to mobile services, AI powered telecom operations and expanded investment plans in markets such as Bangladesh, Kazakhstan and Pakistan can shape expectations for future profit margins and the level of reinvestment needed to support those ambitions.
- Your read on VEON is one view; the desks covering it have another. See what analysts think VEON's shares could be worth.
The issue now is whether VEON's current valuation can be explained by the level and quality of the earnings the business is generating today.
If you are weighing VEON against other telecoms leaning into AI and digital infrastructure, it can help to compare it with 92 AI infrastructure stocks.
Is VEON Getting Expensive on Earnings?
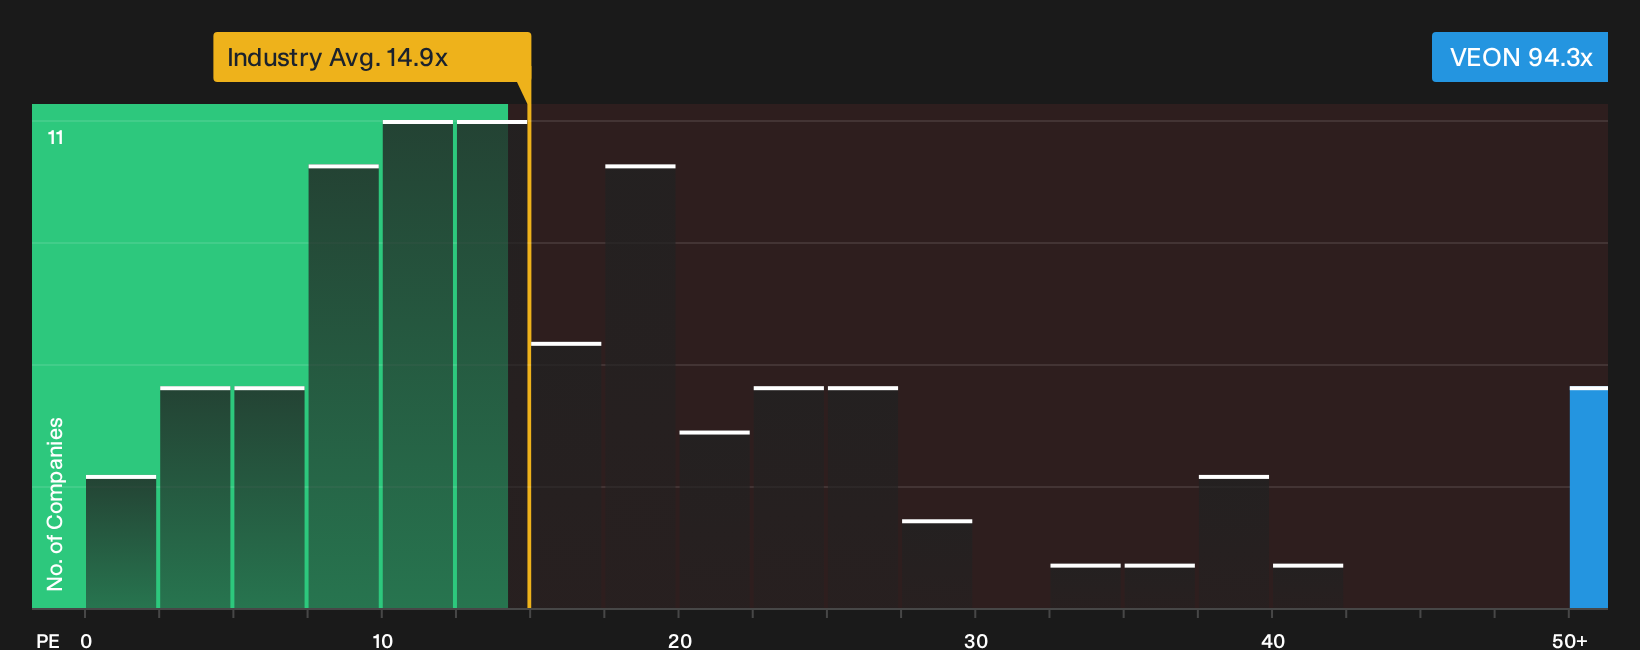
The P/E ratio is a useful fit for VEON because earnings are still a key yardstick for how the market prices telecom and digital service platforms. Right now, VEON trades on about 94.3x earnings, which is far above the Wireless Telecom industry average of 14.9x and also well above the broader peer group on roughly 12.6x. Against a tailored fair P/E, which is the multiple implied by VEON's growth profile, margins, size and risk, the current level screens as overvalued. The gap is large enough that the model is effectively flagging how steep the earnings premium has become rather than pointing to a precise fair value.
Because the stock is already pricing in a lot of good news, the recent satellite to mobile launches with Starlink in markets like Bangladesh and Kazakhstan, plus the AI focused deal with Amdocs, appear to be reinforcing a rich valuation rather than leaving obvious room in the P/E. Anyone comparing VEON to other telecoms leaning into digital infrastructure has to decide whether this kind of earnings multiple still leaves enough margin for error. Explore the numbers behind VEON's P/E valuation.
The VEON Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where VEON's rich P/E debate leaves off. They spell out which paths for revenue growth, profitability and earnings power would need to play out for the stock to trade materially higher or lower than it does today, and set out those building blocks rather than a single model output so you can come back to see how those assumptions stack up against actual results as they arrive on VEON's Community page.
Community views on VEON split between those who see digital services and capital returns as underappreciated, and others who think the risk profile already looks fully priced in.
Bull case: 7% undervalued
"VEON is aggressively expanding digital service offerings in emerging markets that are rapidly digitalizing and seeing surging demand for mobile internet and data…"
Discover why this Narrative puts VEON at 7% undervalued.
Bear case: 10% overvalued
"Its concentration in politically and economically unstable regions like Ukraine, Pakistan, and Bangladesh creates the risk of recurring operational disruptions…"
Explore why this Narrative puts VEON at 10% overvalued.
One more VEON question that could change the whole earnings story
Everything so far has focused on what VEON looks like today, yet professional coverage also sketches out where they expect this business to be a few years from now, and that forward view can sharply reframe the current multiple. Explore where analysts expect VEON to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com